Commercial Auto vs. Personal Auto Insurance

Choosing the right insurance policy for your vehicle is based on more than just what type of vehicle you have. The purpose of your vehicle is also an important part of your choice. A car used for every day, personal use has needs different insurance policies than the vehicle you use in your business. When reviewing your options and situation, it becomes clearer whether you need commercial or personal auto insurance.


What Is Commercial Auto Insurance?

Commercial auto insurance covers vehicles that are used when operating a business. Business vehicles can involve additional risks and may carry different equipment which may be covered with the help of commercial auto insurance.

Commercial auto insurance can cover vehicles that transport employees and equipment including:

  • company cars
  • delivery vehicles
  • service vans & trucks

Commercial auto policies can provide liability and damage coverage while also accounting for risks that come with operating a business.


What Is Personal Auto Insurance?

Personal auto insurance is generally created to cover vehicles that are used for personal, everyday use. A personal auto policy may include liability, collision, comprehensive, uninsured motorist coverage, and other options depending on the insurance agency and state laws.

Vehicles used for personal transportation may include vehicles used for commuting, shopping, visiting friends and family, and taking personal trips.

Personal auto insurance policies may have limitations when using it for an operating business. If you regularly use your vehicle to earn income or conduct business, it’s important to check with your agent and see if there are better coverage options.


Key Takeaways

The biggest differences between the two insurance policies include vehicle use, ownership, exposure to liabilities, and drivers.

  • Personal insurance is generally intended for personal driving. Commercial insurance is designed for regular business use.
  • A personally owned vehicle used for personal reasons will have personal auto insurance. Vehicles owned by a business may require commercial coverage.
  • Commercial vehicles may be driven by employees or multiple authorized drivers, creating additional risks.
  • Business vehicle accidents can potentially expose both the driver and the business to claims.


Both personal and commercial auto insurance play important roles when it comes to choosing the right coverage for your vehicle. Personal auto insurance focuses on everyday personal transportation, while commercial auto insurance addresses risks associated with business activities.  Reviewing your policy with an insurance agent can help you make the right choice whenever your vehicle’s use, ownership, or drivers change. Having coverage that corresponds with your vehicle use and purpose can help reduce the risk of unexpected coverage issues.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

Tips to Reduce Insurance claims on the Job Site

A job site can change quickly, and even a small mistake can turn into an expensive problem. One loose tool, an unsecured ladder, a distracted driver, or an overlooked safety hazard could lead to an injury, damaged property, stolen equipment, or a costly insurance claim. For contractors, these incidents can also mean project delays, lost productivity, and added stress for both employees and customers.

While not every accident can be prevented, many common job-site claims can be reduced with proper planning, training, and safety procedures. Taking a proactive approach to risk management can help protect your employees, your equipment, your customers, and your business. By creating safer work habits and addressing hazards before they become problems, contractors can reduce the likelihood of claims and keep projects moving more smoothly.

So here are some of the best tops to reduce insurance claims on the job site:

1. Strengthen Onboarding and Training

Proper training can help prevent many common job-site accidents. New employees should understand safety procedures, how to use equipment correctly, and what is expected of them before working independently.

Regular toolbox talks and refresher training can also help reinforce safe habits and address new risks as job sites and responsibilities change.

Contractors should consider training employees on:

  • Proper equipment and tool use
  • Fall prevention
  • Safe lifting techniques
  • Personal protective equipment
  • Emergency procedures
  • Vehicle and machinery safety

Making safety training part of the company’s normal routine can help employees recognize hazards before they lead to an accident.

2. Target High‑Risk Groups

Some employees and job duties may require extra attention. New workers, temporary employees, and anyone performing unfamiliar or hazardous tasks may benefit from additional training and supervision.

High-risk activities such as working at heights, operating heavy machinery, or handling electrical work should also receive closer oversight to help prevent accidents

3.Require proper PPE

Personal protective equipment, or PPE, can help reduce the severity of injuries when accidents happen. The type of PPE required will depend on the work being performed, but employees should always have access to the proper safety equipment for their job.

Common examples include:

  • Hard hats
  • Safety glasses or goggles
  • Work gloves
  • High-visibility clothing
  • Hearing protection
  • Steel-toed boots
  • Respirators
  • Fall-protection equipment

Simply providing PPE is not enough. Employers should also make sure employees understand how to use it correctly and that damaged or worn-out equipment is replaced when necessary.

4. Inspect Tools and Equipment Regularly

Damaged or poorly maintained equipment can quickly become a safety hazard. Tools, ladders, scaffolding, vehicles, and machinery should be inspected regularly and repaired when needed.

Employees should also be encouraged to report damaged equipment right away. If something is unsafe, it should be removed from use until it can be repaired or replaced.

5. Have a Clear Incident-Reporting Process

Employees should know exactly what to do if an accident, injury, property damage, or near miss occurs. A clear reporting process helps the company respond quickly and document what happened.

Photos, witness statements, and written reports can all be useful. Near misses should also be reviewed because they may reveal hazards that could lead to a more serious accident later.

6. Review Your Contractor Insurance Regularly

Even with strong safety procedures, accidents can still happen. Contractors should regularly review their insurance coverage as the business changes and grows.

Hiring employees, adding vehicles, buying equipment, or taking on larger projects can all affect insurance needs. Coverage may include general liability, workers’ compensation, commercial auto, tools and equipment coverage, builders risk, and umbrella liability.

Depending on the business, contractor insurance may include:

  • General liability insurance
  • Workers’ compensation
  • Commercial auto insurance
  • Tools and equipment coverage
  • Commercial property insurance
  • Builders risk insurance
  • Umbrella liability coverage

An annual insurance review can help identify coverage gaps and make sure the business is prepared if a loss occurs.

Conclusion

Reducing insurance claims starts with creating a safer, more prepared job site. Proper training, regular equipment inspections, the right protective gear, and clear reporting procedures can all help lower the chances of accidents and costly losses. While not every incident can be prevented, taking proactive steps can make a major difference.

Contractors should also review their insurance coverage regularly to make sure it keeps up with changes in the business. The right combination of strong safety practices and proper insurance protection can help protect your employees, your projects, and the future of your business.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes


Crown Point Apartment Policy: Protecting Your Investment and Tenants

Owning an apartment building in Crown Point comes with real financial responsibility. Standard homeowners insurance simply won’t cut it when you’re managing multiple units and tenants.

We at Briggs Agency, Inc. help local property owners understand what a proper Crown Point apartment policy actually covers and why it matters for your bottom line. This guide walks you through the protection you need.

What Your Apartment Building Policy Actually Covers

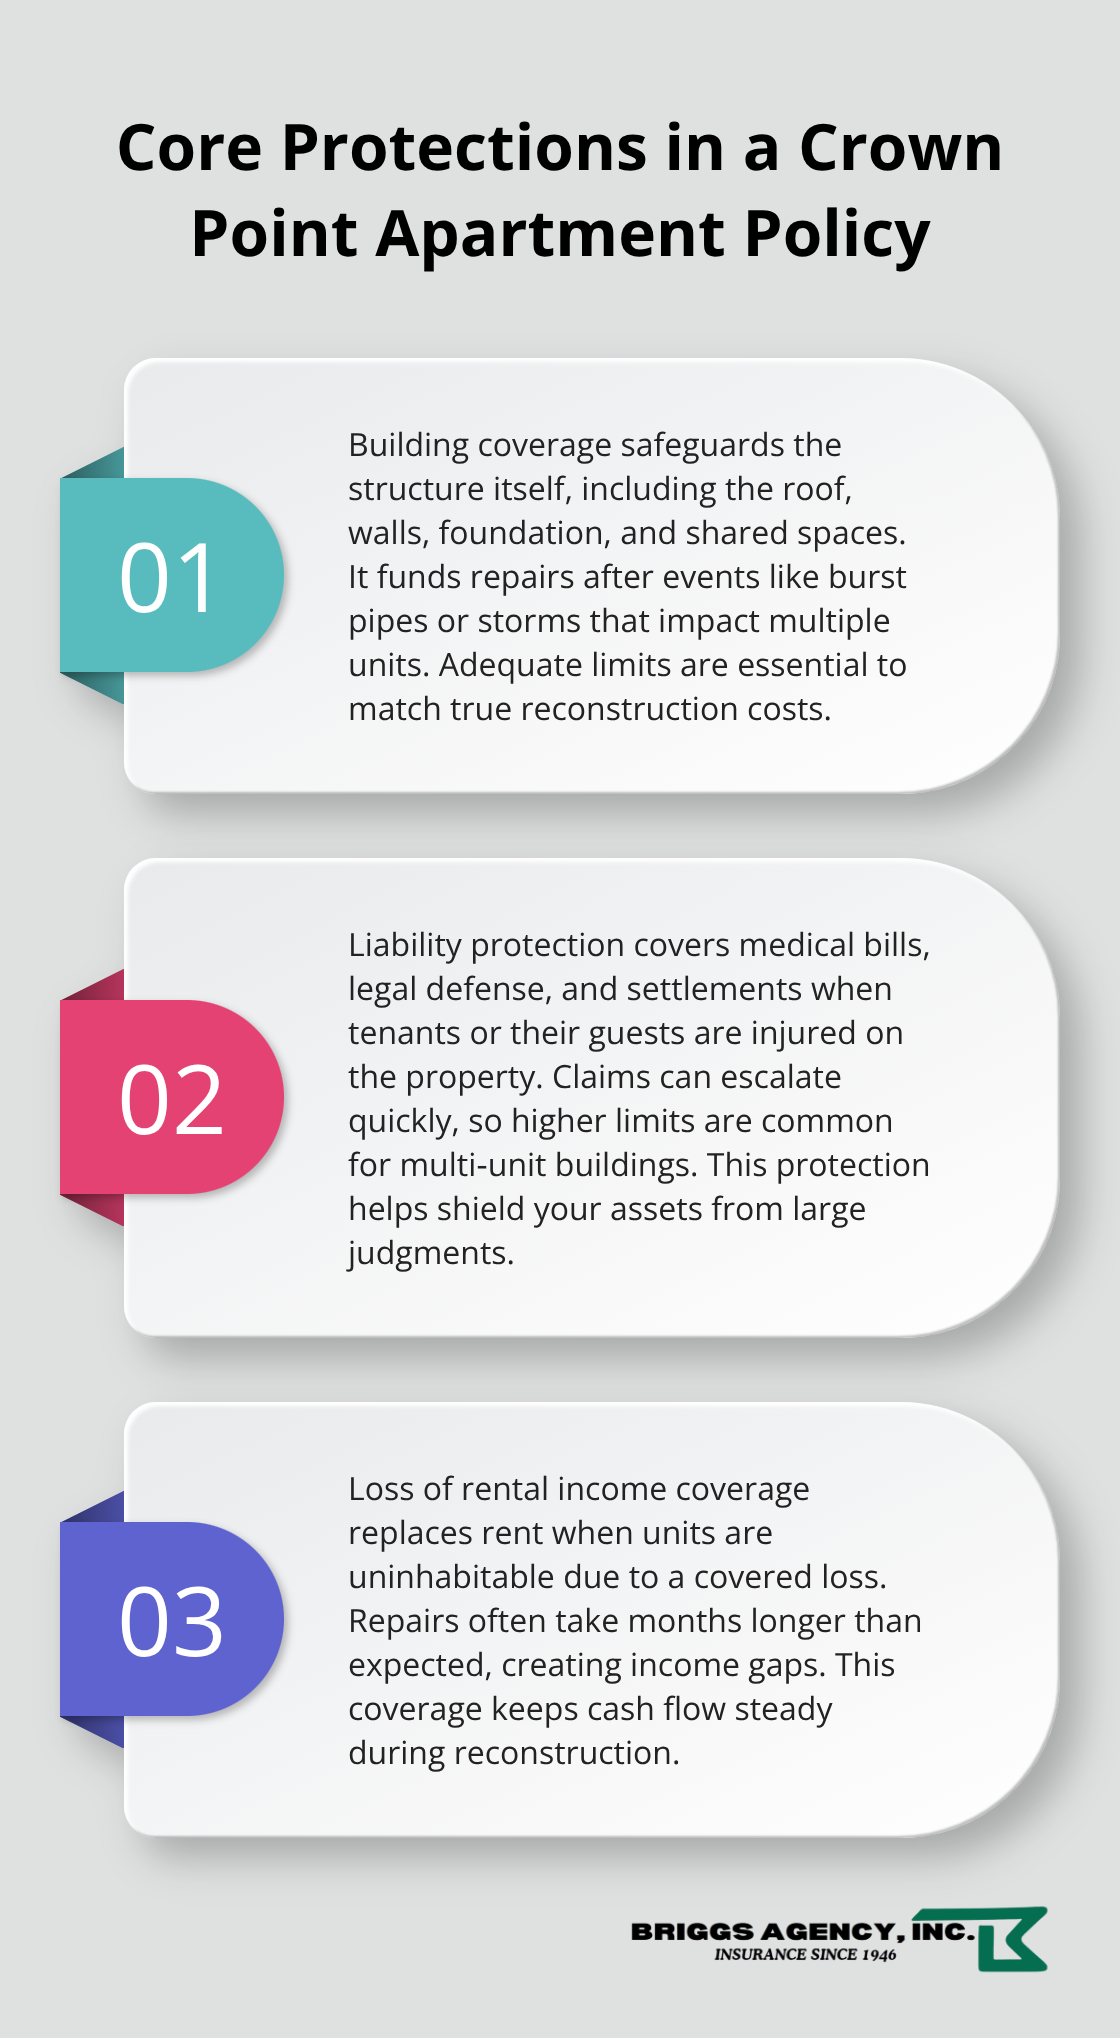
Apartment building insurance protects three distinct areas that homeowners policies ignore entirely. It covers structural damage to the building itself-the roof, walls, foundation, and common areas like hallways, stairwells, and the parking lot. When a pipe bursts in the basement and floods the laundry room, or a storm damages the roof affecting multiple units, your apartment policy pays for repairs. The coverage limits matter significantly here.

Three core protections in an apartment building insurance policy: building, liability, and loss of rental income. - Crown Point apartment policy

According to the National Association of Insurance Commissioners, the average apartment building replacement cost in Indiana involves reconstruction expenses after a loss. Most apartment owners underestimate their coverage needs, leaving themselves dangerously exposed.

Liability Protection When Tenants Get Injured

Liability coverage separates apartment policies from standard homeowners insurance. If a tenant slips on ice in the common stairwell and breaks their leg, they’ll likely sue the building owner. Your apartment policy covers medical expenses, legal fees, and settlements up to your policy limit. The Insurance Information Institute reports that premises liability claims average 15,000 to 25,000 dollars in medical costs alone, before legal representation. Indiana courts have awarded settlements exceeding 500,000 dollars in cases involving serious injuries in apartment common areas. Your policy should include at least 500,000 dollars in general liability coverage, though 1 million dollars is increasingly standard for multi-unit properties. This coverage also protects you if a tenant’s guest suffers injury on the property (which happens more frequently than most owners anticipate).

Income Protection When Units Sit Empty

Loss of rental income coverage reimburses you when a covered event makes units uninhabitable. A fire that damages three units and renders them unrentable for four months during repairs triggers this protection to replace the rent you would have collected. This matters tremendously because reconstruction timelines often exceed expectations. A study from the Insurance Journal found that apartment building repairs average six to nine months after major structural damage, creating significant income gaps for owners. If your building generates 8,000 dollars monthly in rent across twelve units, a six-month interruption costs 48,000 dollars in lost income. Most apartment owners carry this coverage with limits between 12 and 24 months of potential lost rent (depending on their risk tolerance and financial reserves).

Why Your Current Coverage Likely Falls Short

Standard homeowners policies cap coverage at 300,000 to 500,000 dollars-amounts that barely cover one unit in a modern apartment building. Multi-unit properties face exposure that single-family homeowners never encounter. The combination of higher replacement costs, expanded liability exposure, and income interruption risk means apartment owners need specialized protection. Your next step involves assessing whether your current policy actually matches your property’s real value and the income it generates.

Why Standard Homeowners Policies Fail Multi-Unit Properties

Standard homeowners policies were built for single-family homes, not apartment buildings. The coverage limits reflect that reality, and they’re dangerously inadequate for your situation. A typical homeowners policy caps dwelling coverage at 300,000 to 500,000 dollars, which sounds substantial until you calculate what it actually costs to rebuild an apartment building. Reconstruction costs for multi-unit residential properties average around $350 per square foot in Indiana. A twelve-unit building occupying 24,000 square feet would need 8.4 million dollars in replacement coverage. Your homeowners policy covers roughly one-tenth of that exposure. When a major fire or structural failure hits, you pay the difference from your own pocket.

Tenant Occupancy Creates Liability Gaps

Insurance companies exclude tenant-occupied units from standard homeowners policies for a specific reason: tenants create liability exposure that homeowners policies don’t address. If a tenant’s guest slips on common stairs or suffers injury in a shared hallway, the homeowners policy typically denies the claim outright. The policy language specifically excludes injuries that occur in areas where non-family members live or regularly access. This gap becomes catastrophic when you face a genuine liability lawsuit. Indiana courts have awarded judgments exceeding 750,000 dollars in premises liability cases involving apartment common areas. Your homeowners policy won’t cover a penny of that claim.

Common Areas Leave You Completely Exposed

Standard policies also fail to cover damage to common areas and shared spaces that directly affect your rental income. Hallways, stairwells, laundry facilities, parking lots, and roof structures supporting multiple units fall into a gray zone under homeowners coverage. If heavy snow collapses your parking structure and tenants can’t access units for three months, your homeowners policy won’t reimburse the lost rent. If water damage from a failed common roof affects five units simultaneously, standard coverage treats it as a single-unit loss rather than a building-wide event. Apartment building policies specifically address these shared spaces with separate coverage limits that match the actual replacement costs.

The Real Cost of Underinsurance

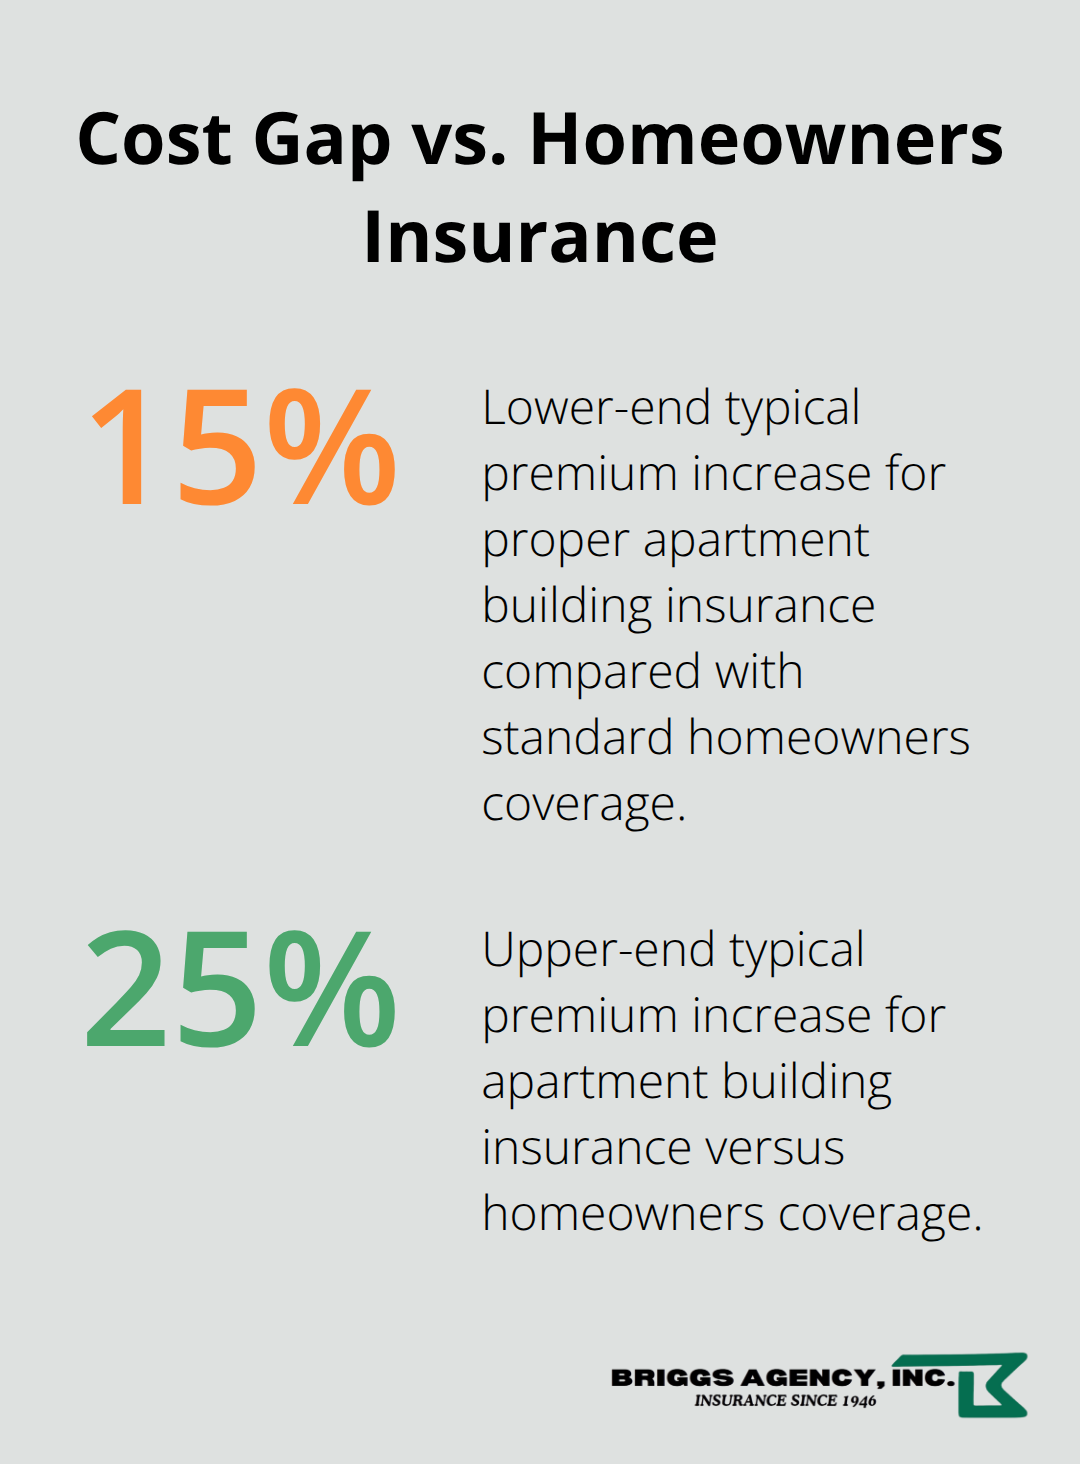
The cost difference between standard homeowners coverage and proper apartment building insurance typically runs 15 to 25 percent more annually, but that premium difference vanishes instantly when you face a claim that homeowners insurance denies. Your building’s income-producing nature demands protection designed for that reality. The question isn’t whether you can afford apartment building insurance-it’s whether you can afford what happens when standard homeowners coverage fails you.

Percentage comparison showing apartment building insurance typically costs 15% to 25% more than standard homeowners coverage. - Crown Point apartment policy

Understanding what apartment building policies actually cover (and what homeowners policies leave unprotected) helps you make the right choice for your Crown Point property.

How to Choose the Right Apartment Building Insurance in Crown Point

Calculate Your Actual Coverage Needs

Calculating your actual coverage needs starts with honest numbers about your property. Most apartment owners guess at their requirements rather than measuring them precisely, which is why so many end up underinsured. Start with your building’s replacement cost-not its market value, but what it would genuinely cost to rebuild it from scratch today. Take your total square footage and multiply it by the current reconstruction cost per square foot in your area (Indiana averages around $350 per square foot for multi-unit residential). A twelve-unit building spanning 24,000 square feet needs approximately $8.4 million in dwelling coverage.

Next, calculate your annual rental income across all units and multiply by the number of months your building would likely sit empty during major repairs. If your building generates $96,000 annually in rent, you face $48,000 to $72,000 in potential lost income that your policy should cover.

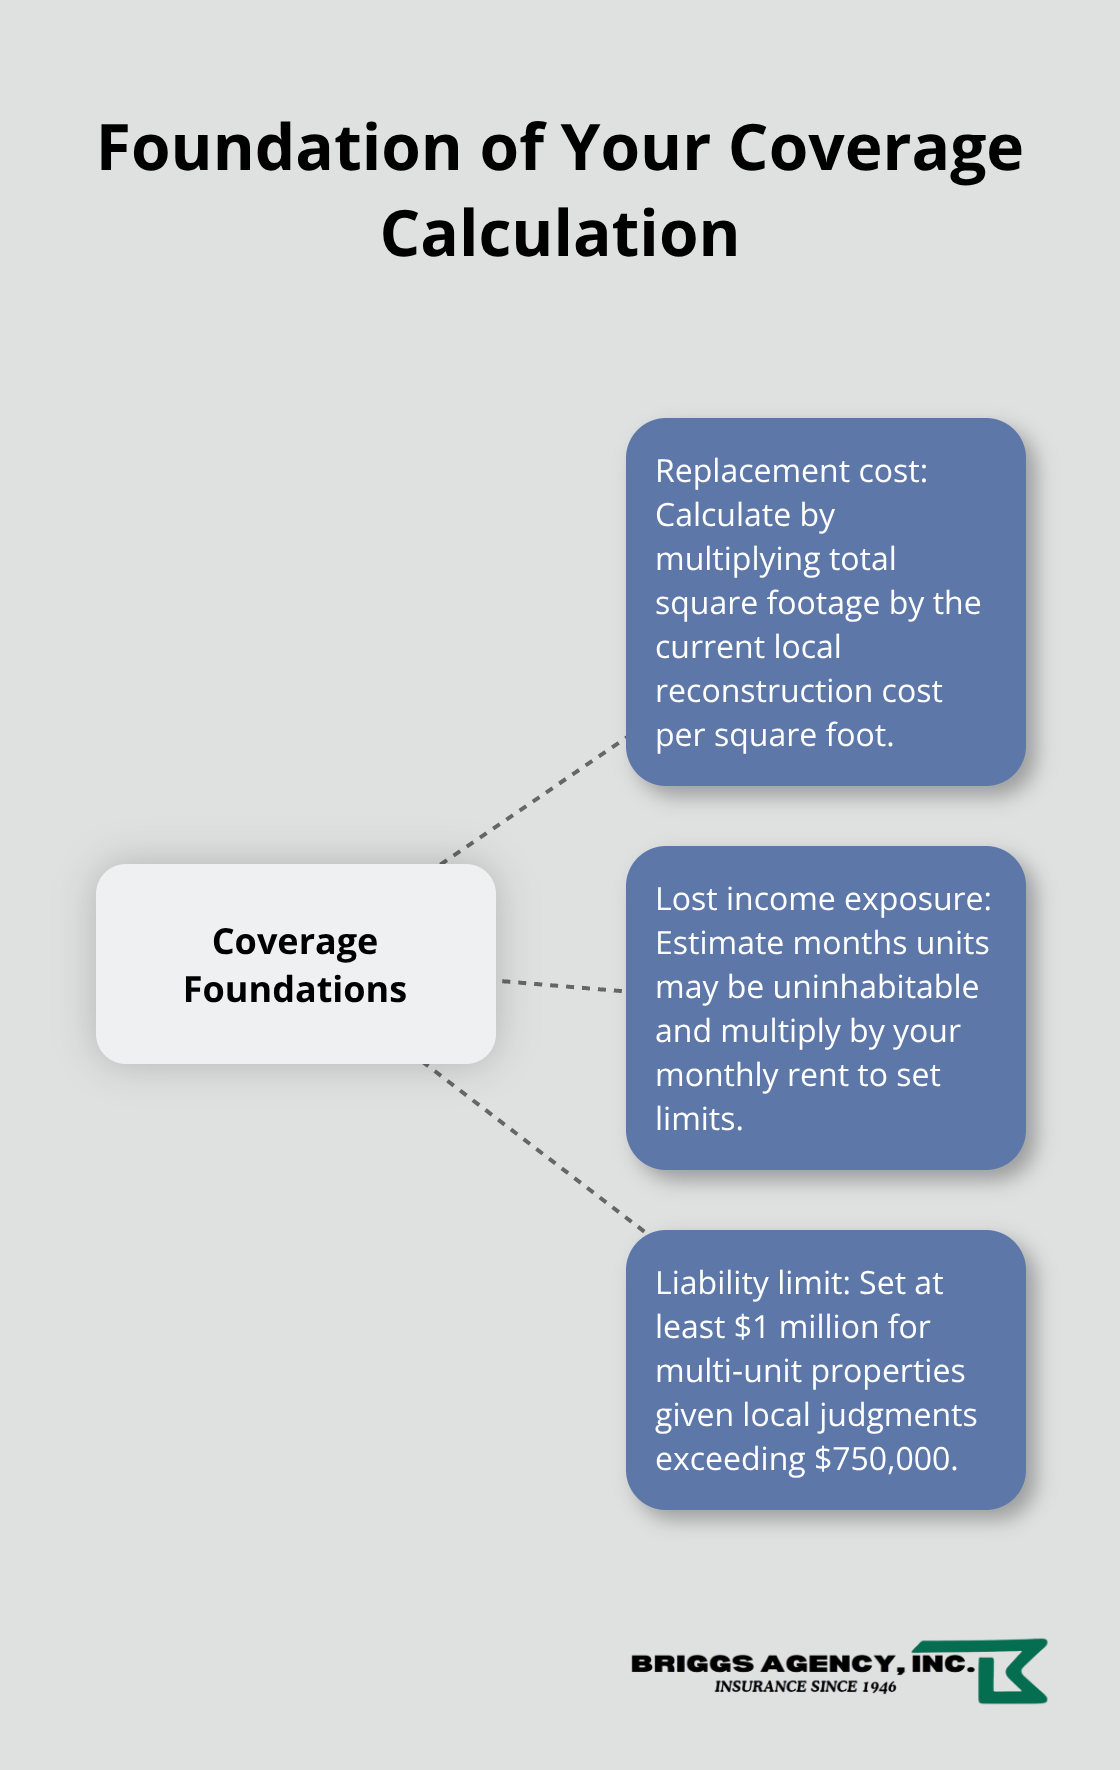
Your liability exposure depends on tenant volume and local court history. Indiana courts have awarded settlements exceeding $750,000 in apartment premises liability cases, which means your general liability limit should sit at minimum $1 million for any multi-unit property. These three numbers-replacement cost, lost income exposure, and liability limit-form the foundation of what you actually need to request from carriers.

Hub-and-spoke showing replacement cost, lost income exposure, and liability limit as the foundation of apartment coverage needs.

Request Quotes from Multiple Carriers

Comparing quotes requires discipline because insurance companies price policies differently based on building age, construction type, occupancy rates, and loss history. Request quotes from at least three carriers and ask each one the same detailed questions about what they exclude, what deductibles apply to different coverage types, and whether they offer discounts for safety features like fire suppression systems or security cameras. One carrier might charge $2,400 annually for your building while another quotes $3,200 for the same protection.

Don’t automatically choose the lowest price-instead, verify that each quote actually covers your replacement cost calculation and includes the liability limits you determined. A local agent who represents multiple carriers and understands Crown Point’s specific risks proves far more valuable than shopping online alone.

Work with a Local Agent Who Knows Your Market

An agent familiar with your neighborhood knows which carriers respond quickly to claims, whether they’ve denied coverage unfairly in the past, and which ones offer meaningful discounts for your specific property type. Your agent should also review your current policy line-by-line to identify gaps between what you’re paying for and what you actually need. We at Briggs Agency, Inc. represent multiple top-rated carriers, which allows our experienced local agents to compare options and match property owners throughout Crown Point with carriers that understand apartment building risks and price accordingly. An independent agent with access to several carriers can often find coverage options and pricing that online shopping cannot match.

Final Thoughts

Your Crown Point apartment policy protects your investment when standard homeowners insurance fails you completely. The coverage gaps we’ve outlined throughout this guide-replacement costs that exceed your policy limits, liability claims that drain your reserves, and income losses during reconstruction-demand specialized protection designed for multi-unit properties. Without proper apartment building insurance, you face financial devastation that no property owner can afford.

Choosing the right coverage requires more than comparing premiums online. You need an agent who understands Crown Point’s rental market, knows which carriers handle apartment claims fairly, and can match your specific property with appropriate limits and deductibles. That local expertise matters tremendously when you file a claim and need someone who advocates for you with the carrier.

We at Briggs Agency, Inc. have served Crown Point property owners since 1946, helping them navigate insurance decisions that protect their buildings and tenants. Our experienced local agents represent multiple top-rated carriers, which means we can compare options and find competitive pricing tailored to your property’s actual risks. Contact Briggs Agency, Inc. to discuss your apartment building insurance and ensure your investment receives the comprehensive protection it deserves.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.

Questions to Ask Before Buying Insurance

Buying insurance is about more than finding the lowest price. It’s about making sure you have the right protection when you need it most.

Before purchasing an insurance policy, it’s important to understand exactly what you’re getting. Coverage limits, claiming process, and many other things that can all make a major difference in how well a policy protects you. Asking the right questions before you buy can help you avoid unexpected gaps in coverage and give you more confidence in your decision. Whether you’re shopping for auto, home, business, or another type of insurance, taking the time to understand your options can help you choose coverage that fits your needs and budget.

Here are some really important questions you should be asking before you buy insurance:

1. What exactly is being covered?

Before purchasing a policy, make sure you understand exactly what types of losses, damages, or situations are covered. Insurance policies can vary significantly, even when they appear similar at first glance. Ask your agent to explain the main protections included in the policy and how they apply to your specific situation.

Depending on the type of policy, coverage may include things such as:

  • Damage to your home, vehicle, or business property
  • Liability if you are responsible for injuring someone or damaging their property
  • Theft or vandalism
  • Certain weather-related losses
  • Medical expenses after a covered accident
  • Temporary living expenses if your home becomes unlivable
  • Damage to business equipment or inventory
  • Certain legal defense costs

Not every policy includes the same protections, so it is important to review your specific coverage rather than assuming something is automatically included.

2. How much will it cost me?

The premium is an important part of choosing insurance, but it should not be the only factor you consider. Ask how much the policy will cost monthly or annually, what your deductible will be, and whether there are additional fees. You should also ask about available discounts, such as bundling multiple policies or qualifying for certain safety or claims-free discounts. A lower price may be appealing, but make sure you are not sacrificing important coverage just to save money.

3. What won’t be covered?

Every insurance policy has exclusions, which are situations or types of damage that the policy does not cover. Knowing these exclusions ahead of time can help you recognize potential gaps in your protection.

Depending on the policy, common exclusions may include:

  • Flood damage under a standard homeowners policy
  • Earthquake damage unless additional coverage is purchased
  • Normal wear and tear or lack of maintenance
  • Intentional damage
  • Certain high-value belongings without additional coverage
  • Business activities conducted from your home
  • Certain types of vehicle use, such as some commercial or rideshare activities
  • Losses that exceed the limits of your policy

Coverage and exclusions vary by policy and insurance carrier, so always ask your agent to explain what is specifically excluded. In some cases, additional coverage or endorsements may be available to help fill those gaps.

4. What is the limit on the coverage?

Insurance policies have coverage limits, which are the maximum amounts the insurance company will pay for a covered claim. Make sure those limits are high enough to properly protect your home, vehicle, business, belongings, or other assets. Choosing limits that are too low could leave you responsible for a significant portion of the costs after a major loss. Your insurance agent can help you determine what coverage limits make sense for your situation.

5. What is the claim process like?

Knowing how the claims process works before you ever need to file one can make a stressful situation easier to handle. Ask who you should contact after a loss, what information or documentation you will need, and what you can expect throughout the process. It is also helpful to know whether your insurance agent can assist you with questions during a claim. Having a clear understanding of the process can help you feel more prepared if something unexpected happens.

Conclusion

Buying insurance is an important decision, and asking the right questions can help you feel more confident about the coverage you choose. Understanding what is covered, what is excluded, how much the policy costs, what the coverage limits are, and how the claims process works can help prevent surprises later. Taking the time to review your options and talk with a knowledgeable insurance agent can make it easier to find a policy that provides the protection you need at a price that fits your budget. It can also help you spot potential coverage gaps before they become a problem. The more you understand your policy upfront, the better prepared you’ll be when you actually need to use it.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes


What Every Subcontractor Should Know About Insurance

Introduction

Imagine finishing a major construction project, getting ready to collect your payment, and then discovering that one accident could cost your business thousands—or even put you out of business. For subcontractors, insurance is more than just another business expense; it is a critical part of protecting your company, employees, equipment, and financial future. Every subcontractor should understand what their insurance covers, what their contracts require, and what risks they may be responsible for. Knowing the basics of insurance can help subcontractors avoid costly surprises and make smarter decisions before stepping onto a jobsite.

Body

1. Understanding General Liability Insurance

General liability insurance is one of the most important types of coverage for subcontractors. It generally protects a business when claims involve third-party bodily injury, property damage, or certain other liabilities connected to the company’s operations.

For example, if a subcontractor accidentally damages a customer’s property or someone is injured because of the subcontractor’s work, general liability insurance may help cover eligible claims and legal expenses. Many general contractors also require subcontractors to carry specific liability limits before they are allowed to begin work.

However, subcontractors should not assume that every type of accident or claim is automatically covered. Policies contain exclusions and limitations, so subcontractors should understand their specific policy rather than relying only on the phrase “general liability.”

2. Workers’ Compensation Insurance

Workers’ compensation is another important consideration for subcontractors who have employees. It is designed to provide benefits for employees who suffer work-related injuries or illnesses, subject to applicable laws and policy terms.

Subcontractors should understand their state’s requirements and make sure their employee classifications and payroll information are accurate. Failing to maintain appropriate workers’ compensation coverage can lead to serious financial and legal consequences.

3. Additional Insurance Coverage

General liability and workers’ compensation may not be enough for every subcontractor. Depending on the type of work being performed, additional coverage may be necessary.

Commercial auto insurance can be important when company vehicles are used for business purposes. Tools and equipment may require separate coverage because a general liability policy typically is not designed to protect a subcontractor’s own property. Subcontractors involved in design or professional services may also need professional liability insurance. Depending on the trade and project, umbrella, excess liability, or pollution coverage may also be appropriate.

The right combination of insurance depends on the subcontractor’s trade, employees, equipment, contracts, and the risks associated with the work.

4. Understanding the Subcontract

Insurance requirements are often written directly into the subcontractor’s agreement with the general contractor. Before signing, subcontractors should carefully review these requirements and make sure their insurance actually satisfies them.

Contracts may require specific coverage limits, additional insured status, primary and noncontributory coverage, or a waiver of subrogation. These requirements can be easy to overlook, especially when a subcontractor is focused on pricing and scheduling the project.

A certificate of insurance can demonstrate that certain insurance policies are in place, but the certificate itself generally does not change the terms of the underlying insurance policy. The actual policy and applicable endorsements are what determine coverage.

5. Don’t Wait Until Something Goes Wrong

One of the biggest mistakes a subcontractor can make is waiting until after an accident or dispute to find out what their insurance covers. Before beginning a project, subcontractors should review the contract, identify their insurance obligations, and discuss any questions with a qualified insurance professional.

They should also notify their insurer when there are significant changes to their business, such as taking on new types of work, purchasing vehicles or equipment, hiring employees, or accepting substantially larger projects. Keeping insurance information current can help reduce the risk of discovering a coverage problem when it is too late.

Conclusion

Insurance is not simply paperwork that subcontractors need to satisfy a general contractor. It is an important tool for protecting a business from the financial consequences of accidents, injuries, property damage, and other unexpected events. By understanding general liability, workers’ compensation, additional coverage options, and the insurance requirements in their contracts, subcontractors can better protect themselves and their businesses. The most important lesson is simple: don’t wait for a problem to find out what your insurance covers. Know your risks, understand your contract, and make sure your coverage matches the work you do.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski


Rental Property Insurance: Safeguard Your Investment And Tenants

Owning a rental property comes with real financial exposure. Tenant disputes, weather damage, and liability claims can quickly drain your profits or create legal headaches.

At Briggs Agency, Inc., we help landlords understand how rental property insurance protects both their investment and their tenants. This guide walks you through the coverage types you need, the risks you face, and how to choose the right policy for your situation.

What Coverage Your Rental Property Actually Needs

How Rental Policies Differ from Homeowners Insurance

Rental property insurance differs fundamentally from homeowners insurance because the risk profile is completely different. A homeowners policy protects your primary residence and assumes you live there; a rental policy accounts for tenant occupancy, business operations, and landlord liability. Standard homeowners policies explicitly exclude rental income coverage and tenant-related liability, which means you face exposure if a tenant gets injured on the property or your building becomes uninhabitable and you lose rental income. This distinction matters because the financial consequences of being underinsured are substantial. A rental property generates income that homeowners insurance will not cover, so even a two-month loss of rent due to fire or major damage represents significant direct losses.

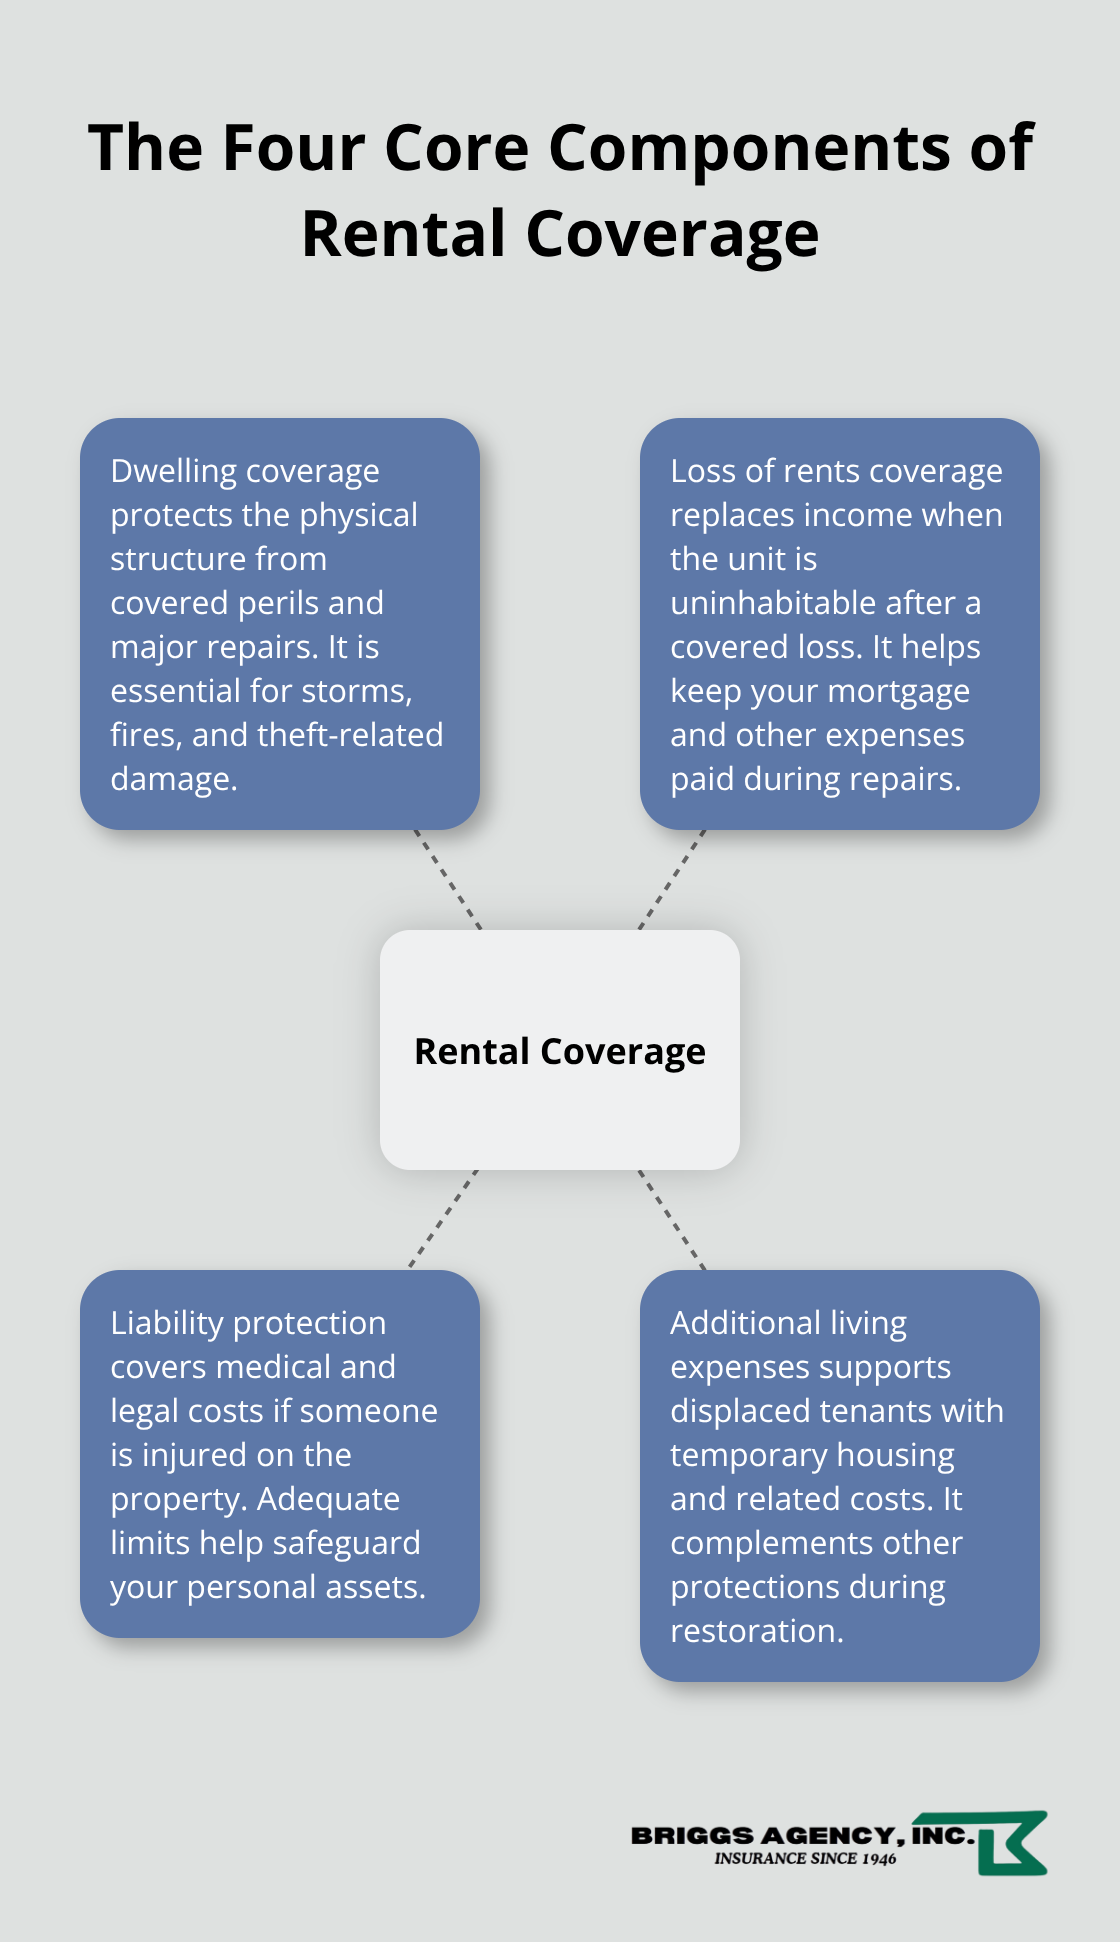
The Four Core Components of Rental Coverage

Rental property policies typically include four core components: dwelling coverage, which protects the physical structure; loss of rents coverage, which replaces your income if the property becomes uninhabitable; liability protection, which covers medical expenses and legal costs if someone is injured at your property; and additional living expenses coverage for tenants temporarily displaced. Each component addresses a specific vulnerability that standard homeowners policies ignore. The liability piece matters most because tenant injuries or property damage claims can escalate quickly. Premises liability claims can be substantial, and if a tenant’s injury leads to a lawsuit, your personal assets become vulnerable without proper landlord liability limits.

Hub-and-spoke diagram showing the core components of rental property insurance for U.S. landlords.

Setting Appropriate Liability Limits

Most carriers recommend minimum liability coverage of $300,000 to $500,000 for single-family rentals and higher amounts for multi-unit properties. Your specific coverage needs depend on your property type, location, tenant screening practices, and whether you self-manage or hire a property manager. Local agents who understand Indiana’s rental market and your specific situation help identify gaps that generic online quotes miss. The right policy protects both your investment and your tenants, but only if you select limits that match your actual exposure.

Common Risks Landlords Face and How Insurance Protects Against Them

Property Damage from Weather, Fire, and Theft

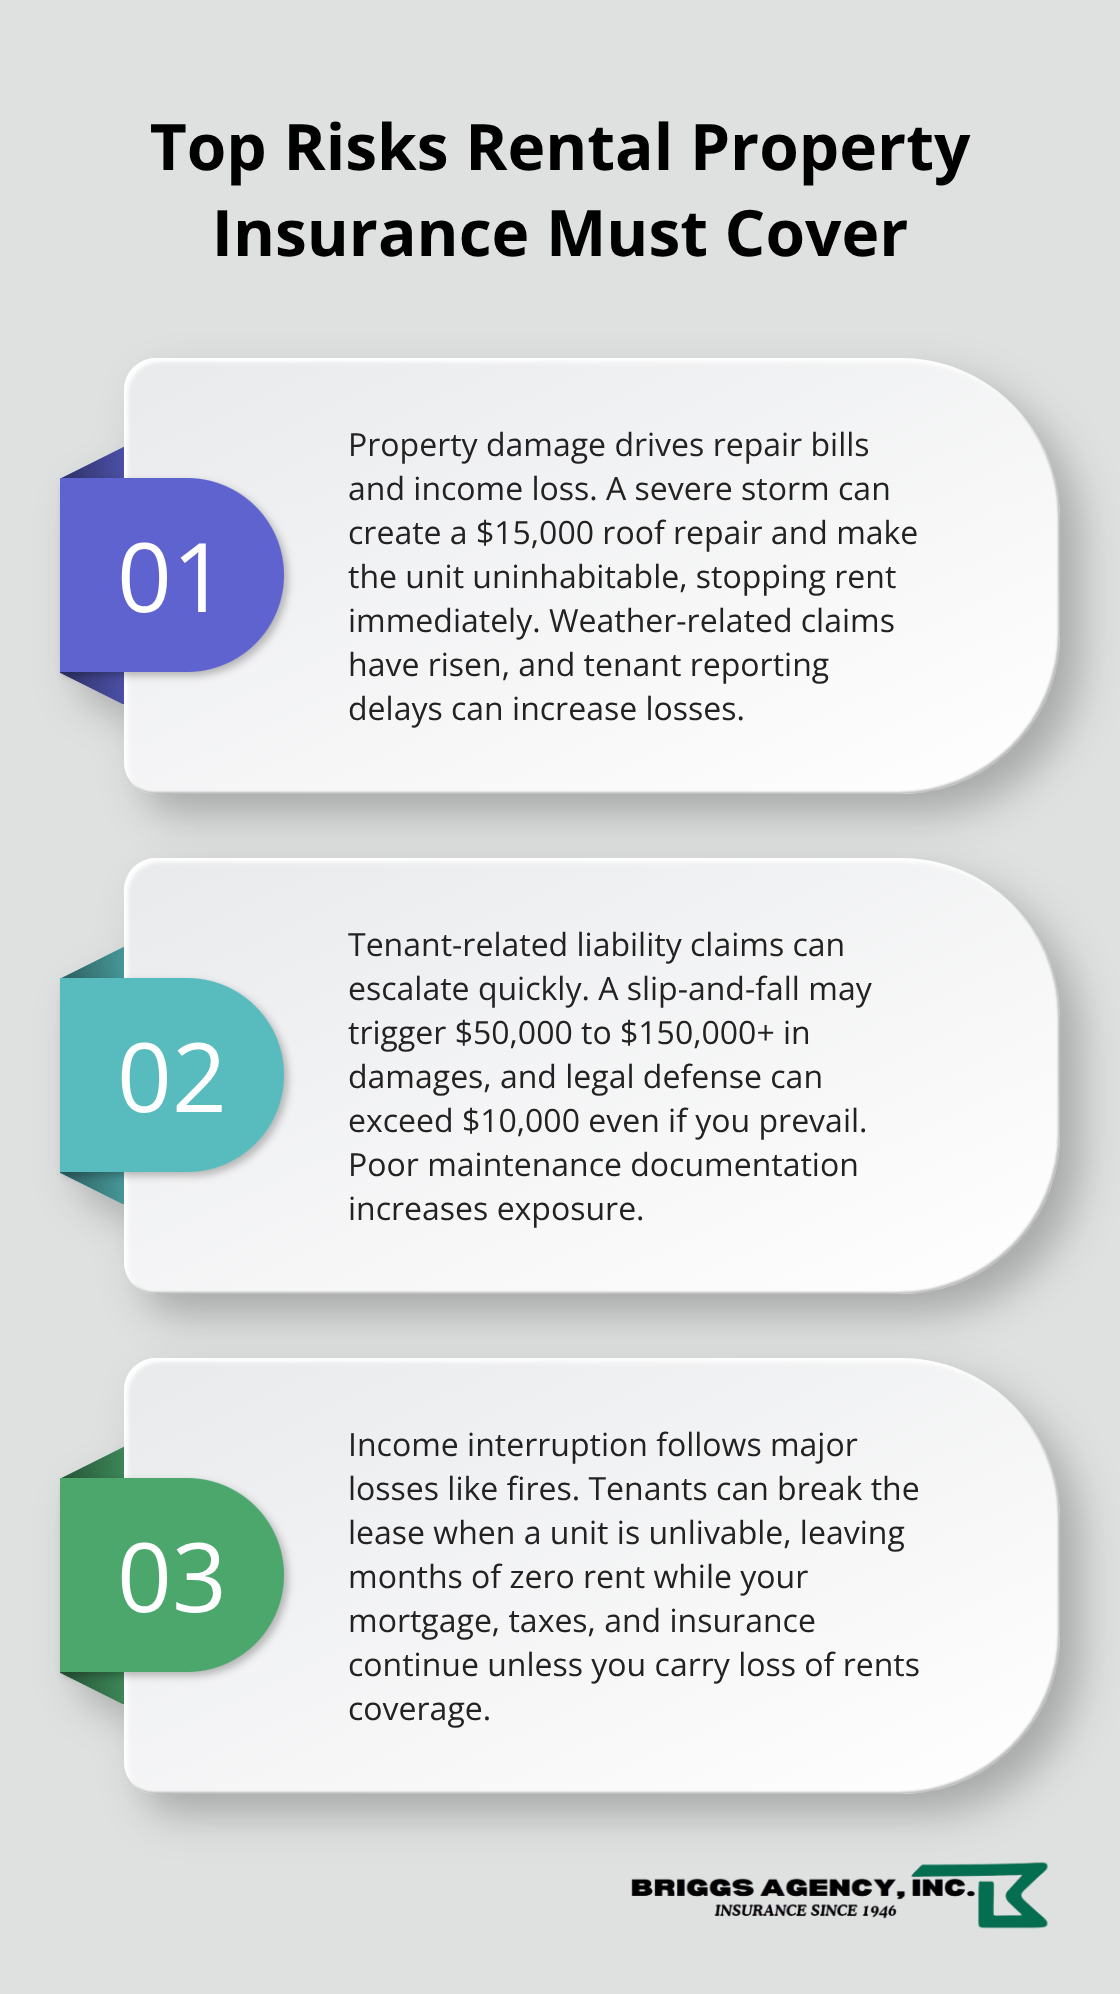
Weather damage, fires, and theft represent the most common threats to your rental property’s physical structure, but the financial impact extends beyond repair costs. A severe storm that damages your roof doesn’t just create a $15,000 repair bill-it also makes the unit uninhabitable, which stops your rental income immediately. Weather-related property damage claims have increased significantly, and rental properties face higher exposure because tenants often delay reporting damage or lack incentive to prevent loss.

Theft of appliances, HVAC systems, and copper wiring happens regularly in vacant units, with typical losses ranging from $3,000 to $10,000 per incident. Dwelling coverage protects the structure itself, but you need loss of rents coverage to replace the income you lose while the property sits uninhabitable during repairs. Without loss of rents protection, a three-month reconstruction period after a fire means three months of zero income while your mortgage, taxes, and insurance payments continue unchanged.

Tenant-Related Liability Claims

Tenant-related liability claims create a different financial exposure that many landlords underestimate. If a tenant slips on ice in your parking lot and fractures their leg, they can sue you for medical expenses, lost wages, and pain and suffering-with claims often reaching $50,000 to $150,000 or higher depending on injury severity and state law. Premises liability cases show that landlords face significant risk when they lack proper maintenance documentation, and even when you win, legal defense costs alone can exceed $10,000.

A tenant injured due to a maintenance issue you knew about but delayed fixing strengthens their case substantially. Your liability coverage pays their medical bills and legal judgments, protecting your personal assets from seizure.

Loss of Rental Income and Uninhabitable Conditions

Loss of rental income due to uninhabitable conditions hits hardest when you face a major loss. If a fire makes your property unlivable, your tenant has the legal right to break their lease and move out immediately, and you cannot collect rent until repairs finish and the unit passes inspection. Without loss of rents coverage, this gap represents pure financial loss that comes directly from your pocket.

These three risk categories-structural damage, tenant injuries, and income interruption-form the foundation of what your rental policy must address. The right coverage limits and policy structure determine whether a single incident depletes your savings or remains manageable.

Three-part overview of primary landlord risks with examples and costs.

How to Choose the Right Rental Property Insurance Coverage

Assess Your Property and Tenant Profile

Start by documenting what you actually own and what you face. Walk through your rental property and list the physical structure value, any detached buildings, appliances you provide, and personal property you keep there. Then assess your tenant situation honestly: are you managing a single-family home with one long-term tenant or a multi-unit building with frequent turnover?

Properties with higher turnover and younger tenants statistically experience more liability claims, while older buildings face greater weather-related damage risk. Your property location matters significantly-Indiana properties in flood-prone areas require flood insurance if financed with government-backed mortgages, and theft claims concentrate in specific neighborhoods. Once you understand your actual exposure, you can avoid overbuying coverage you don’t need while ensuring you’re not dangerously underinsured.

Compare Policies Beyond the Premium

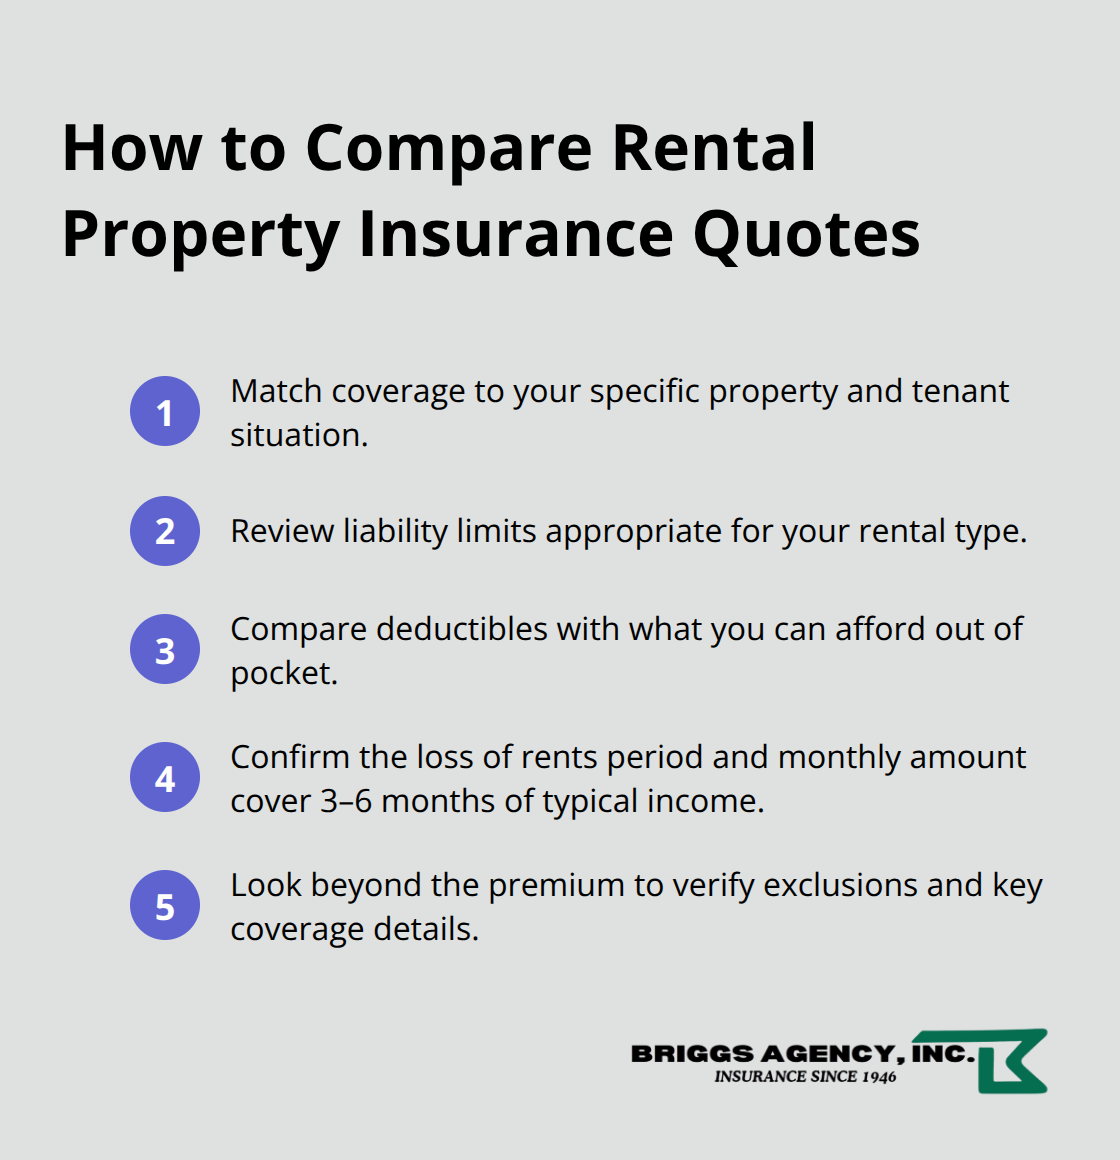
Many landlords make the mistake of choosing the cheapest quote without matching coverage to their specific situation, then discover gaps when a claim happens. Comparing policies requires looking beyond the premium number. Two carriers might quote the same price but offer different liability limits, deductibles, and loss of rents periods.

A $1,000 deductible saves money on premiums but costs significantly more when you file a claim, so calculate whether you can actually afford that out-of-pocket amount if damage occurs. Loss of rents coverage should cover at least three to six months of your typical rental income-if you charge $1,500 monthly rent, you need $4,500 to $9,000 in loss of rents protection.

Compact checklist to evaluate rental property insurance quotes beyond the premium.

Request Multiple Quotes and Ask Detailed Questions

Request quotes from multiple carriers and ask each agent to explain exactly what each policy covers and excludes; generic quote comparisons miss critical differences. Local agents who know Indiana rental markets and your neighborhood help you avoid underinsurance mistakes that cost far more than premium savings ever would. An independent agency that represents multiple top-rated carriers can compare options across different companies and tailor coverage to your specific property and tenant profile, delivering competitive pricing and the right protection for your situation.

Final Thoughts

Rental property insurance protects your investment from the financial damage that tenant disputes, weather events, and liability claims create. The coverage types we’ve covered-dwelling protection, loss of rents, and liability limits-work together to keep your rental income stable and your personal assets safe from lawsuits. Choosing the right policy means matching your coverage to your actual property and tenant situation, not just picking the lowest premium.

Your rental property insurance needs change as your portfolio grows, your property ages, or your tenant profile shifts. A policy that worked perfectly five years ago may leave you underinsured today. Review your coverage annually and after major property changes like renovations, tenant transitions, or neighborhood shifts, and compare quotes every few years to find better pricing or improved protection options.

Document your property value, list your typical monthly rental income, and think through the tenant-related risks specific to your situation (including local weather patterns and neighborhood crime rates). Then contact a local agent who represents multiple carriers and can compare options across different companies. We at Briggs Agency, Inc. have served Indiana landlords, and our experienced agents understand the rental market in Crown Point and throughout the region-reach out to discuss your rental property insurance needs and get quotes that match your actual exposure.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
General Liability vs. Professional Liability

Having a business comes with its risks. A customer could slip and fall at your location, an employee could accidentally damage a client’s property, or a customer could claim that your professional advice caused them financial harm. While business owners may take every precaution possible, accidents are still possible. Two coverages that are often confused are general liability insurance and professional liability insurance. Both can help protect a business from costly liability claims, but they are designed to cover very different types of risks.


What Is General Liability Insurance?

General liability insurance is one of the most common types of coverage for businesses. Its purpose is to protect a company against claims involving bodily injury, property damage, and certain personal or advertising injuries that come from business operations. General liability insurance has protection for:

  • Bodily injury
  • Property damage
  • Personal injury
  • Medical payments


What Is Professional Liability Insurance?

Professional liability insurance protects businesses claims that come from the professional services or expertise they provide. It is sometimes called Errors and Omissions insurance. Professional liability insurance may help when a client alleges that your business made an error, failed to perform a professional service properly, or provided advice that resulted in a financial loss.

Generally, professional liability claims include:

  • Professional mistakes or errors
  • Incorrect advice
  • Missing deadlines
  • Negligence


Can a Business Need Both?

Many businesses face both general and professional liability risks. Having only one type of coverage could leave important exposures uninsured. For example, if a client visits the office and slips, the claim would be addressed by general liability insurance. If another client later claims that the consultant provided incorrect advice that caused the company financial loss, that will fall under professional liability insurance. Businesses should investigate both their physical operations and the professional services when trying to figure out which coverage they need.


General liability and professional liability insurance both play important roles in protecting businesses. General liability insurance protects against third-party bodily injury and property damage, while professional liability insurance focuses on claims involving mistakes or failures in professional services. Every business has different risks. Reviewing your insurance regularly can help identify potential gaps and make sure your coverage continues to match the way your business operates.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

How To Save Money On Auto Insurance Without Sacrificing Coverage

Introduction

Imagine opening your monthly bills and realizing that your car insurance costs almost as much as your car payment. For many drivers, auto insurance is one of the largest recurring expenses, but paying less does not have to mean giving up important protection. With the right approach, drivers can lower their insurance costs while still maintaining coverage that protects them financially after an accident. By comparing insurance providers, taking advantage of discounts, adjusting deductibles, and carefully reviewing coverage, drivers can find ways to save money without putting themselves at unnecessary risk.

Body

Compare Different Insurance Companies

One of the easiest ways to save money on auto insurance is to compare quotes from different insurance companies. Insurance providers use different methods to determine how much a driver will pay, so two companies may offer very different prices for similar coverage. Drivers should request several quotes and compare them using the same liability limits, deductibles, and additional coverage. Choosing the cheapest policy is not always the best option, so it is important to make sure the lower price does not come with significantly less protection.

Take Advantage of Available Discounts

Another effective way to reduce insurance costs is to ask about discounts. Many insurance companies offer discounts for safe driving, having multiple vehicles, bundling auto insurance with renters or homeowners insurance, completing defensive-driving courses, or driving fewer miles. Students and drivers with good driving records may also qualify for certain discounts. Since discounts vary between insurance companies, drivers should ask their insurer which ones they qualify for and compare those savings with other providers.

Adjust Your Deductible

Drivers can also reduce their premiums by increasing their insurance deductible. A deductible is the amount a driver must pay out of pocket before insurance covers a qualifying claim. For example, choosing a $1,000 deductible instead of a $500 deductible may lower the monthly or annual premium. However, drivers should only choose a higher deductible if they can afford to pay it after an accident. Saving money on the premium is not helpful if a driver cannot afford the deductible when they need to file a claim.

Avoid Reducing Important Coverage

While reducing coverage may lower an insurance bill, it can create serious financial problems after an accident. Liability insurance is especially important because it helps protect drivers from the costs of injuries or property damage they cause to other people. Drivers should be cautious about lowering their liability limits simply to save money. Instead, they should look for savings through discounts, comparison shopping, and deductible adjustments before removing important protection.

Review Your Policy Regularly

Insurance needs can change over time, so drivers should review their policies regularly. Changes such as driving fewer miles, paying off a vehicle, adding or removing a driver, or purchasing a different car can affect insurance costs. Reviewing a policy each year gives drivers an opportunity to identify unnecessary coverage, correct outdated information, and look for new discounts. Taking a few minutes to review a policy can potentially save money while ensuring that the coverage still matches the driver’s needs.

Conclusion

Saving money on auto insurance does not require drivers to sacrifice the protection they need. By comparing insurance companies, taking advantage of discounts, choosing an affordable deductible, maintaining important liability coverage, and reviewing their policies regularly, drivers can reduce their insurance expenses while remaining financially protected. The goal should not simply be to find the cheapest insurance policy, but to find the best value. With careful research and smart decisions, drivers can keep their coverage strong while putting more money back in their pockets.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski

What is Gap Insurance?

Gap insurance stands for Guaranteed Asset Protection insurance. Gap is an optional type of auto insurance that protects drivers who decide to finance or lease a vehicle. This type of insurance helps cover the difference between the amount a vehicle is worth at the time of a total loss and the amount of that is still owed on the loan or lease.


How Gap Insurance Works

When a driver buys a new vehicle, its value decreases overtime due to depreciation. In case of an accident or a stolen vehicle, your regular auto insurance generally pays the vehicle’s current market value. Gap insurance, however, can cover the amount you originally paid. For example, if a car is worth $20,000 but you still owe $24,000 in loans, your regular insurance can pay the approximate $20,000. Having the additional Gap insurance can help cover the remaining $4,000, subject to the policy’s limits and terms.


Who Can Benefit from Gap Insurance

Gap insurance can be helpful for people who:

  • Finance a vehicle for a long period of time.
  • Make a small down payment on a vehicle.
  • Purchase a vehicle that has a quick depreciation.
  • Have a loan balance that is higher than the vehicle’s current value.
  • Lease a vehicle.


What Gap Insurance Usually Covers

Generally, Gap insurance covers the difference between the vehicle’s insurance settlement and the remaining loan balance after a covered loss. However, the coverage varies depending on your insurer. Gap insurance may not cover late fees, overdue payments, extended warranties, or some additional charges.


Overall, Gap insurance can be helpful for those who lease or finance a vehicle. It provides protection against the effects of vehicle depreciation. If something happens to a vehicle while you owe more on it than its current value, Gap insurance can help pay the difference.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

Understanding Comprehensive vs. Collision Coverage

Understanding the difference between comprehensive and collision coverage is an important part of making informed decisions about your auto insurance.

Although both coverages can help pay for damage to your vehicle, they apply in different situations. Collision coverage generally helps with damage caused by an accident involving another vehicle or object, while comprehensive coverage typically applies to non-collision events such as theft, vandalism, severe weather, falling objects, and animal-related damage. Knowing how each type of coverage works can help you better understand your policy and choose protection that fits your needs.

Collision Coverage

Collision coverage helps pay for damage to your vehicle if it is involved in an accident with another vehicle or object, regardless of who is at fault. This can include accidents involving another car, a guardrail, fence, tree, light pole, or other stationary object. It may also apply in certain single-vehicle accidents, such as if your vehicle rolls over or you lose control and hit something.

This coverage is especially important because liability insurance generally does not pay for damage to your own vehicle when you are responsible for an accident. With collision coverage, your policy may help cover the cost of repairing or replacing your vehicle after a covered accident, subject to your deductible and the terms of your policy.

For example, if you accidentally back into a pole and damage your bumper, collision coverage may help pay for the repairs after your deductible is applied. If the damage is severe and your vehicle is considered a total loss, collision coverage may help pay the vehicle’s actual cash value, depending on your policy.

While collision coverage is not typically required by state law, lenders and leasing companies may require it if your vehicle is financed or leased. Even when it is optional, it can provide valuable financial protection by helping reduce the out-of-pocket costs that can come with an unexpected accident.

Comprehensive Coverage

Comprehensive coverage helps pay for damage to your vehicle caused by events that are generally unrelated to a collision. This can include theft, vandalism, fire, hail, windstorms, flooding, falling objects, broken glass, and damage caused by animals.

For example, if a tree branch falls on your parked vehicle during a storm or your car is damaged by hail, comprehensive coverage may help pay for repairs after your deductible is applied. It may also help if your vehicle is stolen or damaged during an attempted theft.

Unlike collision coverage, comprehensive coverage is designed to protect against many unexpected events that are outside of your control. This makes it especially valuable for drivers who want added protection from weather-related damage, theft, and other non-collision losses.

Comprehensive coverage is not usually required by state law, but lenders and leasing companies may require it if your vehicle is financed or leased. Even when it is optional, it can provide added peace of mind by helping reduce the financial impact of damage that could otherwise lead to costly repairs or replacement.

What They Both Don’t Cover

Comprehensive and collision coverage protect your vehicle, but they do not cover every expense associated with an accident.

Depending on the situation, separate coverage may be needed for:

  • Injuries you cause to another person
  • Damage you cause to another person’s property
  • Your own medical expenses
  • Injuries caused by an uninsured or underinsured driver
  • Rental vehicles while your car is being repaired
  • Roadside assistance
  • Normal wear and tear or mechanical breakdowns

That is why it is important to look at your auto policy as a whole instead of focusing on just one type of coverage.

Conclusion

Understanding the difference between comprehensive and collision coverage can make it easier to choose the right protection for your vehicle. Collision coverage is designed to help with damage caused by accidents involving another vehicle or object, while comprehensive coverage helps protect against non-collision events such as theft, vandalism, severe weather, and animal-related damage.

Having the right combination of coverage can help reduce unexpected out-of-pocket costs and give you greater confidence on the road. Because every driver, vehicle, and policy is different, it is important to review your coverage regularly and make sure it still fits your needs.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes