What to Do If Someone Hits Your Parked Car?

It can be frustrating to see that your car has been hit in the parking lot after just treating yourself to a shopping spree. In many cases, it doesn’t matter if the person who hit you flees the scene or stays. In both cases, knowing what steps to take can make the insurance claim process much faster. There are several steps you should consider determining which insurance policy is the right fit for you. Here’s what you should understand when someone hits your parked vehicle.


Get Information from the Driver and Gather Evidence

If the person who hit your car is still at the scene, it is important to gather the following information:

  • Full name and contact information
  • Driver’s license information
  • License plate number
  • Insurance company
  • Policy Information
  • Vehicle make, model, and color

It is also important to focus on documenting the scene and gathering any evidence that can be found instead of arguing about who is at fault.

Contacting Your Insurance Company and the Company of the Other Driver

If needed, a police report can be made. One possible way to deal with the consequence is to contact the driver’s insurance company. Their property damage liability insurance may cover for the damage on your car.

You can also contact your insurance company to file a claim. If your insurance policy includes collision coverage, it can usually take care of any repairs on your vehicle, whether or not your car was parked or not.

Getting an Estimate Before Making Repairs

Unless your vehicle needs immediate repairs to remain safe, avoid starting repairs before the insurance has time to document the damage. This is crucial because the insurance company may cover for any damages based on your coverage.


Finding out that someone hit your car can be frustrating. However, knowing what steps to take next can help you get through the problem without frustration. Reviewing your insurance policy can help you know exactly how to respond in such situations.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

What To Do Immediately After Storm Damage.

A storm can be over in minutes, but the damage it leaves behind can take weeks or even months to fix. Storms can cause serious damage to homes, cars, and personal belongings. After a storm, it is important to stay calm and take the proper steps to protect yourself and your property. Knowing how to work with your insurance company can make the recovery process easier and help you receive the coverage you deserve.

Stay Safe First

After a storm, your first priority should always be safety. Stay away from downed power lines, broken glass, unstable structures, and areas with flooding. If your home is unsafe, leave the property and wait until it has been inspected. Do not put yourself in danger just to check for damage.


Document the Damage

Once it is safe, take pictures and videos of everything that was damaged. Photograph your roof, windows, walls, floors, furniture, appliances, vehicles, and other belongings. Try to take pictures before cleaning up or making major repairs because your insurance company may need to see the damage.

You should also make a list of damaged or destroyed items. Save receipts for anything you purchase because of the storm, including temporary repairs or emergency supplies.


Contact Your Insurance Company

After documenting the damage, contact your insurance company as soon as possible to report the claim. Give them as much information as you can and ask for your claim number and the contact information for your insurance adjuster.

Your insurance policy will determine what types of storm damage are covered. It is important to understand your deductible and any limits or exclusions in your policy.


Prevent More Damage

While waiting for your insurance company, take reasonable steps to prevent additional damage. For example, you may need to cover a broken window or place a temporary tarp over part of a damaged roof. Keep receipts for these emergency repairs because they may be important for your claim.

However, avoid making major permanent repairs until your insurance company has had an opportunity to inspect the damage, unless the repairs are necessary for safety.


Conclusion

Storm damage can be overwhelming, but taking the right steps can make the recovery process easier. The most important things to remember are to stay safe, document the damage, contact your insurance company, keep your receipts and records, and carefully choose contractors. By staying informed and organized, homeowners can protect themselves and work toward getting their property back to normal.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski


What Happens After a Car Accident?

Imagine you are leaving work and are ready to relax in the comfort of your own home, when suddenly, you have to deal with the consequences of another bad driver on the road. A car accident can add a lot of unwanted stress and confusion, especially when you are not sure what steps to take next. Understanding the insurance process during a car accident is crucial, even if you were not the one at fault. The three main steps every driver should take in such situations are to report the incident, file for an insurance claim to determine who is responsible, and to take care of any repairs.

Reporting the Incident

After making sure no one is hurt, the first and most important step is reporting the incident to the police and your insurance company. Drivers should exchange information such as phone numbers, license numbers, insurance information, and driver’s license information. Taking pictures on the incident and collecting information from witnesses are also important steps to take which can provide additional evidence. A police report can also be helpful to provide an official record as to what exactly happened. Providing accurate and honest information can help the insurance company understand what happened and how to help.

Filing an Insurance Claims

After the accident is reported, an insurance claim may be opened. An adjuster, assigned by the insurance company, is in charge of looking over the accident, reviewing evidence, and deciding which policy is the right option for you. Your insurance may also request photos of the damage, the police report, witness information, and repair estimates. Depending on the situation and the severity of the accident, the adjuster may inspect the vehicle and the insurance companies involved may communicate together to determine the who was responsible and what coverage works.

Repairs and Payments

Once the insurance company evaluates the damage of the vehicle, the insurance declares whether the vehicle can be repaired or declared a total loss.  If repairs are possible, the insurance may cover eligible costs, taking out any applicable deductible. Some drivers are allowed to choose a repair shop; however, it is best to check with your insurer and the state rules. If the repair cost of the vehicle is too much compared to its value, the insurer may declare it a total loss. In these cases, the insurance calculates the vehicle’s cash value and often offers a settlement based on the coverage. In cases where the driver still owes a car loan, the insurance company may not always cover the remaining loan balance.


Car accident can be difficult to handle and are often overwhelming. However, understanding the insurance process can help you understand what steps to take and what to expect as the outcome. Before anything drivers should focus on safety, reporting the incident, and documenting evidence. After that, the insurance company investigates the claim, determines the applicable coverage, and potentially takes care of any repairs and costs. Even though every accident is not the same, being prepared and having basic understanding can help you make the process easier and less stressful.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: Sara Trajanoska


Five Insurance Mistakes That Can Cost You Thousands

A few small insurance mistakes might not seem like a big deal—until one of them leaves you paying thousands of dollars out of pocket.

Insurance is meant to protect you financially when the unexpected happens, but having a policy doesn’t automatically mean you’re fully protected. Choosing limits that are too low, skipping important coverage, or failing to review your policy can create expensive gaps you may not notice until it’s too late.

Here are 5 mistakes that can cost you thousands of dollars and then how to avoid them.

1. Not Updating Your Insurance After Major Life Changes

Your insurance should change as your life changes.

Buying a new vehicle, renovating your home, getting married, starting a business, adding a teenage driver, or purchasing expensive belongings can all affect your insurance needs.

One common example is home renovations. If you significantly upgrade your kitchen, finish your basement, or add onto your home but never tell your insurance agent, your current dwelling limit may no longer reflect what it would cost to rebuild your home.

The same goes for expensive jewelry, electronics, collectibles, or other valuables. Standard homeowners policies may have limitations for certain types of property, so additional coverage may be necessary.

Reviewing your policies after major changes can help make sure your coverage still matches your life.

2. Choosing Coverage That Is the Cheapest

Everyone wants to save money, but the cheapest insurance policy isn’t always the best deal.

A lower premium can sometimes mean lower liability limits, higher deductibles, or fewer coverage options. That may not seem like a big deal until you have a serious claim.

For example, imagine you cause an accident that results in $75,000 in injuries, but your auto policy only provides $25,000 in bodily injury liability coverage. Depending on the circumstances, you could potentially be responsible for the amount that exceeds your policy limits.

Instead of looking only at the monthly price, consider what you’re actually getting for your premium. Saving a few dollars each month may not be worth taking on thousands of dollars in additional risk.

3. Assuming Everything Is Automatically Covered

One of the biggest insurance mistakes is assuming your policy covers something without actually checking.

Insurance policies contain exclusions, limitations, deductibles, and specific coverage conditions. For example, a standard homeowners policy generally does not provide coverage for every type of water or flood damage. Certain valuables may also have coverage limits, and business equipment kept at home may not receive the same protection as personal belongings.

Auto policies can also vary when it comes to rental reimbursement, roadside assistance, custom equipment, or coverage for certain drivers.

Before something happens, ask your insurance agent questions like, “Would my policy cover this?” and “Are there any limits or exclusions I should know about?”

It’s much better to find out before a claim than afterward.

4. Never Reviewing Your Insurance Policy

One of the easiest insurance mistakes to make is assuming that once you have a policy, you never need to look at it again. But your life can change a lot from year to year, and your insurance should change with it.

Buying a new car, remodeling your home, getting married, adding a new driver, starting a business, or purchasing expensive belongings can all affect the amount and type of coverage you need. If your policy still reflects your situation from several years ago, you could have gaps in coverage without realizing it.

Rates and discounts can also change over time. You may qualify for savings you didn’t have before, or another insurance carrier may offer better coverage for a similar price.

Reviewing your insurance at least once a year gives you a chance to make sure your limits, deductibles, discounts, and coverage options still make sense. A short policy review now could help prevent a much more expensive surprise later.

5. Skipping Umbrella Insurance

Many people assume the liability coverage on their home and auto policies is enough, but a serious accident or lawsuit can quickly exceed those limits.

Umbrella insurance provides an extra layer of liability protection above the limits of certain underlying policies, such as auto or homeowners insurance. For example, if you’re responsible for a major car accident and the damages are higher than your auto liability limit, an umbrella policy may help cover the remaining eligible costs up to its own limit.

Without that additional protection, you could be responsible for paying the difference out of pocket. Depending on the situation, that could put your savings, income, and other assets at risk.

Umbrella insurance can be especially worth considering if you own a home, have significant savings or assets, have young drivers in your household, own rental property, or simply want additional protection against a large liability claim.

Skipping umbrella coverage might save you money on your premium today, but one major lawsuit could cost far more in the long run.

Conclusion

Insurance mistakes are often easy to overlook, but they can become very expensive when a claim happens. Taking the time to review your coverage, understand your limits, and make sure you have the protection you actually need can help prevent major financial surprises.

Your insurance should grow and change along with your life. If it’s been a while since you reviewed your policies, now may be a good time to speak with an independent insurance agent and make sure you’re properly protected.


You can experience being a part of and full-serviced independent Insurance Agency today! Simply contact Briggs Agency Inc, if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog Post Written by: Alex Condes

Why Commercial Contractor Insurance Matters for Local Builders

Running a construction business means managing countless moving parts, and one critical piece often gets overlooked: commercial contractor insurance. Without proper coverage, a single accident or equipment loss can drain your finances and threaten everything you’ve built.

At Briggs Agency, Inc., we’ve seen too many local builders operate without adequate protection. The right policy isn’t just a safety net-it’s a business essential that keeps your operations running smoothly when unexpected events happen.

What Your Contractor Insurance Actually Protects

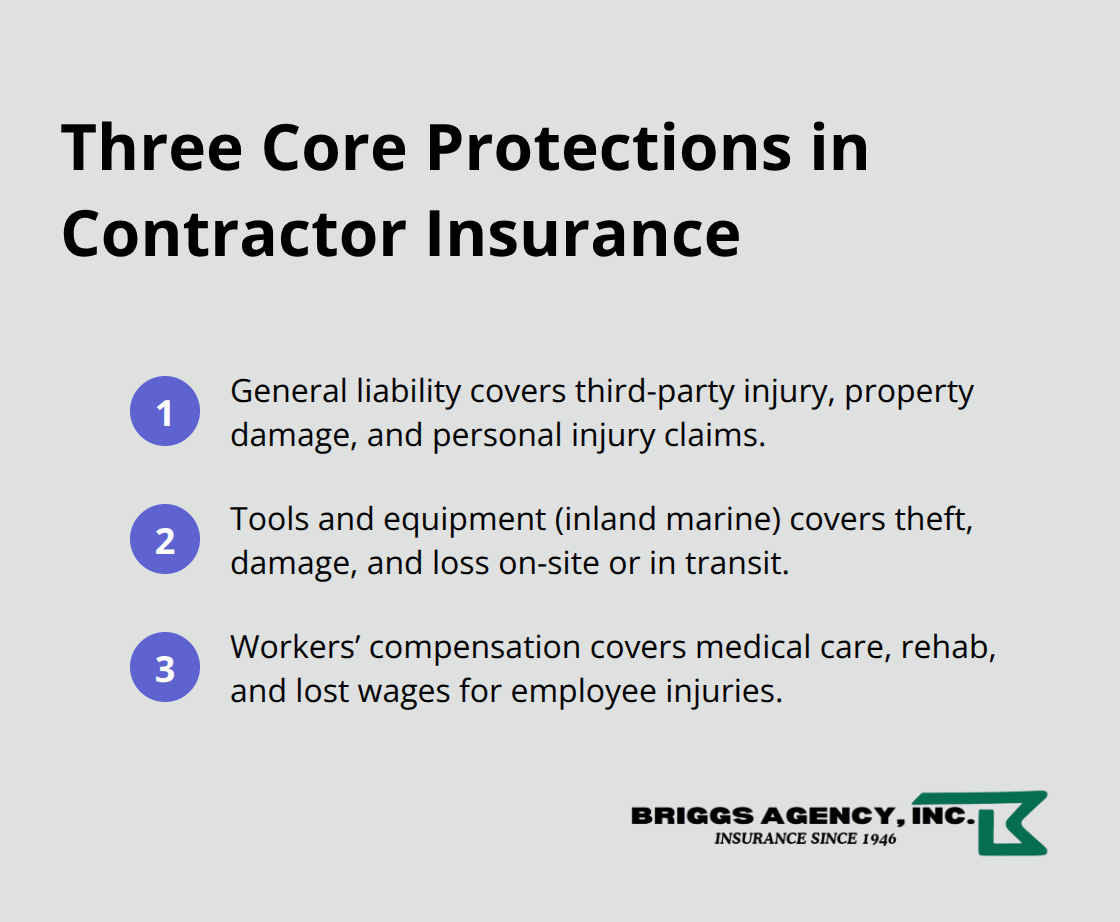
Commercial contractor insurance covers three distinct areas that directly impact your bottom line, and understanding what each one does prevents expensive gaps in your protection. General liability insurance protects you when third parties claim bodily injury, property damage, or personal injury arising from your work-incidents like accidentally damaging a client’s kitchen cabinet or someone getting injured on your job site. General liability coverage costs between $750 and $2,500 annually for a standard $1M/$2M policy for small-to-mid-sized contractors. This coverage shields you from paying out of pocket when someone sues over injuries or damage connected to your operations, and many clients now require proof of this coverage before they’ll hire you.

Key contractor insurance protections summarized for U.S. builders

Tools and Equipment Coverage Keeps Projects Moving

Tools and equipment insurance protects the expensive gear that keeps your projects moving forward, covering theft, damage, and loss whether your equipment sits at a job site or travels between locations. A single theft of a power tool collection or a damaged compressor can stall work for days and cost thousands to replace, which is why this coverage matters more than most builders realize. Inland marine insurance specifically covers contractor tools, mobile equipment, and even leased or borrowed gear, paying either replacement cost or actual cash value depending on your policy. This protection ensures that unexpected equipment loss doesn’t force you to halt operations or absorb replacement costs that eat into your profit margins.

Workers’ Compensation: Legal Protection and Employee Care

Workers’ compensation insurance is legally required in most states and covers medical costs, rehabilitation, and lost wages when your employees get injured on the job. California requires workers’ compensation coverage for licensed contractors even if you have no employees, which means solo operators cannot skip this protection. This coverage shields your business from lawsuits while ensuring injured workers receive proper care, keeping your operation compliant with state law and protecting your ability to keep working. When an injury happens on site, workers’ compensation handles the financial burden so you can focus on recovery and getting back to your projects-which is exactly what your next step should address.

Real Risks Contractors Face Without Proper Coverage

Property Damage Claims Drain Your Finances Fast

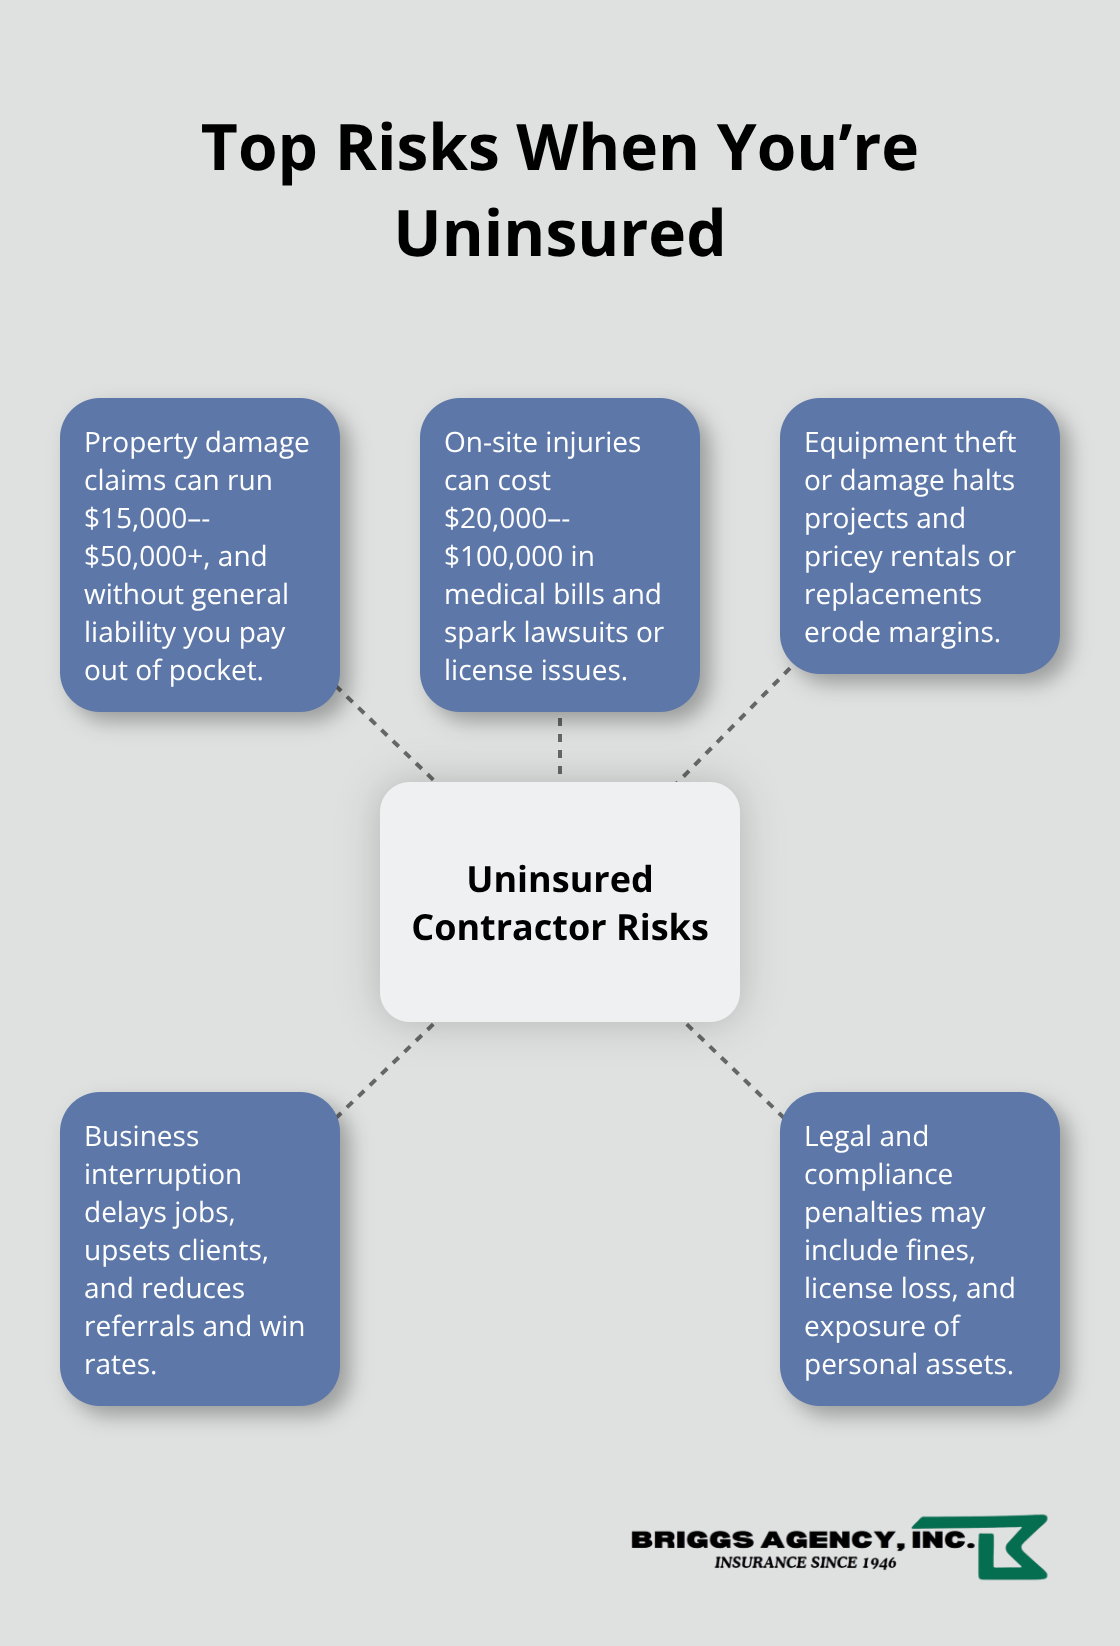
A single property damage claim costs $15,000 to $50,000 or more, depending on what gets damaged and how extensive the repairs are. Without general liability coverage, you write that check yourself-directly from your business account. Contractors lose months of profit recovering from one incident where they accidentally damaged a client’s flooring or broke a window. The Hartford reports that construction businesses pay roughly $113 per month for general liability coverage, which works out to about $1,351 annually. That small premium protects against a major claim, especially when clients now routinely require proof of $1 million in coverage before they sign a contract. Many builders think they can skip this protection on smaller jobs, but property damage doesn’t care about project size-a mistake on a kitchen remodel costs just as much to fix whether the job is worth $5,000 or $50,000.

On-Site Injuries Create a Financial and Legal Trap

Injury claims on job sites catch unprepared contractors off guard with staggering costs. Medical bills alone for a serious on-site injury exceed $20,000 to $100,000 depending on severity, and without workers’ compensation coverage, you face both the medical costs and potential lawsuits from the injured person. Legal defense costs compound the problem quickly-even a claim that gets dismissed still requires attorney fees that drain cash flow faster than most builders anticipate. Contractors operating without proper coverage also risk losing their license, facing fines from state labor departments, and getting sued personally, which means creditors can come after your personal assets and savings. Beyond the immediate financial hit, a serious incident creates operational chaos: your crew stops working while investigating the injury, clients get nervous about your safety practices, and your reputation takes damage that affects future bids.

Equipment Theft and Damage Stop Projects Cold

Equipment theft or damage presents a risk that most contractors underestimate until it happens. A stolen trailer full of tools or a damaged compressor doesn’t just cost money to replace-it stops your projects cold. You lose productivity, miss deadlines, and potentially face penalty clauses in your contracts. Some contractors respond by renting replacement equipment at premium rates, which eats into profit margins and compounds the original loss. Business interruption from these events creates a domino effect: delayed projects lead to unhappy clients, which leads to fewer referrals and harder bids to win.

Hub-and-spoke diagram showing major risks contractors face without insurance - Commercial contractor insurance

These three exposure areas-property damage, employee injuries, and equipment loss-show why comprehensive coverage matters so much. Understanding how to select the right policy for your specific work is the next step toward protecting your business from these preventable financial disasters.

How to Choose the Right Contractor Insurance Policy

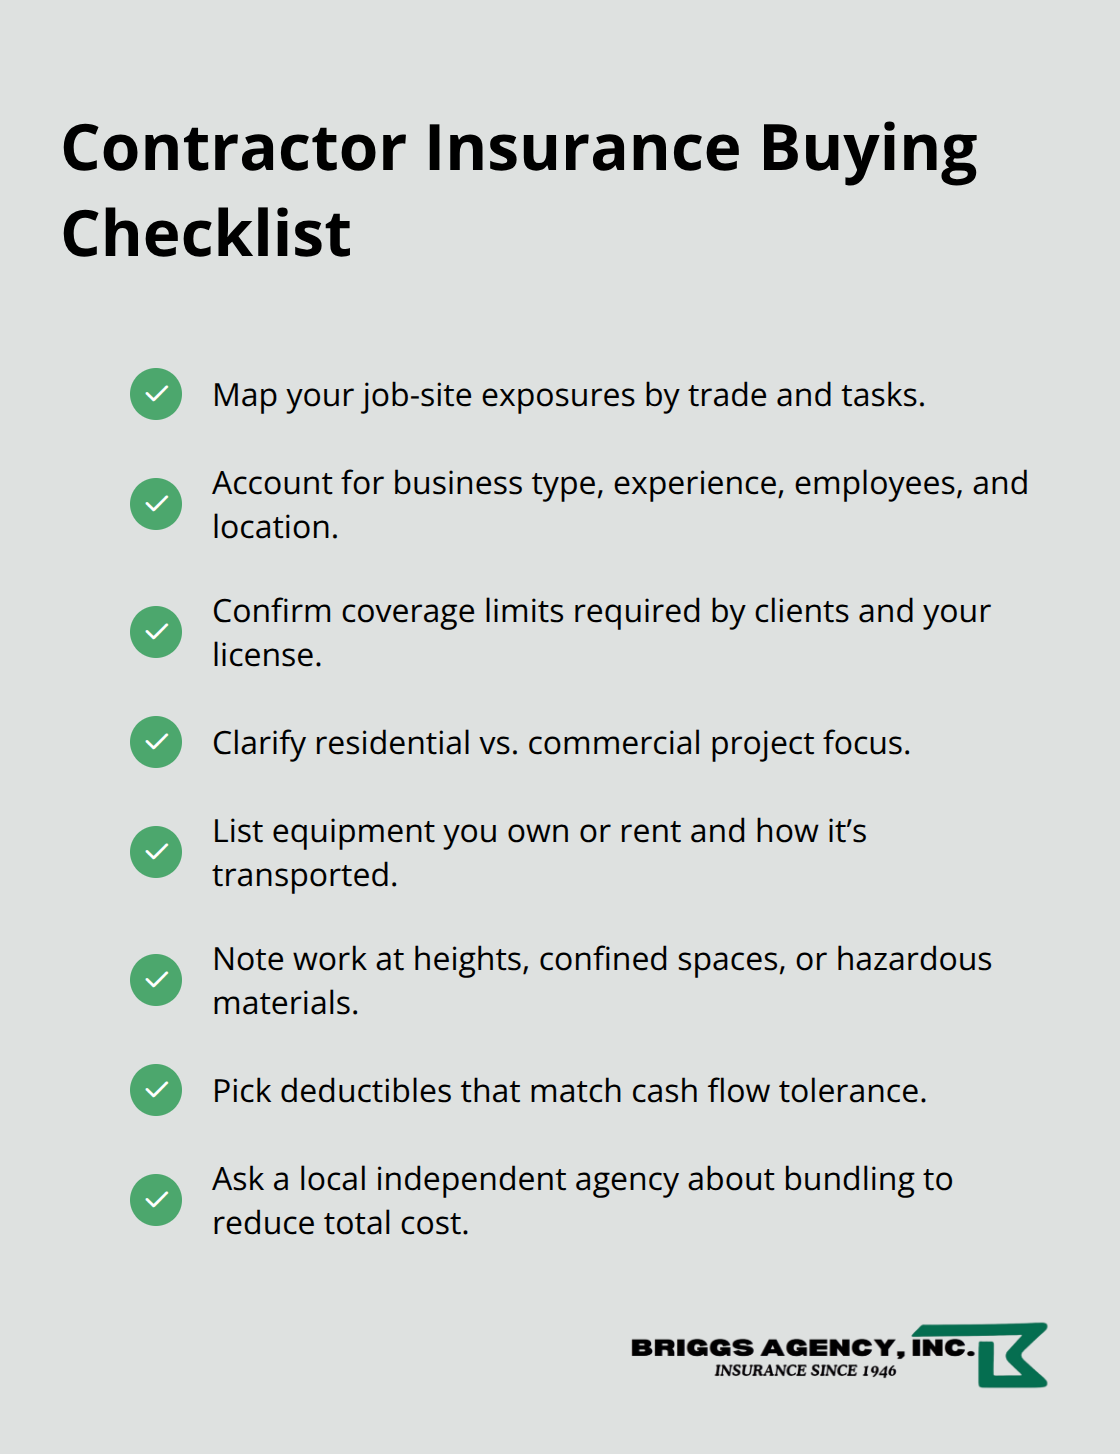
Start by mapping your actual job site exposure and which risks show up most often in your specific trade. A framing contractor faces different exposures than a plumber or electrician, and your policy needs to reflect those differences or you’ll pay for coverage you don’t need while leaving gaps in areas where you do. The Hartford reports that factors like business type, experience level, number of employees, location, coverage limits, deductibles, and claims history all shape your premium and available options. Get specific about your projects: Do you work mostly residential remodels or commercial builds? Do you rent equipment or own it? Do you work at heights or in confined spaces? Do you handle hazardous materials?

Checklist to choose the right contractor insurance policy in the U.S. - Commercial contractor insurance

Each answer points toward different coverage needs. A solo carpenter doing kitchen remodels needs different protection than a five-person framing crew working on new construction. Once you understand your actual exposures, you can stop overpaying for irrelevant coverage and ensure you’re protected where it matters most.

Coverage Limits Matter More Than You Think

Most contractors default to the standard $1 million general liability limit because it’s common, but that doesn’t mean it’s right for your work. Before you settle on any limit, check what your clients require contractually and what your state mandates for your license type. Many clients now demand $2 million in aggregate coverage, which costs more but becomes non-negotiable when you’re bidding larger projects. The real mistake happens when contractors choose limits based on premium cost alone instead of actual exposure. A single serious injury claim or major property damage incident can exceed standard limits quickly, and then you’re personally liable for the overage. Compare what different carriers charge for moving from $1 million to $2 million coverage-the price difference often surprises contractors who assumed it would cost substantially more. Deductibles work the same way: a higher deductible lowers your monthly premium but means you pay more out of pocket when a claim happens. Most contractors find a $1,000 or $2,500 deductible strikes the right balance between affordable premiums and manageable out-of-pocket exposure, but your specific cash flow situation should drive that decision.

Local Agents Bring Market Knowledge to Your Coverage Decisions

An independent agency that knows your community understands the specific risks contractors face in your area-whether that’s seasonal weather patterns, local building code requirements, or common claim types in your region. When you call a national carrier’s 1-800 number, you get generic quotes based on limited information. When you work with a local agent, they ask detailed questions about your actual operations, your safety practices, your claims history, and your growth plans over the next few years. That conversation reveals coverage gaps you might not have considered and uncovers bundling opportunities that lower your total cost. Many contractors save significantly when they combine general liability, tools and equipment, and commercial auto coverage under one agency relationship. A local independent agency represents multiple carriers instead of locking you into one company’s options and pricing. This access to multiple top-rated carriers means your agent can compare options and tailor policies to deliver competitive pricing and the right protection for your specific work. A local agent also handles the administrative burden when claims happen-they advocate for you with the carrier, help navigate the process, and ensure you get paid fairly. After a property damage claim or injury incident, that relationship matters more than the premium you saved shopping online.

Final Thoughts

Commercial contractor insurance protects your business from the real financial threats that stop contractors cold. A single accident, equipment loss, or injury claim forces you to choose between paying claims out of pocket or risking your business license and personal assets-that’s not a choice any builder should face. The coverage you’ve read about in this post addresses these threats directly and keeps your operation running when unexpected events happen.

Your next step starts with honest conversations about your actual work. What types of projects do you handle most often, how many employees work for you, and what equipment do you own or rent? These details shape which coverages matter most and help you avoid paying for protection you don’t need while staying covered where it counts. Moving from a $1 million to $2 million liability limit often costs less than contractors expect, and that extra protection becomes essential when clients demand higher limits before signing contracts.

A local independent agency that represents multiple carriers delivers the best path forward for your commercial contractor insurance needs. We at Briggs Agency, Inc. have served Crown Point and surrounding communities since 1946, helping contractors and business owners reduce risk and protect what they’ve built. Contact Briggs Agency, Inc. today to discuss your contractor insurance needs and get a quote that reflects your actual exposure.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.

10 Things Your Homeowners Insurance Doesn’t Cover

You might think your homeowners insurance covers just about anything—but some of the most expensive surprises are the ones your policy may not cover at all. From floods and sewer backups to pest damage and everyday wear and tear, there are several common situations that can leave homeowners paying out of pocket. Knowing these exclusions ahead of time can help you spot potential gaps in your coverage before you ever need to file a claim.

Here are 10 things homeowners insurance typically doesn’t cover.

1. Flood Damage

One of the biggest misconceptions about homeowners insurance is that it covers flooding. In most cases, it doesn’t.

Damage caused by rising water, heavy rainfall that enters your home from the ground, overflowing rivers, or storm surge typically requires a separate flood insurance policy.

Even homes outside high-risk flood zones can experience flooding, so it may be worth discussing your risk with your insurance agent.

2. Earthquakes and Ground Movement

Standard homeowners insurance generally excludes damage caused by earthquakes and certain types of ground movement.

This can include:

  • Earthquakes
  • Landslides
  • Mudslides
  • Sinkholes
  • Earth shifting or settling

Depending on where you live, earthquake or other specialty coverage may be available separately.

3. Normal Wear and Tear

Homeowners insurance is intended for sudden and unexpected damage—not things that happen because your home gets older.

For example, your policy usually won’t pay to replace a roof simply because it has reached the end of its useful life.

Other examples can include:

  • Worn-out flooring
  • Aging appliances
  • Peeling paint
  • Deteriorating siding
  • Old plumbing

Regular home maintenance is still the homeowner’s responsibility.

4. Damage From Poor Maintenance

Ignoring a problem for months and then filing an insurance claim usually won’t work.

For example, if you notice a small roof leak but leave it unrepaired until it causes major water damage, some or all of the damage could be excluded.

Insurance companies generally expect homeowners to take reasonable steps to maintain their property and prevent additional damage.

5. Pest and Insect Damage

Discovering termites, mice, squirrels, or other unwanted guests can get expensive quickly.

Unfortunately, homeowners insurance typically doesn’t cover damage caused by infestations because pest problems are generally considered preventable through routine maintenance.

This can include damage from:

  • Termites
  • Bed bugs
  • Rodents
  • Ants
  • Other insects or pests

6. Sewer or Drain Backups

If sewage or water backs up through a drain or sump pump and damages your basement, a standard homeowners policy may not automatically cover it.

However, many insurance companies offer water backup coverage as an optional endorsement.

This relatively small addition to your policy can provide valuable protection, especially if you have a finished basement or keep valuable belongings downstairs.

7. Certain Expensive Valuables

Your personal property is typically covered by homeowners insurance, but certain categories of valuable items may have special limits.

These can include:

  • Jewelry
  • Watches
  • Fine art
  • Firearms
  • Collectibles
  • Coins
  • High-value electronics

For example, you may have thousands of dollars of jewelry but only a limited amount of coverage for theft under your standard policy.

High-value items may need to be scheduled separately to receive broader or higher limits of protection.

8. Business-Related Property and Liability

More people than ever work or operate businesses from home, but homeowners insurance isn’t designed to fully protect a business.

Your policy may provide very limited coverage for business equipment, and certain business-related liability claims may be excluded entirely.

If you operate a business from your home, you may need a home-business endorsement or separate commercial insurance.

9. Intentional Damage

Insurance is designed to protect against accidents—not intentional actions.

If a homeowner intentionally damages their own property or deliberately causes a loss, homeowners insurance will generally not cover it.

Intentional acts that cause injury or property damage to someone else may also be excluded from liability coverage.

10. Your Car

Your homeowners policy may cover certain personal belongings that are stolen from your vehicle, depending on the circumstances and your policy.

But damage to the vehicle itself isn’t covered by homeowners insurance.

For example, if a tree falls on your car during a storm, the damage would normally fall under the comprehensive portion of your auto insurance, not your homeowners policy.


Homeowners insurance can provide valuable protection, but it’s just as important to understand what your policy doesn’t cover as what it does. Knowing about common exclusions can help you avoid unexpected expenses and make sure you have the right additional coverage in place.

Every home and homeowners policy is different, so reviewing your coverage regularly is one of the best ways to make sure you’re properly protected.

You can experience being a part of and full-serviced independent Insurance Agency today! Simply contact Briggs Agency Inc, if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes and David Stefanoski


Contractor Liability Insurance: Guarding Your Projects and Profits

One accident on your job site can cost thousands in medical bills, legal fees, and settlements. Contractor liability insurance protects your business from these financial disasters.

At Briggs Agency, Inc., we’ve helped countless contractors understand why this coverage isn’t optional-it’s essential for survival. Whether you’re a solo operator or managing a larger team, the right policy keeps your projects and profits safe.

What Contractor Liability Insurance Actually Protects

Bodily Injury Coverage Shields You from Medical and Legal Claims

Contractor liability insurance covers three distinct areas of financial exposure that can sink your business if left unprotected. First, it pays for bodily injury claims when someone gets hurt because of your work. If a client’s employee trips over your equipment and breaks a leg, or a passerby is struck by debris from your job site, this coverage handles their medical bills, lost wages, and legal settlements. A single serious injury claim can easily exceed $100,000 in medical costs alone, not counting legal defense.

Property Damage Liability Protects Against Costly Accidents

Second, the policy covers property damage liability, which protects you when your work damages someone else’s property. You might puncture a water line while excavating, damage a neighbor’s fence, or break an HVAC unit during installation-this coverage pays for repairs or replacement. Without this protection, you absorb the full cost of repairs, which can range from thousands to tens of thousands of dollars depending on the damage.

Legal Defense Costs Keep You Protected in Court

Third, it covers your legal defense costs, meaning the insurance company pays for attorneys and court expenses even while your claim is being investigated. Many contractors assume they’ll never need this, then face substantial legal fees before a case is even settled. Most general liability policies include all three protections under one standard policy with limits of $1,000,000 per occurrence and $2,000,000 products and completed operations aggregate, though larger projects often demand higher limits.

Why Clients Require This Coverage Before Work Starts

Most commercial contracts now require proof of liability insurance before work begins. Clients want a Certificate of Insurance naming them as an additional insured, which means they’re also protected under your policy. Without this documentation, you won’t land legitimate commercial jobs. On residential projects, homeowners increasingly ask for proof of coverage because their own homeowner’s policies explicitly exclude damage caused by contractor work. If you cause damage and can’t prove you’re insured, the homeowner’s only recourse is to sue you personally, putting your home, vehicles, and bank account at risk.

Completed Operations Coverage Extends Protection After Project Completion

Completed operations coverage, included in most contractor policies, extends protection for up to one year after project completion-critical because defects or injuries can surface weeks or months later. For high-risk trades like roofing or excavation, this tail coverage is absolutely essential. This extended window of protection is why understanding your specific coverage limits matters so much when you assess your business needs.

Why Contractors Need Liability Insurance

A Single Accident Can Wipe Out Your Profits

Liability lawsuits destroy contractor finances in ways most business owners never anticipate until it’s too late. A single claim for bodily injury or property damage can exceed $500,000 in legal defense costs and settlements combined, and without insurance, that bill falls directly on you. Construction industry data shows that contractors without adequate liability coverage face significant out-of-pocket losses per major incident, according to the Construction Industry Institute. That money comes straight from your profits, your equipment fund, or forces you to liquidate assets or close the business entirely.

The financial math is straightforward: a $1,500 annual premium for solid liability protection costs far less than absorbing a $200,000 property damage claim or a $300,000 settlement for a serious injury. One accident on your job site can cost thousands in medical bills, legal fees, and settlements-liability insurance protects your business from these financial disasters.

Clients and Lenders Won’t Work Without Proof of Coverage

Your clients won’t work with you without proof of coverage, and lenders won’t finance projects if you lack it. Most commercial contracts now require you to name the client as an additional insured on your policy before any work starts, and many residential homeowners demand a Certificate of Insurance showing active coverage. If you can’t provide documentation, you don’t get the job-it’s that straightforward.

Commercial property owners and general contractors treat liability insurance as a non-negotiable requirement. They protect themselves by ensuring your policy covers their interests, which means you must have the right coverage in place before you show up on site.

Liability Insurance Protects Your Personal Assets and Reputation

Beyond client requirements, liability insurance protects your personal assets and business reputation. A lawsuit without insurance protection can force you into personal bankruptcy, threaten your home equity, and damage your standing in your local construction community. Contractors with solid liability coverage build trust faster, win more bids, and operate with the confidence that a single accident won’t end their business.

Your reputation in the construction industry depends on demonstrating that you operate professionally and responsibly. Proof of adequate coverage signals to clients, lenders, and other contractors that you take risk seriously and protect everyone involved in your projects.

The Right Coverage Positions You for Growth

Contractors with proper liability protection can pursue larger projects, bid on commercial work, and attract better clients who value professionalism. Without this foundation, you remain limited to smaller residential jobs where clients may not require proof of coverage-but those opportunities pay less and offer less stability. The contractors who build sustainable, profitable operations understand that liability insurance isn’t an expense; it’s an investment in business growth and security.

Understanding what coverage you actually need and how much protection fits your specific work is the next step toward building that foundation.

How to Choose the Right Coverage for Your Business

Assess Your Trade and Risk Profile

Your trade classification determines your base insurance rate and risk profile. According to the National Association of Insurance Commissioners, electricians typically pay $750 to $2,500 annually for standard coverage, framers pay $1,500 to $3,000, and roofers pay $3,000 to $6,000 or more due to higher injury and property damage frequency. Excavation and civil contractors fall into the $2,500 to $5,000 range. These figures reflect real underwriting data, not estimates.

A painter handling residential interior work might operate safely with $1,000,000 per occurrence and $2,000,000 products and completed operations aggregate, while a framing contractor or general contractor tackling commercial projects needs substantially higher protection. The difference matters because underinsured contractors face personal liability when claims exceed their coverage limits. If you carry $1,000,000 coverage and a claim settles at $1,500,000, you personally owe the difference.

Match Coverage Limits to Project Size and Client Demands

Project size and client requirements should drive your coverage decisions. A homeowner renovation might require only basic $1M/$2M limits, but commercial general contractors increasingly demand $2,000,000 per occurrence and $5,000,000 aggregate from subcontractors. Some large commercial projects specify $5,000,000 umbrella coverage on top of underlying limits, which means you need $6,000,000 per occurrence and $7,000,000 products and completed operations protection. Refusing to meet these requirements simply means losing the job.

Higher coverage limits increase premiums, but they’re mandatory for business growth. Contractors who stay limited to small residential work because they refuse adequate coverage sabotage their own profitability and scalability. The investment in proper limits pays back immediately through access to better-paying commercial projects and client confidence.

Factor in Location and Deductible Strategy

Your location multiplies your base rate significantly. High-litigation states like New York push premiums to $3,500 to $6,500 for the same $1M/$2M coverage, while tort-reform states like Ohio and Texas range from $700 to $1,800. This isn’t arbitrary pricing; it reflects actual claims history and legal environment in each state.

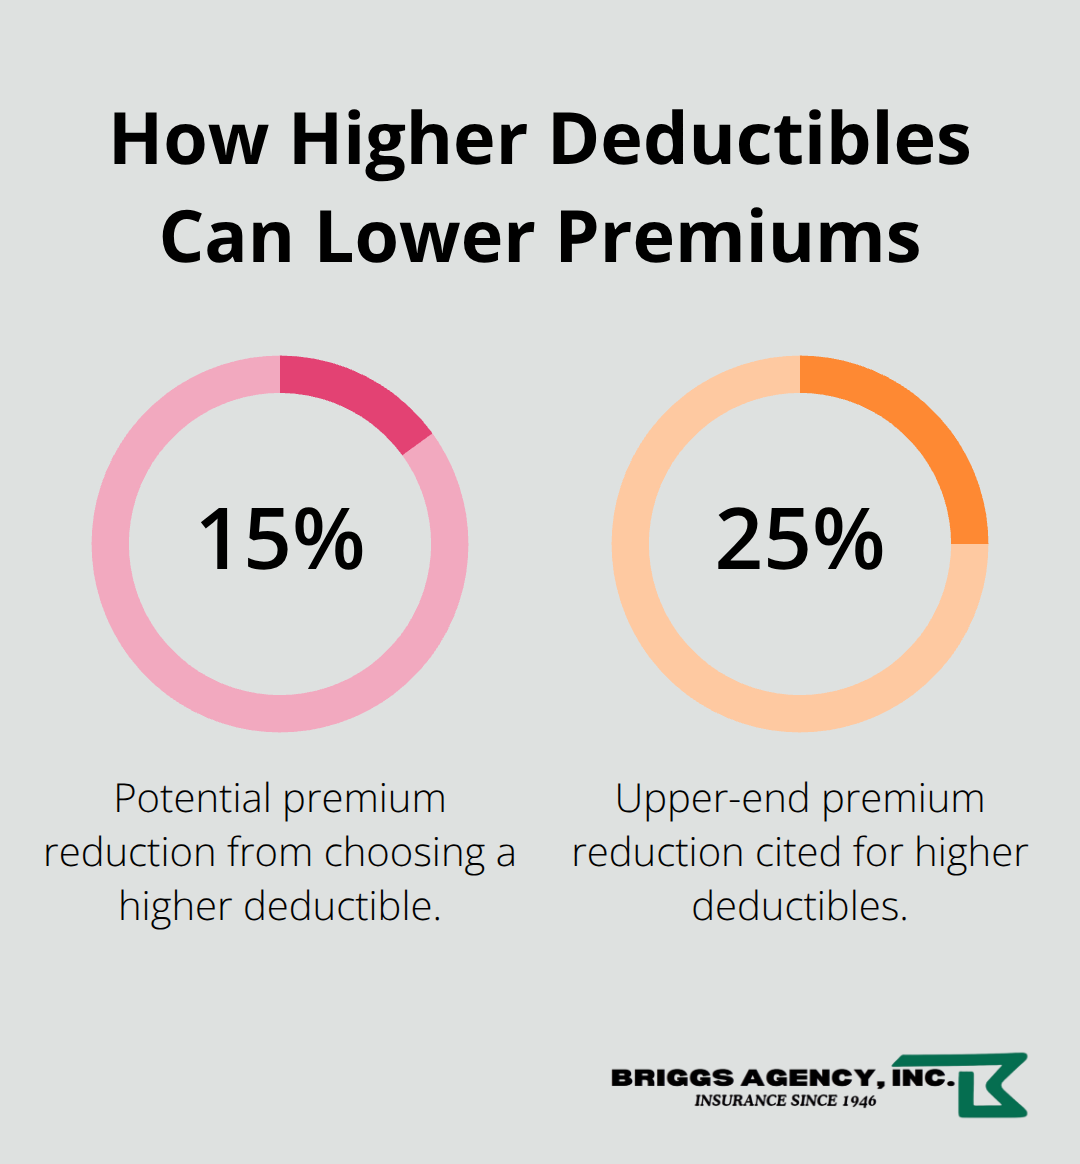
Your deductible choice directly trades premium savings for out-of-pocket risk. A $500 deductible costs more upfront but limits your exposure per claim, while a $2,500 or $5,000 deductible reduces your annual premium by 15 to 25 percent but increases what you pay when a claim occurs. Most contractors try $1,000 deductibles as the practical middle ground.

Premium reduction range when choosing higher deductibles. - Contractor liability insurance

Get a Customized Quote and Track Subcontractor Coverage

Get a customized quote based on your actual gross receipts, payroll, and subcontracted costs rather than guessing at coverage levels. Insurers calculate final premiums after a year-end audit that reviews your actual business activity, so starting with an accurate quote prevents audit penalties later. Uninsured or underreported subcontractors trigger audit reclassifications that can spike your final bill by 200 percent.

A strict no-Certificate-of-Insurance, no-payment policy prevents this expensive mistake. Digital COI tracking systems with real-time alerts cost little but eliminate the scramble to verify coverage before work starts. These systems help you maintain compliance and demonstrate mature risk-transfer processes to underwriters, which can improve your rates over time.

Final Thoughts

Contractor liability insurance forms the foundation that separates contractors who build sustainable businesses from those who operate on borrowed time. The coverage protects your finances when accidents happen, satisfies client and lender requirements, and shields your personal assets from catastrophic loss. Without it, a single incident destroys years of hard work and profitability.

Your trade classification, project size, location, and client demands determine what coverage you actually need (a painter’s requirements differ significantly from a roofer’s, and commercial work demands higher limits than residential projects). Matching your policy to your specific risk exposure prevents both underinsurance and overpaying for unnecessary protection. Getting a customized quote based on your actual gross receipts and payroll ensures you start with accurate pricing and avoid audit penalties later.

Contact Briggs Agency, Inc. to discuss your contractor liability insurance needs and find the right protection for your business. As a family-owned independent agency serving Crown Point, Indiana, we represent multiple top-rated carriers and compare options to deliver competitive pricing tailored to your trade, project scope, and growth plans. Our experienced local agents handle the complexity so you can focus on running your business safely and profitably.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Auto Shop Garage Insurance: Protecting Your Mechanics’ Business

Running an auto shop means managing countless moving parts-literally and figuratively. One wrong move during a repair, an employee injury, or a customer dispute can drain your finances fast.

At Briggs Agency, Inc., we’ve seen how the right auto shop garage insurance protects mechanics’ businesses from these real threats. This guide walks you through the coverage types that matter, the risks you face, and what actually affects your premiums.

What Your Auto Shop Insurance Actually Covers

Liability coverage protects your shop when a customer suffers an injury on your premises or claims your work caused damage to their vehicle. A baseline of $1 million per occurrence and $2 million aggregate is standard, but this only addresses bodily injury and property damage claims-not damage to the customer’s car while it sits in your bay. That’s where garage liability comes in, and it’s a separate animal that many shop owners overlook. General liability excludes business operations, so you need garage liability to close that gap. If you road-test vehicles or have multiple technicians driving customer cars, you should push your umbrella coverage to at least $2 million, possibly higher if you handle exotic or high-value vehicles. The cost difference between $1 million and $2 million umbrella coverage is typically $300–$600 annually, which is negligible compared to what a single serious injury claim could cost.

Protecting Customer Vehicles in Your Care

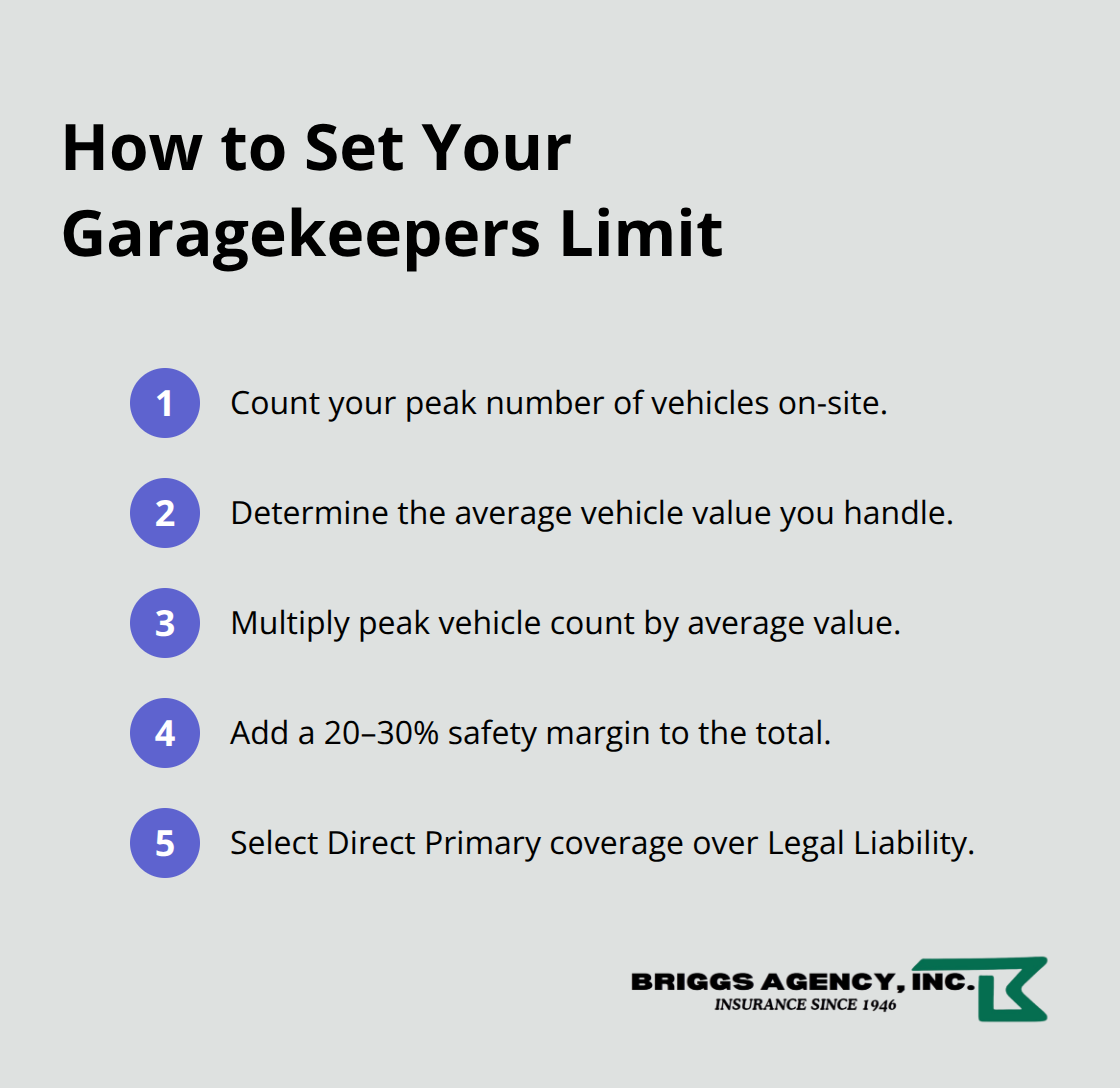
Garagekeepers coverage protects customer vehicles from fire, theft, vandalism, or collision while the car remains under your care, custody, and control. Most policies cap per-occurrence limits around $2,500, with a typical per-vehicle deductible of $500, but that’s often too low if you service high-value cars. Calculate your exposure by multiplying the maximum number of vehicles on-site at any time by the average vehicle value, then add 20–30% as a cushion. If you typically have 25 vehicles in your shop averaging $28,000 each, you’re looking at roughly $700,000 in exposure, so a $900,000 to $1 million limit makes sense.

Steps to calculate an appropriate garagekeepers coverage limit for an auto shop

Choose Direct Primary coverage over Legal Liability-Direct Primary pays claims immediately without requiring you to prove negligence, while Legal Liability requires proof and creates delays that frustrate customers and damage your reputation.

Tools, Equipment, and Shop Assets

Inland Marine coverage protects your diagnostic equipment, lifts, and specialty tools against theft, damage, or loss both on-site and in transit. This coverage matters because a stolen $8,000 diagnostic scanner or damaged lift can halt operations for weeks. Equipment breakdown coverage also protects your lifts and diagnostic tools from mechanical failure, which standard property policies exclude. Your shop’s tools and equipment represent significant capital investment, so verify that your Inland Marine policy covers the full replacement cost of your highest-value items.

Workers’ Compensation and Employee Protection

Workers’ compensation is legally required in most states and covers medical expenses and lost wages if an employee suffers an injury on the job. Your workers’ comp cost depends on your state’s classification codes, payroll breakdown, and experience modifier. Separate your clerical and sales payroll from your shop payroll to avoid misclassification, which can spike your rates unnecessarily. If your experience modifier sits above 1.0, request a detailed breakdown from your carrier to understand which claims or exposures drove the increase-sometimes errors in classification or reserve assumptions inflate your mod unfairly.

Moving Forward with Your Coverage Strategy

The right combination of liability, garagekeepers, inland marine, and workers’ compensation forms the foundation of your shop’s protection. However, your specific exposure depends on the services you offer and how you operate. Understanding these gaps now positions you to address the real risks that could disrupt your business.

Real Risks That Stop Auto Shops Cold

Vehicle Damage Claims Expose Hidden Gaps

Vehicle damage claims happen constantly in auto shops, and most owners dramatically underestimate their exposure. A customer’s $45,000 BMW sits in your bay while you perform brake service, and a technician accidentally backs into it with a lift. That $8,000 in damage falls outside your general liability policy because the vehicle was in your care. Garagekeepers coverage handles vehicles in your care, custody, or control that you don’t own while they’re being repaired, serviced, or stored at your business, but only if you’ve set your limits correctly. If you cap your coverage at $2,500 per occurrence, you absorb the remaining $5,500 personally. Shop owners often discover this gap the hard way, assuming garagekeepers would cover any vehicle damage, only to find their limits were insufficient. The solution is straightforward: calculate the total value of vehicles typically in your shop and set your garagekeepers limit to match that exposure plus a 20–30% buffer. If you service high-value or exotic vehicles, request per-vehicle sublimits that reflect their actual value rather than a blanket cap that leaves you exposed.

Employee Injuries Create Compounding Financial Pressure

Employee injuries create a different kind of financial trap. A technician suffers a back injury while removing a transmission, and your workers’ compensation covers his medical bills and partial wages during recovery. That baseline protection masks the real cost that emerges when the injury causes him to miss eight weeks of work and you need to hire a temporary replacement at $25 per hour. Your workers’ comp doesn’t reimburse that overtime or temp labor expense, so your profit margin absorbs the hit. Additionally, if your experience modifier sits above 1.0, each claim pushes your rates higher for three years, compounding the financial damage. Invest in loss prevention now: proper lifting techniques, ergonomic workstations, and regular safety briefings reduce claims significantly. Separate your shop payroll from clerical payroll when reporting to your carrier, because misclassification inflates your rates unnecessarily. A single preventable injury can cost you thousands in direct expenses plus years of elevated premiums.

Customer Disputes Over Workmanship Quality

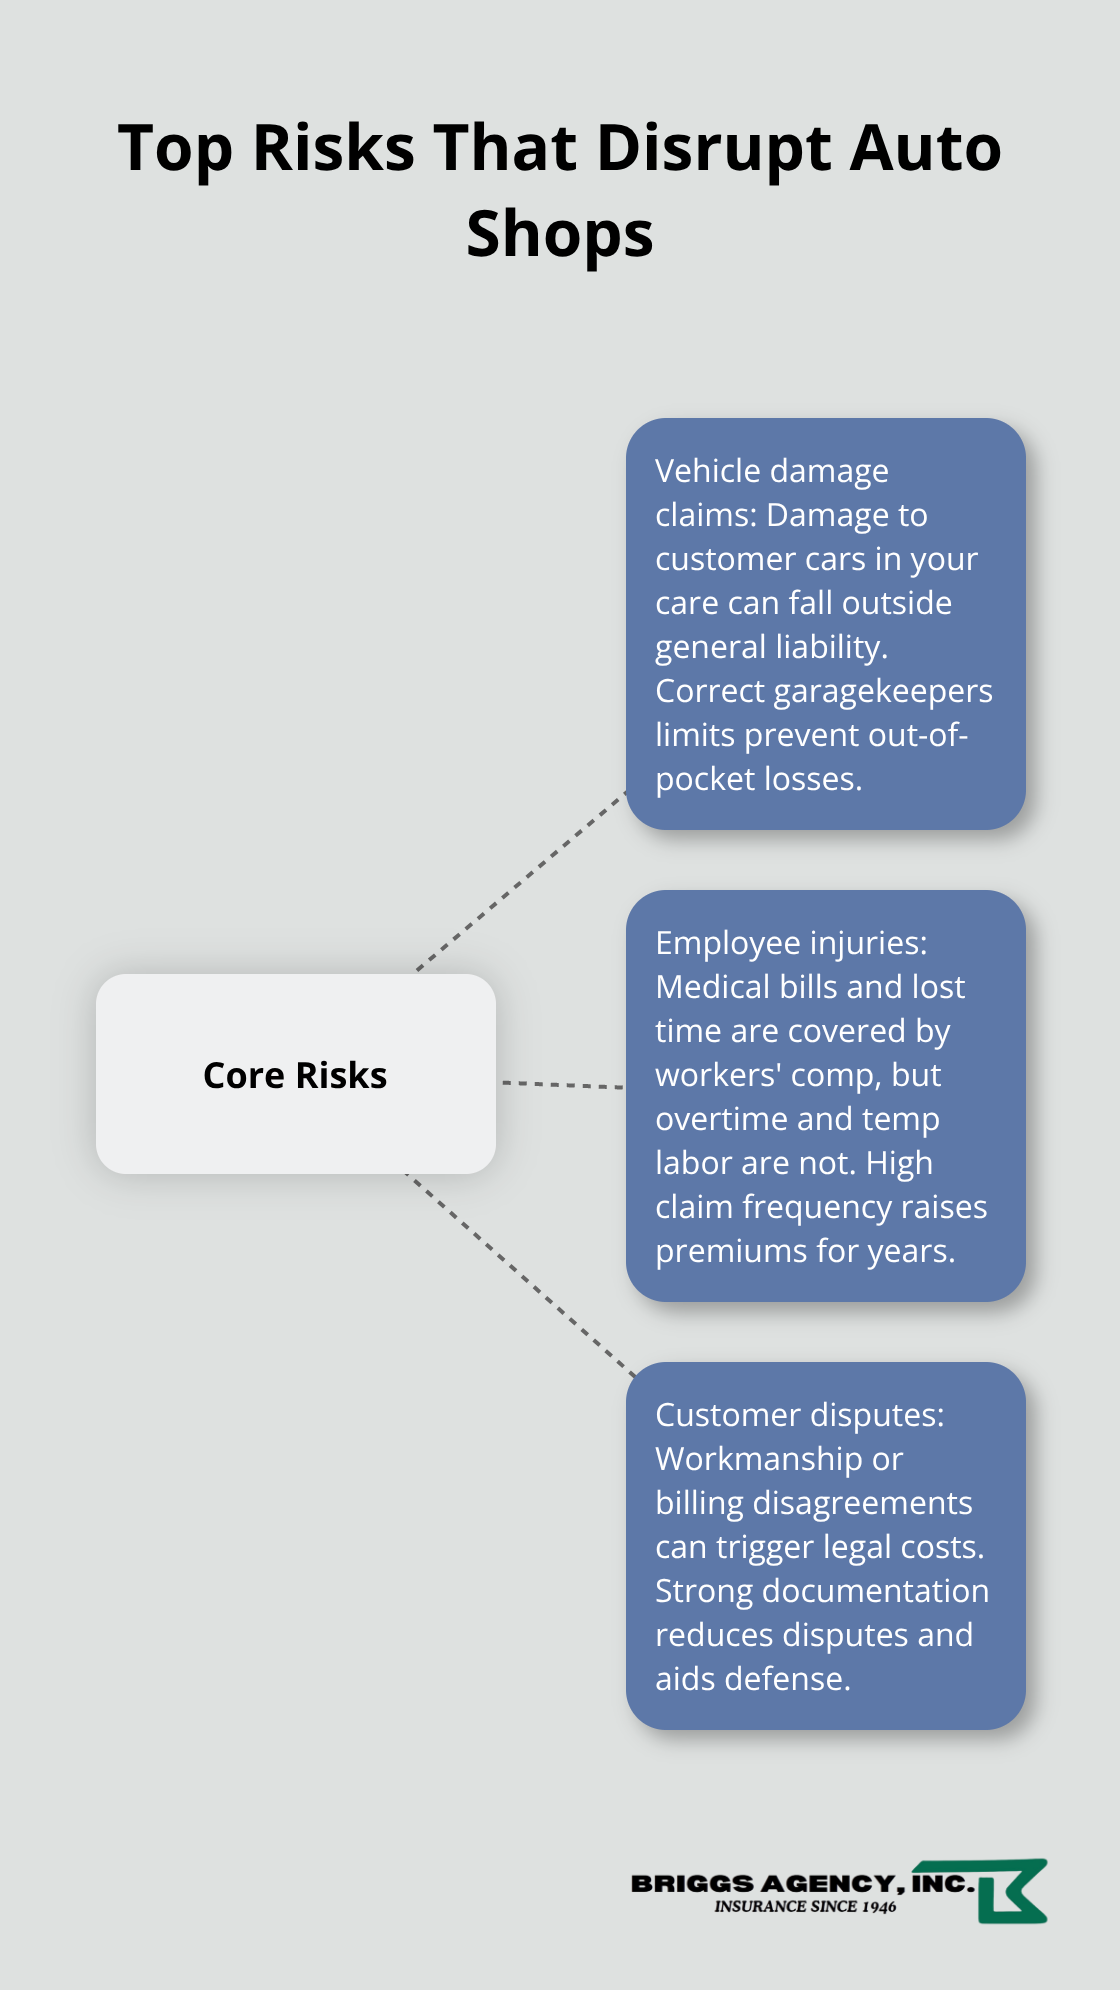
Customer disputes over repair quality or billing often escalate into legal claims that drain both time and money. A customer claims your shop installed a faulty alternator that failed two months after service, and now they demand $1,200 in damages plus rental car costs. Your garage liability covers bodily injury and property damage from your operations, but disputes over workmanship quality sit in a gray area that can trigger litigation costs regardless of whether you’re ultimately liable. Documentation becomes your strongest defense: photograph vehicles before and after service, provide written estimates that detail exactly what work will be performed, and maintain detailed service records that prove you followed proper procedures. Most customers won’t pursue legal action if your documentation clearly shows what was done and why. When disputes do occur, your liability coverage at least covers legal defense costs, which can easily exceed $5,000 before the case is resolved. These three risk categories-vehicle damage, employee injuries, and customer disputes-represent the most common threats to your shop’s financial stability, yet each one responds to specific coverage choices and operational practices that you control directly.

Hub-and-spoke diagram showing three major risk categories for auto repair shops - Auto shop garage insurance

What Actually Drives Your Auto Shop Insurance Costs

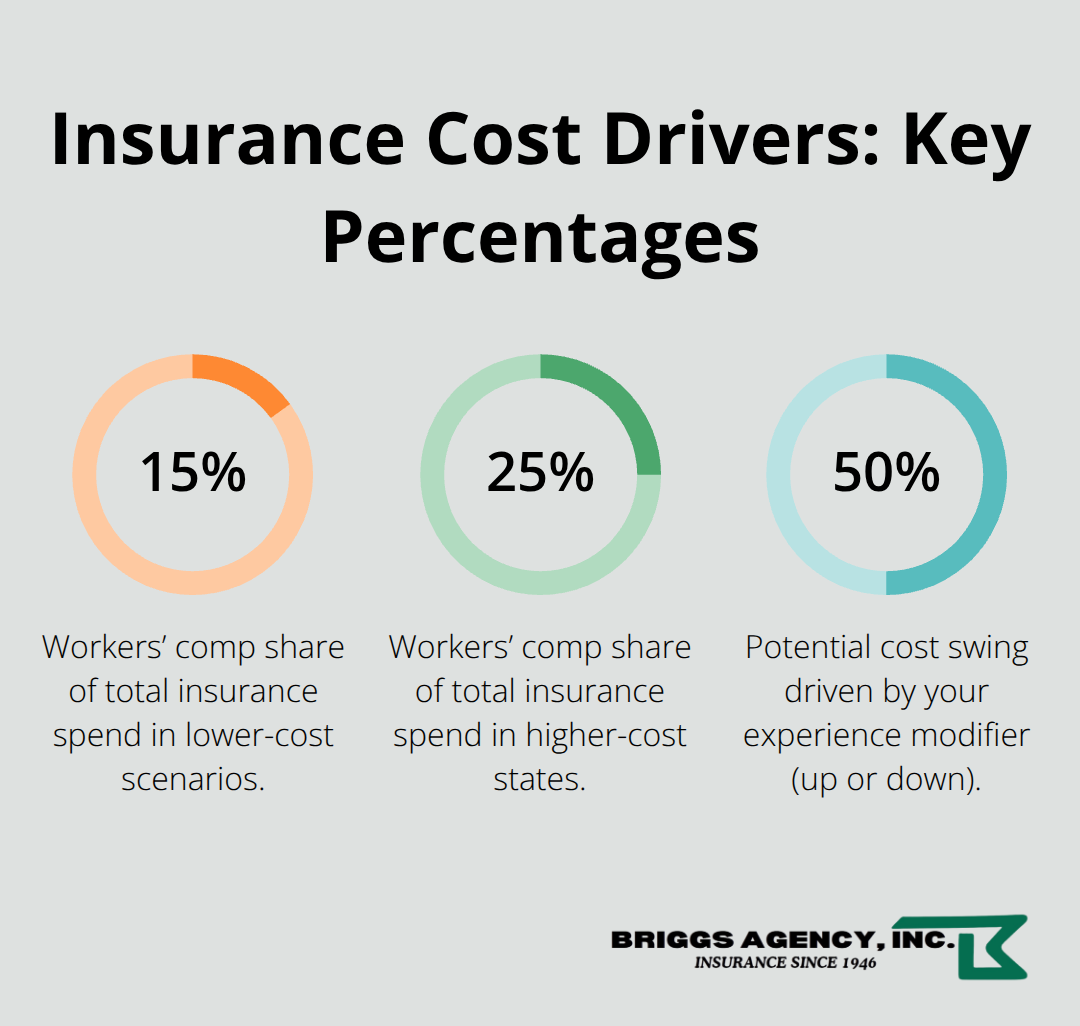
Your premiums reflect concrete operational factors that you control far more than most shop owners realize. The number of technicians on your payroll directly impacts your workers’ compensation costs, which typically represent 15–25% of your total insurance spend depending on your state. If you have five technicians earning $50,000 annually, your total payroll sits at $250,000, and your workers’ comp premium might run $8,000–$12,000 per year based on your state’s classification codes and experience modifier.

Percentage chart highlighting workers’ comp share and potential experience modifier impact on costs - Auto shop garage insurance

How Your Claims History Multiplies Costs

Your experience modifier-a multiplier that reflects your claims history-can swing that cost up or down by 30–50%. A modifier above 1.0 means you pay more than the standard rate because your shop filed more claims than the average shop in your classification. Request a detailed breakdown from your carrier showing which claims contributed to your modifier and what assumptions they used for reserves. Sometimes errors in classification inflate your mod unfairly, and correcting them saves thousands annually.

Separate your shop payroll from clerical work when reporting to your carrier, because mixing classifications artificially spikes your rates. A shop with three technicians, two office staff, and one owner reporting everything under one classification pays significantly more than a shop that properly separates $150,000 in shop payroll from $80,000 in clerical payroll.

Service Types Create Different Risk Profiles

The services you offer create vastly different risk profiles and premiums. A shop that only performs routine maintenance like oil changes and tire rotations pays substantially less than a shop performing transmission rebuilds or welding. Road-testing vehicles adds major exposure-if your technicians test-drive customer cars regularly, your umbrella coverage should start at $2 million rather than $1 million. That upgrade costs roughly $300–$600 annually but protects you from catastrophic liability.

Body work and painting introduce solvent and chemical exposures that standard garages don’t face, justifying higher pollution liability premiums. Garagekeepers coverage also scales directly with the vehicles you handle: a shop servicing mostly used Honda Civics and Toyota Corollas faces lower exposure than a shop handling luxury vehicles or exotic cars.

Location and Vehicle Value Shape Your Exposure

Calculate your garagekeepers limit by multiplying your peak on-site vehicle count by average vehicle value, then add 25% as a safety margin. If you typically have 15 vehicles averaging $35,000 each, you need roughly $650,000 in coverage, not the $2,500 default limit most policies offer. Your location matters significantly because state regulations, local labor costs, and litigation patterns all affect premiums. Indiana shops pay different rates than California shops, and urban locations typically cost more than rural areas due to higher medical costs and settlement values.

Claims History Determines Your Options

Your claims history over the past three years directly influences what carriers will quote and at what price. A shop with zero claims in three years qualifies for better rates and may access carriers that avoid shops with frequent small claims. Conversely, a shop with three claims in two years faces limited carrier options and higher premiums across all coverages. This is why loss prevention investments pay immediate dividends: reducing claims not only saves the direct cost of the claim but also lowers your baseline premium for years afterward, compounding the savings substantially.

Final Thoughts

Your auto shop garage insurance foundation rests on three essential coverage types working together: liability coverage protects you from customer injury claims, garagekeepers coverage protects the vehicles in your care from damage, and workers’ compensation protects your employees and your business from injury-related financial collapse. The specific limits you choose for each coverage type matter far more than the coverage names themselves-a $2,500 garagekeepers limit sounds reasonable until a customer’s $40,000 vehicle gets damaged in your bay and you’re writing a check for $37,500 out of pocket. Equipment breakdown and inland marine coverage round out your protection by safeguarding the tools and diagnostic equipment that keep your shop running.

We at Briggs Agency, Inc. represent multiple top-rated carriers, which means we compare options across different insurers rather than steering you toward one company’s standard package. Our experienced local agents in Crown Point, Indiana have served businesses since 1946, and we’ve seen firsthand how the right auto shop garage insurance tailored to your specific operation saves money while protecting what you’ve built. We’ll review your claims history, calculate your actual vehicle exposure, and identify gaps in your current coverage that could blindside you later.

Contact Briggs Agency, Inc. for a policy review and bring your current declarations page along with a list of the services you offer, the number of vehicles you typically have on-site, and your employee count. We’ll compare your current limits against your actual exposure, identify any coverage gaps, and show you what competitive rates look like from carriers that specialize in auto shop protection. The conversation takes 15 minutes and could save you thousands annually while closing the gaps that keep shop owners awake at night.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Truck Insurance for Fleets: Streamlined Coverage for Carriers

Running a fleet means managing multiple risks at once. Truck insurance for fleets is designed to handle that complexity with streamlined coverage that protects your entire operation.

At Briggs Agency, Inc., we work with carriers who need practical solutions, not generic policies. This guide walks you through what fleet coverage actually includes, how to reduce costs, and how to find the right provider for your business.

What Fleet Coverage Actually Protects

Consolidating Multiple Vehicles Into One Policy

Fleet truck insurance consolidates multiple vehicles under one policy, which fundamentally changes how you manage risk and cost. Instead of maintaining separate policies for each truck, a fleet policy typically covers five or more vehicles with unified liability, physical damage, cargo, and uninsured motorist protections. The Federal Motor Carrier Safety Administration requires interstate carriers to maintain minimum liability coverage depending on freight type, and a consolidated fleet policy makes it far simpler to stay compliant across your entire operation. Consolidation eliminates duplicate administrative overhead-one renewal date, one billing cycle, one point of contact for claims-rather than juggling multiple insurers and renewal notices throughout the year.

Diagram showing how consolidating vehicles under one fleet policy streamlines compliance, admin, coverage, scaling, and claims. - Truck insurance for fleets

This structure also allows you to add or remove vehicles and drivers without starting from scratch, which matters significantly when you scale operations or respond to seasonal demand fluctuations.

Customization and Cost Efficiency

The real advantage over individual truck policies lies in customization and cost efficiency. A fleet policy adjusts to your specific risk profile: the types of cargo you haul, the routes your drivers operate, their safety records, and your equipment mix. Telematics integration has become standard at leading carriers, allowing real-time monitoring of driver behavior and vehicle performance, which directly reduces premiums when data proves safe operation. Physical damage coverage protects against collision, theft, fire, and natural disasters, while motor truck cargo insurance guards freight during transit-critical for temperature-controlled loads where spoilage claims spike quickly.

Coverage Layers That Protect Your Operation

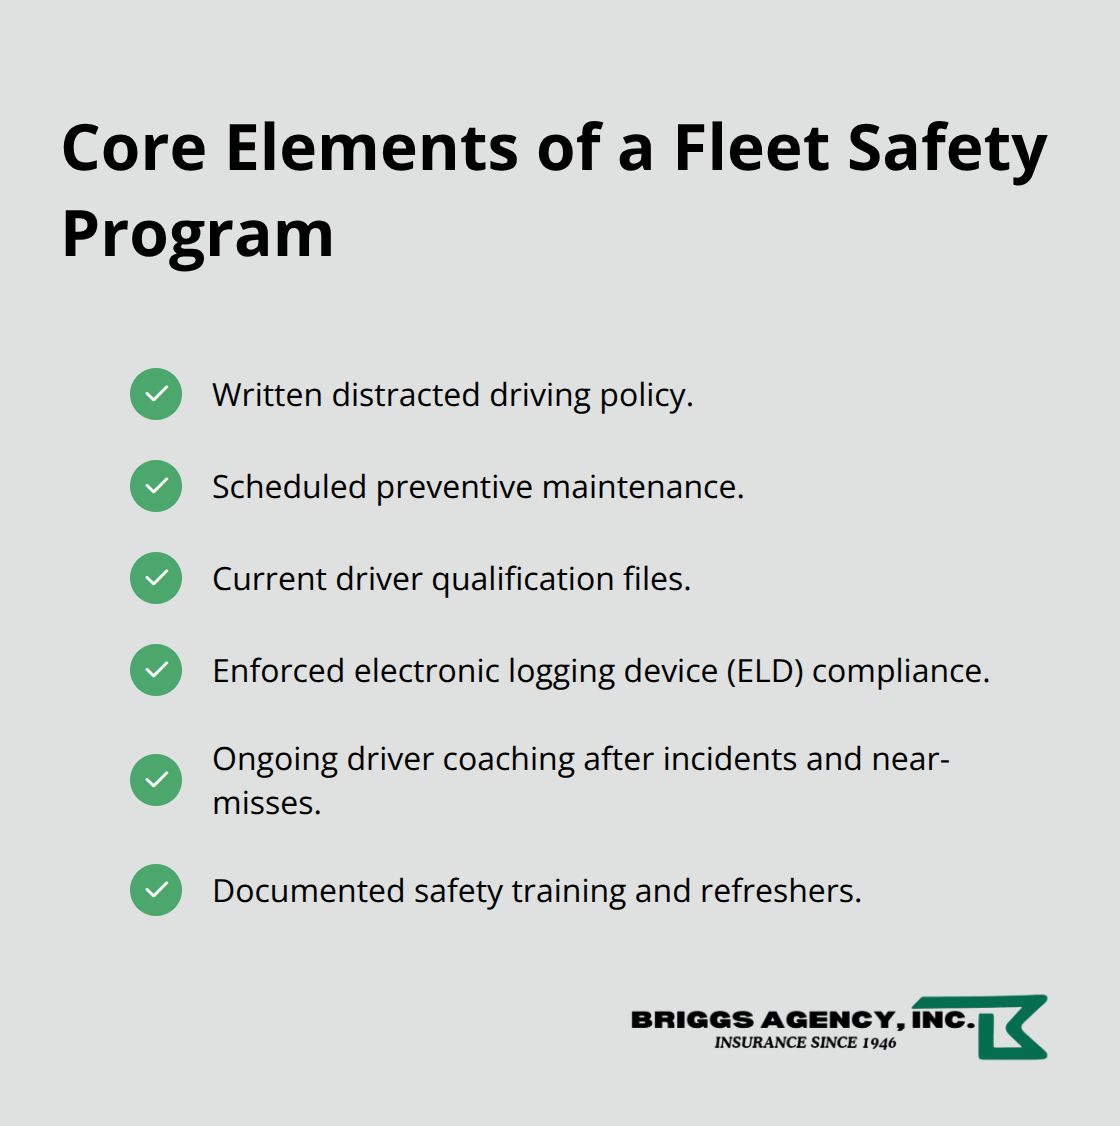
General liability covers non-vehicular incidents like loading injuries, and uninsured motorist protection safeguards you when other drivers lack adequate coverage. The FMCSA’s enforcement focus on electronic logging device compliance and cargo securement means your insurer must understand these regulatory trends, not just quote standard limits. Fleets that implement formal safety programs, maintain current driver qualifications, and enforce distracted driving policies consistently see premium reductions because underwriters recognize lower risk.

Finding Coverage That Matches Your Operation

Your insurer should structure coverage that matches your operation, protecting you where it matters most without unnecessary layers. The right provider understands your specific fleet composition, cargo types, and operational challenges-and that local expertise makes a real difference when claims arise or regulations shift.

How to Cut Fleet Insurance Costs Without Cutting Corners

Establish a Safety Program That Insurers Recognize

Reducing fleet insurance premiums doesn’t mean accepting weaker coverage. The most effective approach is demonstrating to your insurer that your operation runs safely and efficiently. A formal safety program is the fastest way to prove this. Carriers that establish written policies on distracted driving, require regular vehicle maintenance, and maintain current driver qualifications see measurable premium reductions. The Federal Motor Carrier Safety Administration’s focus on electronic logging device compliance means insurers now expect fleets to enforce these standards automatically.

Checklist of safety program components that help reduce fleet insurance premiums. - Truck insurance for fleets

Use Telematics Data to Lower Risk Perception

Telematics data has become the primary language insurers speak when evaluating risk. Real-time monitoring systems track harsh braking, speeding, and unsafe lane changes, giving underwriters concrete evidence of safe operation. When your data shows lower-risk driving patterns, insurers adjust premiums downward because you’ve eliminated guesswork. Dash cameras provide additional leverage by documenting driver behavior and reducing dispute costs when claims occur. Fleets using dash cams typically see claim costs drop because video evidence resolves liability questions faster and often prevents fraudulent claims entirely. These systems are no longer optional if you want competitive pricing.

Manage Claims Strategically to Protect Your Renewal Rate

Claims management strategy matters equally. Every incident that reaches your insurer increases your loss history and signals higher risk at renewal time. Preventing small claims from becoming large ones requires immediate vehicle maintenance, rapid repair turnarounds, and driver coaching after near-misses. A single preventable collision can raise your renewal premium by thousands of dollars across your entire fleet, so investing in preventive maintenance and driver training pays back quickly.

Leverage Regulatory Transparency to Your Advantage

The FMCSA’s Motus platform rollout is streamlining compliance filings, which means your insurer can access your safety record more easily. This shift toward data transparency rewards fleets that maintain clean records. Your insurer can now verify your compliance status directly, making documentation of safety practices even more valuable at renewal time.

Partner With an Agent Who Understands Your Specific Operation

Local agents who know your operation can identify which add-ons actually reduce your overall cost and which are unnecessary. They understand your specific cargo types, routes, and driver profiles in ways that national carriers cannot. The combination of documented safety practices, telematics integration, and a claims-conscious culture creates the conditions for sustained premium reductions year after year. With this foundation in place, the next step is selecting an insurer and agent who can translate these efforts into real savings.

Choosing the Right Fleet Insurer for Your Operation

Identify Carriers With Genuine Trucking Expertise

Selecting a fleet insurer requires looking past premium quotes and examining what actually happens when you file a claim or need coverage adjusted mid-term. Start by identifying carriers with genuine trucking expertise, not just commercial auto programs adapted for fleets. Insurers like Northland Insurance, which has served owner-operators and fleets since 1948, understand the operational realities you face-seasonal demand swings, regulatory compliance pressure, and the cost of downtime. When comparing carriers, ask specifically about their claims processing speed and whether they allow vehicle changes without rewriting your entire policy. A carrier that processes claims in days rather than weeks directly reduces your operational losses.

Evaluate Telematics Integration and Performance Discounts

Request information on their telematics integration options and whether they offer performance-based discounts tied to real driving data. Most competitive carriers now integrate with platforms that feed directly into your fleet management system, eliminating manual reporting. Verify their understanding of your specific cargo types-a carrier experienced with temperature-controlled reefer operations understands spoilage risk differently than one focused on dry van hauling. Ask whether they provide Certificates of Insurance quickly, since delays can cost you contracts. The Federal Motor Carrier Safety Administration’s minimum liability requirements vary depending on your entity type and operating structure, so confirm the carrier can structure limits that satisfy both federal requirements and your customer contracts without overinsuring unnecessarily.

Prepare Detailed Information for Accurate Quotes

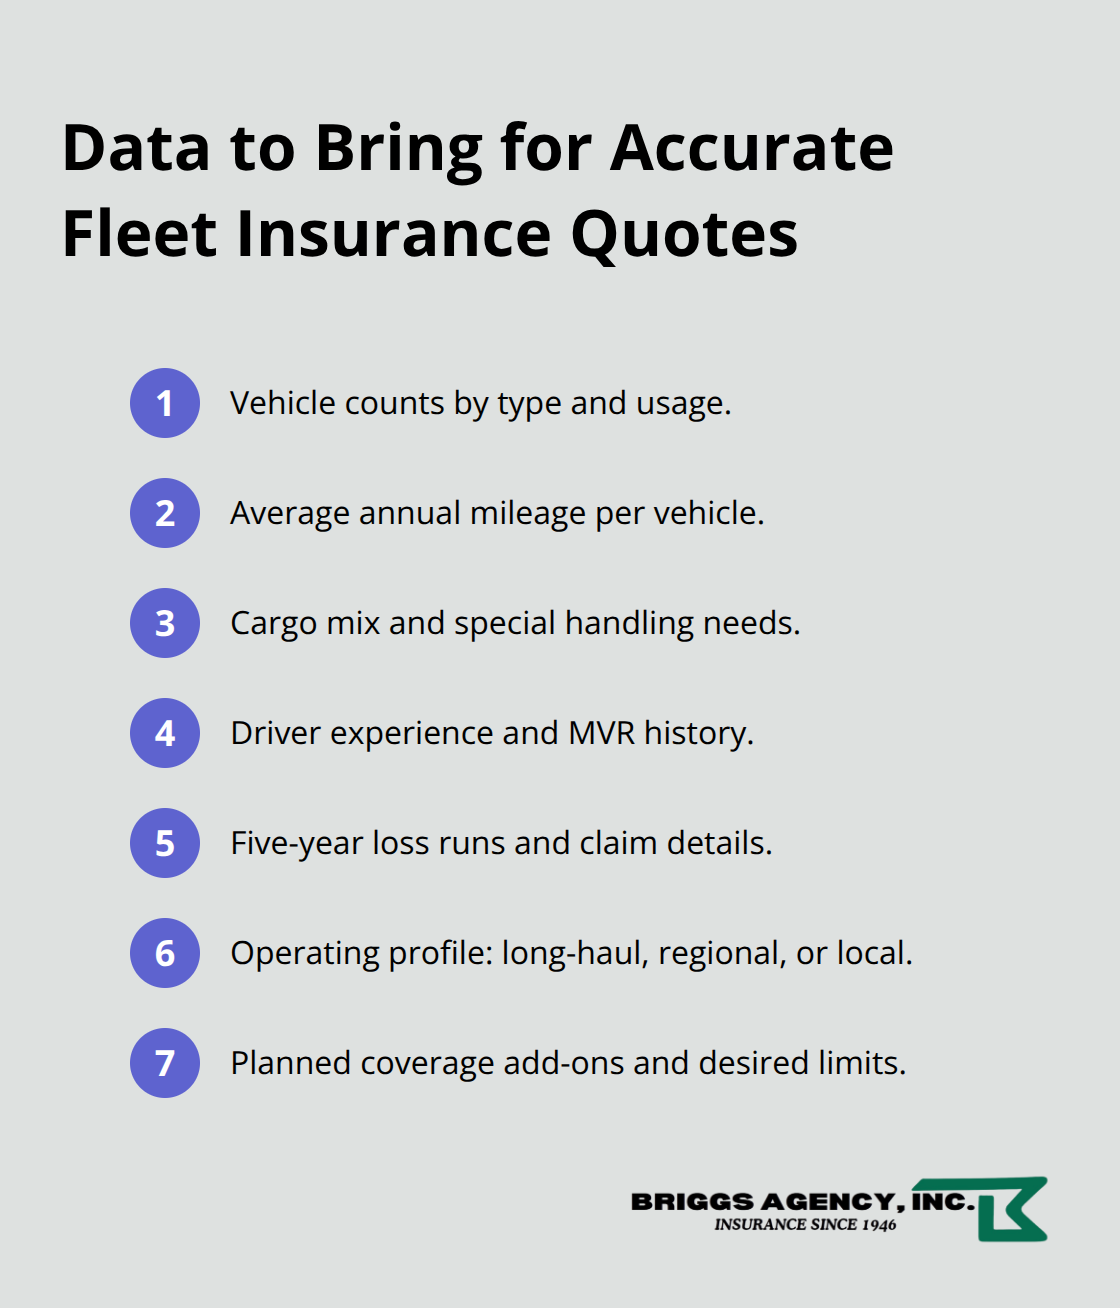
Local agents make a measurable difference because they understand your specific routes, driver profiles, and seasonal patterns in ways national carriers cannot replicate. When requesting quotes, come prepared with vehicle counts, average annual mileage, cargo mix, driver experience levels, and your loss history. Carriers price fleets differently based on whether you run long-haul interstate, regional, or local delivery operations, so specificity matters. Compare not just base premiums but also what add-ons cost-higher liability limits, cargo coverage enhancements, and uninsured motorist protection typically have separate pricing.

Compact list of the key data points insurers need to price fleet coverage accurately.

Assess Loss Control Resources and Policy Flexibility

Ask each carrier about their loss control resources and driver coaching programs, since these directly influence your renewal rates. A carrier offering formal safety program resources and telematics-backed coaching creates long-term savings you won’t see reflected in year-one quotes. Request sample policy language showing how they handle non-trucking liability coverage, since gaps between dispatch and personal use have caused costly disputes. Finally, check whether the insurer allows mid-term adjustments without penalty when you add vehicles or modify operations, since rigid policies force you to overpay or stay underinsured during growth periods.

Final Thoughts

Fleet truck insurance for carriers protects far more than vehicles-it safeguards your drivers when accidents happen, covers cargo losses that could otherwise devastate cash flow, and shields you from liability claims that threaten your operating authority. Consolidating coverage under a single fleet policy eliminates administrative chaos while telematics, formal safety programs, and clean claims records compound savings year after year. An insurer with genuine trucking expertise processes claims quickly, allows mid-term adjustments, and offers performance-based discounts that transform insurance from a compliance burden into a strategic asset.

The path forward requires gathering your fleet details-vehicle counts, cargo types, routes, and driver experience-then requesting quotes from carriers with proven trucking expertise. Work with an agent who understands your specific operation rather than applying generic solutions, since local knowledge identifies which add-ons actually reduce your overall cost. Fleets that invest in the right coverage and risk management practices recover faster from incidents, maintain better renewal rates, and operate with confidence that their protection matches their actual exposure.

At Briggs Agency, Inc., we’ve served businesses in Crown Point and beyond since 1946, and we understand what it takes to protect fleets that keep our community moving. Contact us today to discuss truck insurance for fleets tailored to your operation and receive competitive quotes from multiple carriers.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Restaurant Insurance Guidance: Clear Steps to Smarter Protection

Running a restaurant means managing dozens of moving parts, and insurance is one area where a single oversight can cost you thousands. Most restaurant owners discover too late that standard business policies don’t cover the specific risks they face daily.

At Briggs Agency, Inc., we’ve helped countless restaurant owners find the right coverage. This restaurant insurance guidance walks you through the essential protections your business needs and how to choose a partner who actually understands your operation.

What Makes Restaurant Risks Different from Other Businesses

The Convergence of Liability, Property, and Employee Safety

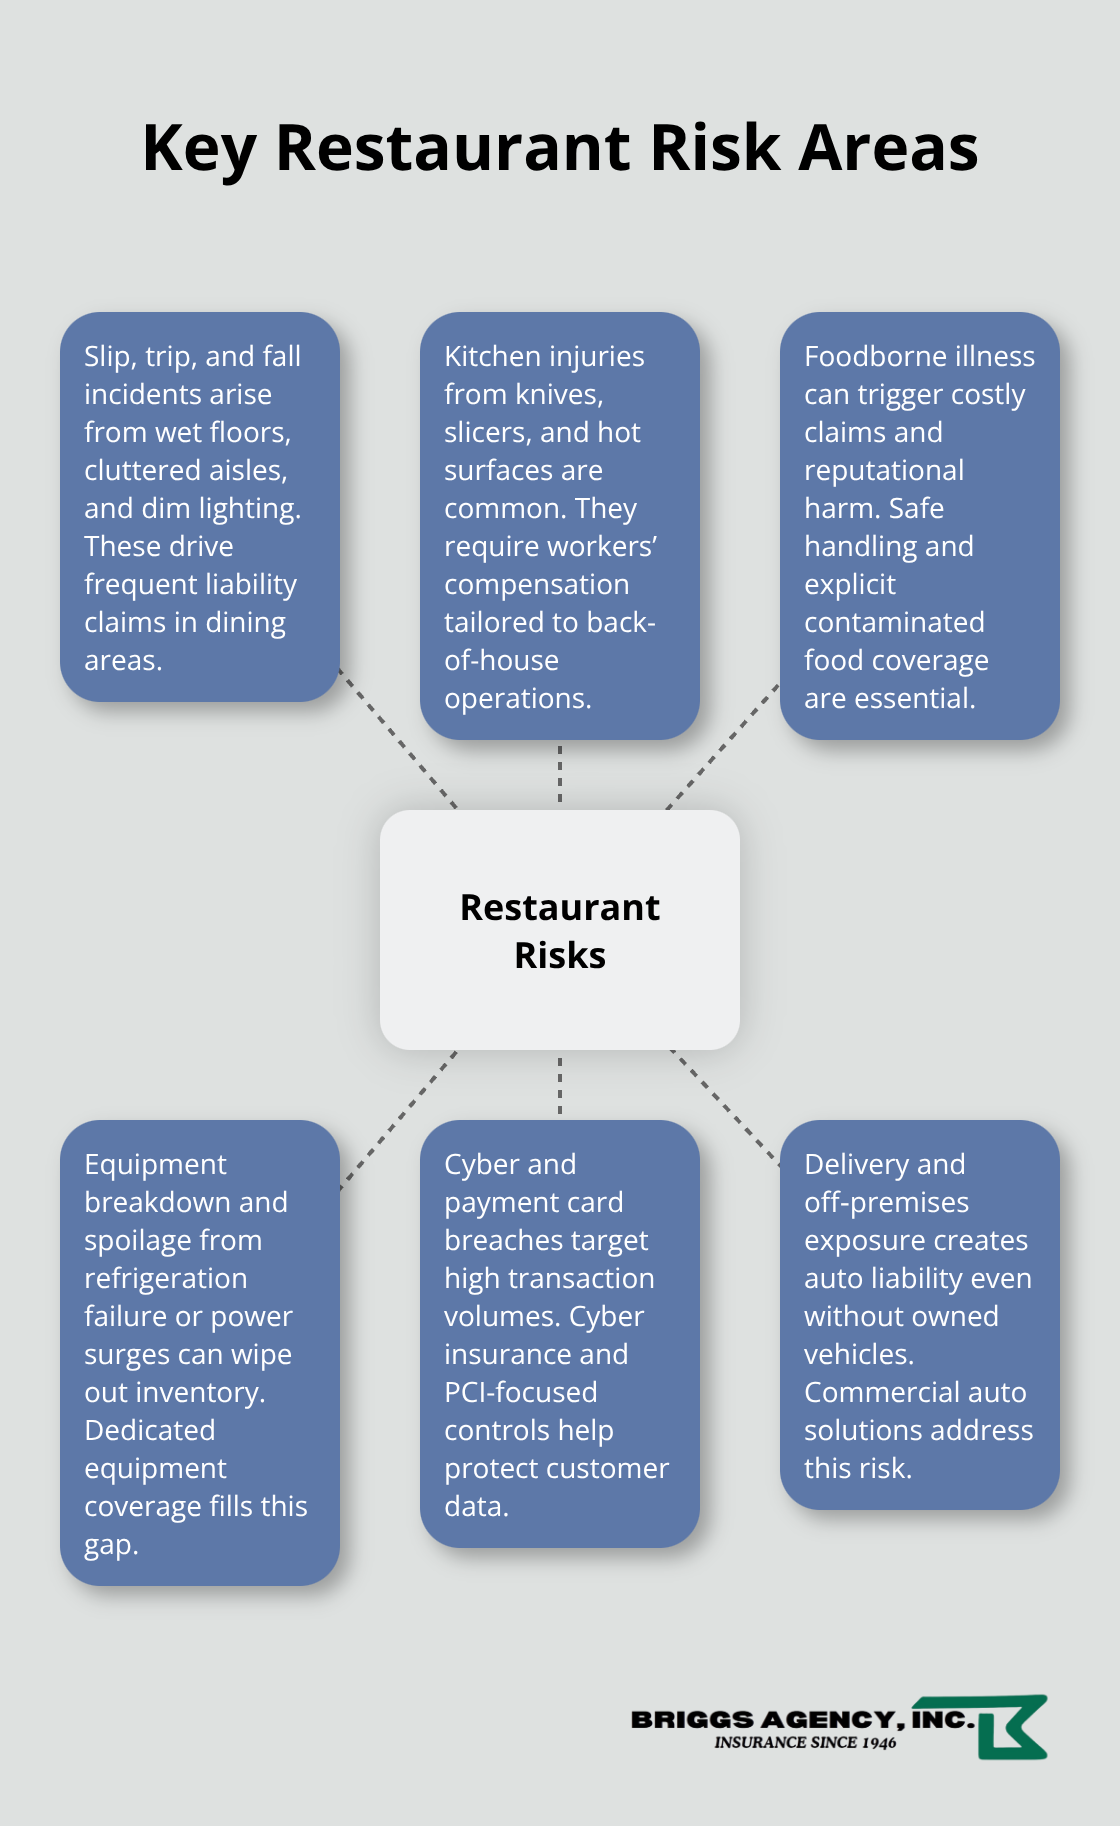
Restaurants operate in an environment where liability, property damage, and employee injuries converge constantly. A slip on a wet floor in the dining room, a knife injury in the kitchen, a refrigerator failure that spoils inventory, or a customer’s foodborne illness claims can each cost thousands to defend or settle. The CDC reports that the average number of U.S. foodborne illnesses is 9.9 million annually, making food safety a serious liability exposure. Standard commercial policies treat restaurants like any other retail business, which means they miss the specific hazards that define food service operations. A general business policy might cover a slip-and-fall at a clothing store, but it won’t address the unique combination of kitchen equipment risks, food handling liability, and alcohol service exposure that restaurants face daily.

Why Generic Policies Leave You Exposed

When we at Briggs Agency, Inc. review restaurant owners’ existing policies, we regularly find gaps that leave them exposed to tens of thousands in uninsured losses. Most restaurant claims span multiple coverage types that generic policies simply don’t bundle together. Front-of-house slip, trip, and fall incidents drive significant claims due to wet floors, cluttered aisles, and dim lighting-these account for more losses than most owners anticipate. Back-of-house injuries from knives, slicers, and hot surfaces are equally frequent and often more severe, requiring workers’ compensation coverage specifically tailored to kitchen environments.

Kitchen-Specific Hazards and Equipment Risks

Kitchen fires and smoke damage stem from grease buildup and unserviced hoods; the National Fire Protection Association requires hood and duct cleaning on schedules that most restaurants don’t follow, creating a documented risk gap. Foodborne illness claims require coverage that explicitly addresses contaminated food or water liability, which many standard policies exclude or limit severely. Equipment breakdown and spoilage from refrigeration failures, power surges, or outages can wipe out inventory overnight, yet general liability policies don’t cover this loss.

Digital and Off-Premises Exposures

Cyber and payment card breaches target restaurants with high transaction volumes; the Verizon Data Breach Investigations Report 2025 confirms that payment systems remain a top breach vector, making cyber insurance essential for operations that store customer data. Delivery and off-premises exposure exists even if you don’t own vehicles, since third-party drivers or employee deliveries trigger auto liability needs that personal auto policies won’t cover. Property damage from weather, water, and sewer backups requires specific endorsements that aren’t standard in basic commercial packages.

Infographic showing core risk categories restaurants face in the United States - Restaurant insurance guidance

Building the Right Coverage Foundation

A Business Owners Policy bundles liability and property coverage and serves as the most cost-effective baseline for small to mid-sized restaurants. However, you must customize it with liquor liability, workers’ compensation, and cyber protection to address the full spectrum of food service risks. Understanding which coverages work together-and which gaps remain in standard packages-positions you to make informed decisions about your restaurant’s protection.

What Coverage Your Restaurant Actually Needs

Foundation Coverages: Liability and Property

General liability covers the slip-and-fall incidents and foodborne illness claims that define restaurant exposure, but it forms only the foundation. When a customer slips on a wet floor or claims food poisoning, general liability defends you and covers medical expenses and settlements up to your policy limit. However, general liability alone won’t protect your building, kitchen equipment, or inventory from fire, equipment failure, or weather damage. Property insurance fills that gap by covering your physical assets, including the structure itself, refrigeration units, cooking equipment, and perishable inventory. Restaurants lose $50,000 or more in spoiled inventory from a single refrigeration failure when owners assume general liability covered equipment breakdown-it doesn’t. A Business Owners Policy bundles general liability and property coverage at a lower cost than buying them separately, making it the practical starting point for most restaurants.

Property Coverage and Building Protection

If you own your building, property coverage becomes non-negotiable; if you rent, your landlord’s policy protects the structure, but your contents and equipment still need dedicated coverage. Property insurance protects both the physical structure and the equipment inside it, addressing losses that general liability explicitly excludes. This distinction matters enormously when a kitchen fire or water damage strikes-your general liability policy won’t cover the damage to your own building or equipment, leaving you exposed to tens of thousands in uninsured losses.

Checklist of essential restaurant insurance coverages for U.S. restaurants - Restaurant insurance guidance

Workers’ Compensation and Employee Protection

Workers’ compensation is legally required in most states and covers medical expenses, lost wages, disability benefits, and rehabilitation costs when employees get injured. Kitchen injuries from knives, slicers, and hot surfaces happen frequently, and workers’ compensation protects both your staff and your business from devastating wage claims. Many states require coverage if you have even one employee, so verify your state’s threshold immediately-Missouri requires five or more employees, while New York requires coverage for any employees. Employment Practices Liability Insurance protects against wage-and-hour claims involving tips, overtime, and retaliation, which have increased significantly as the Department of Labor intensifies wage enforcement.

Alcohol Service and Specialized Liability

If you serve alcohol, liquor liability is non-negotiable because standard general liability explicitly excludes alcohol-related claims. Dram shop laws in most states hold establishments liable when intoxicated patrons injure themselves or others, and liquor liability covers these exposures that can reach six figures in a single incident. Server training programs like TIPS reduce your risk measurably and often qualify you for premium discounts. Cyber insurance protects customer payment data and personal information stored in your POS system, which restaurants with high card volumes absolutely need. 48% of all breaches now involve ransomware, and a single breach notification can cost $10,000 to $50,000 before settlement expenses.

Commercial Auto and Delivery Operations

Commercial auto coverage applies if you deliver food or operate catering services, since personal auto policies explicitly exclude business use and leave you uninsured and liable. These coverages work together to address the specific risks restaurants face, but coverage gaps remain if you don’t intentionally customize them. A standard BOP covers general liability and property, but it won’t address liquor exposure, cyber risk, or delivery vehicle liability unless you add them. Bundling coverages under one policy typically saves 7 percent on auto and 3 percent on renters or condo coverage in many states, making the combined approach more affordable than buying pieces separately. Your restaurant’s specific operation determines which coverages you actually need-a small deli has different exposures than a full-service restaurant with a bar and delivery service.

Percentages showing ransomware share of breaches and typical bundling savings

State requirements vary significantly, so you must verify which coverages your state mandates for licenses or contracts before assuming you’re protected. Getting coverage started online with a quote or through an agent takes less than an hour, and working with an independent agent who asks detailed questions about your specific operations ensures you don’t overpay for coverage you don’t need or underpay and discover gaps when it’s too late. The next step involves evaluating which insurers and agents truly understand restaurant operations and can guide you toward the right combination of protections for your specific business model.

Finding an Insurance Partner Who Understands Your Restaurant

What to Look for in an Insurance Agent

Choosing an insurance provider for your restaurant means finding someone who understands the specific operational complexities you face daily, not someone who treats your business like a retail store or office building. Many restaurant owners shop solely on price, then discover mid-claim that their policy has massive gaps because the agent never asked about their kitchen setup, delivery operations, or alcohol service model. The right partner asks detailed questions about your menu, your staffing structure, whether you handle cash tips or digital payments, if you own or rent your space, and whether you plan to add catering or delivery down the road. These details matter enormously because they determine which coverages you actually need and which ones you can skip without creating exposures.

Independent Agents vs. Captive Representatives

An independent agent represents multiple carriers and can compare options across different insurers, whereas captive agents work for one company and have limited flexibility to find the best fit for your specific situation. When you request quotes, insist that agents explain why they recommend certain coverage limits and what specific risks those limits address in your restaurant. A quote that simply lists coverage types without connecting them to your actual operations is a red flag that the agent hasn’t truly evaluated your business. An agent who understands restaurants can articulate common losses in food service operations and explain how their recommendations address your unique exposures.

Evaluating Quotes and Coverage Details

Request quotes from at least two or three providers, and when comparing them, examine the deductibles, coverage limits, and what each policy actually excludes-not just the premium. A cheaper policy with high deductibles and low limits often costs more in the long run when a claim hits and you discover you’re underinsured. Ask each agent directly how they handle claims and whether they offer risk-control resources like food safety training, equipment maintenance checklists, or slip-and-fall prevention guidance that can reduce your losses and qualify you for premium discounts. The best way to evaluate potential partners is to prepare for your insurance agent meeting by gathering information about restaurants they’ve insured in your area and what claims those restaurants faced.

Building an Ongoing Partnership

The conversation with your chosen agent should happen annually, not just at renewal, because your restaurant changes as you add menu items, staff, or services, and your insurance should evolve with those changes. An agent who understands your operation asks probing questions about your specific risks rather than applying a standard package to every restaurant client. At Briggs Agency, Inc., we represent multiple top-rated carriers, which allows our experienced local agents to compare options and tailor policies to deliver competitive pricing and the right protection for your restaurant’s specific needs. Your agent should explain coverage gaps clearly and help you understand which endorsements or additional policies fill those gaps without overpaying for protection you don’t need.

Final Thoughts

Restaurant insurance protection rests on three core principles: understanding your specific exposures, selecting coverages that work together, and updating your policies as your business evolves. The slip-and-fall in your dining room, the knife injury in your kitchen, the refrigeration failure that spoils inventory, and the foodborne illness claim from a customer represent real financial threats that generic business policies simply don’t address. A Business Owners Policy bundled with liquor liability, workers’ compensation, cyber coverage, and commercial auto protection creates a foundation that matches the risks you face daily.

Getting started with restaurant insurance guidance means scheduling a conversation with an agent who asks specific questions about your operation rather than applying a standard package to every restaurant client. Your agent should understand whether you own or rent your space, how you handle payments, if you serve alcohol, and whether you operate delivery services, because these details determine which coverages you genuinely need. Request quotes from multiple providers and compare the deductibles, coverage limits, and exclusions rather than focusing solely on price, since a cheaper policy with gaps often costs far more when a claim arrives.

Your restaurant changes as you add staff, expand your menu, or introduce new services like catering or delivery, and your insurance must evolve with those changes. At Briggs Agency, Inc., our experienced local agents represent multiple top-rated carriers, which means we compare options and tailor policies to deliver competitive pricing and the right protection for your restaurant’s specific needs. The investment in proper restaurant insurance protection today prevents the financial devastation that comes from discovering gaps when it’s too late.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.