Why Safety Programs Can Lower Insurance Costs

Why Safety Programs Can Lower Insurance Costs

Introduction

For businesses of all sizes, insurance is an important part of protecting employees, property, and operations. However, insurance costs can become a significant business expense, especially when a company has a history of workplace accidents or insurance claims. One effective way businesses can manage these risks is by developing and maintaining a strong safety program.

A safety program does more than help prevent workplace injuries. It can also reduce the number and severity of accidents, limit insurance claims, and demonstrate to insurers that a company is taking proactive steps to manage risk. Over time, these efforts may contribute to more favorable insurance costs and a healthier bottom line.

 A Safer Workplace Could Mean Lower Costs

What if improving workplace safety could do more than protect your employees—it could also help control your insurance expenses?

Every workplace accident has the potential to create costs through medical expenses, lost productivity, property damage, workers’ compensation claims, and higher insurance premiums. The good news is that many of these risks can be reduced through proactive safety measures.

In this post, we’ll explore how safety programs can help lower insurance costs, why insurers care about risk management, and what businesses can do to build a more effective safety program.

How Safety Programs Reduce Workplace Accidents

The primary purpose of a safety program is to prevent accidents and injuries before they occur. Businesses can accomplish this through employee training, regular workplace inspections, equipment maintenance, hazard identification, and clearly defined safety procedures.

When employees understand potential hazards and know how to work safely, the likelihood of accidents can decrease. Fewer accidents can mean fewer insurance claims, which may help a business improve its loss history over time.

For example, regularly training employees on proper lifting techniques can help reduce the risk of back injuries. Likewise, routine equipment inspections can identify mechanical problems before they result in an accident.

Fewer Claims Can Help Control Insurance Costs

Insurance companies evaluate risk when determining coverage and pricing. A business with frequent or costly claims may be viewed as a greater risk than a business with a strong claims history.

A well-managed safety program can help reduce the frequency and severity of claims. While implementing a safety program does not guarantee lower premiums, reducing losses can put a business in a better position when its insurance coverage is reviewed.

This is especially important for businesses that operate in industries where workplace injuries, property damage, or other risks are more common.

Employee Training Is a Key Part of Safety

A safety policy is only effective if employees understand it and follow it. That’s why ongoing employee training should be a central part of any safety program.

Training can cover topics such as:

  • Proper equipment operation

  • Workplace hazard awareness

  • Personal protective equipment

  • Emergency procedures

  • Safe lifting and material handling

  • Fire prevention

  • Vehicle and driver safety

  • Accident and incident reporting

Regular training helps employees recognize risks and understand what they can do to prevent accidents. It also reinforces the idea that workplace safety is an ongoing responsibility rather than a one-time requirement.

Regular Inspections Can Prevent Costly Problems

Small hazards can quickly become expensive problems if they are ignored. A damaged piece of equipment, wet floor, blocked emergency exit, or faulty electrical connection could potentially result in an injury, property damage, or a costly insurance claim.

Regular safety inspections allow businesses to identify and correct these hazards before they cause an accident.

Businesses should consider creating a schedule for routine inspections and documenting the problems they find and the steps taken to correct them. This creates accountability while helping the company track and improve its safety efforts.

A Strong Safety Culture Benefits the Entire Business

The benefits of workplace safety extend beyond insurance costs. A strong safety culture can improve employee morale, reduce downtime, increase productivity, and help businesses avoid the disruption that often follows workplace accidents.

When employees see that their employer takes safety seriously, they may also be more likely to report hazards and follow established procedures.

Ultimately, safety should not be viewed simply as a way to reduce insurance premiums. It should be considered an investment in the long-term success of the business.

How Businesses Can Strengthen Their Safety Programs

Businesses looking to improve their safety efforts can begin with several practical steps:

  • Identify common workplace hazards.

  • Establish clear written safety procedures.

  • Provide regular employee training.

  • Schedule routine equipment and workplace inspections.

  • Encourage employees to report hazards and near misses.

  • Investigate accidents to understand their causes.

  • Track workplace incidents and identify recurring trends.

  • Review and update safety procedures regularly.

Working with insurance and safety professionals can also help businesses identify areas where additional risk-management measures may be beneficial.

Conclusion

A strong safety program can be valuable for both employees and the business itself. By identifying hazards, training employees, maintaining equipment, and preventing accidents, businesses can reduce the likelihood of costly workplace incidents and insurance claims.

Although a safety program does not guarantee lower insurance premiums, a strong commitment to risk management can demonstrate that a business is taking meaningful steps to reduce its exposure to loss. Over time, fewer accidents and claims can contribute to a healthier claim’s history and potentially more manageable insurance costs.

The bottom line is simple investing in workplace safety isn’t just about preventing accidents—it’s about protecting your people, your business, and your bottom line.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski
Restaurant Loss Prevention: Reducing Risk In Food Service

Running a restaurant means juggling dozens of moving parts every single day. From food safety to employee management, the risks are real and costly if left unaddressed.

At Briggs Agency, Inc., we’ve seen firsthand how restaurant loss prevention directly impacts your bottom line. This guide walks you through the most common threats your business faces and the practical strategies that actually work.

What Puts Your Restaurant at Financial Risk

Foodborne Illness Outbreaks and Contamination

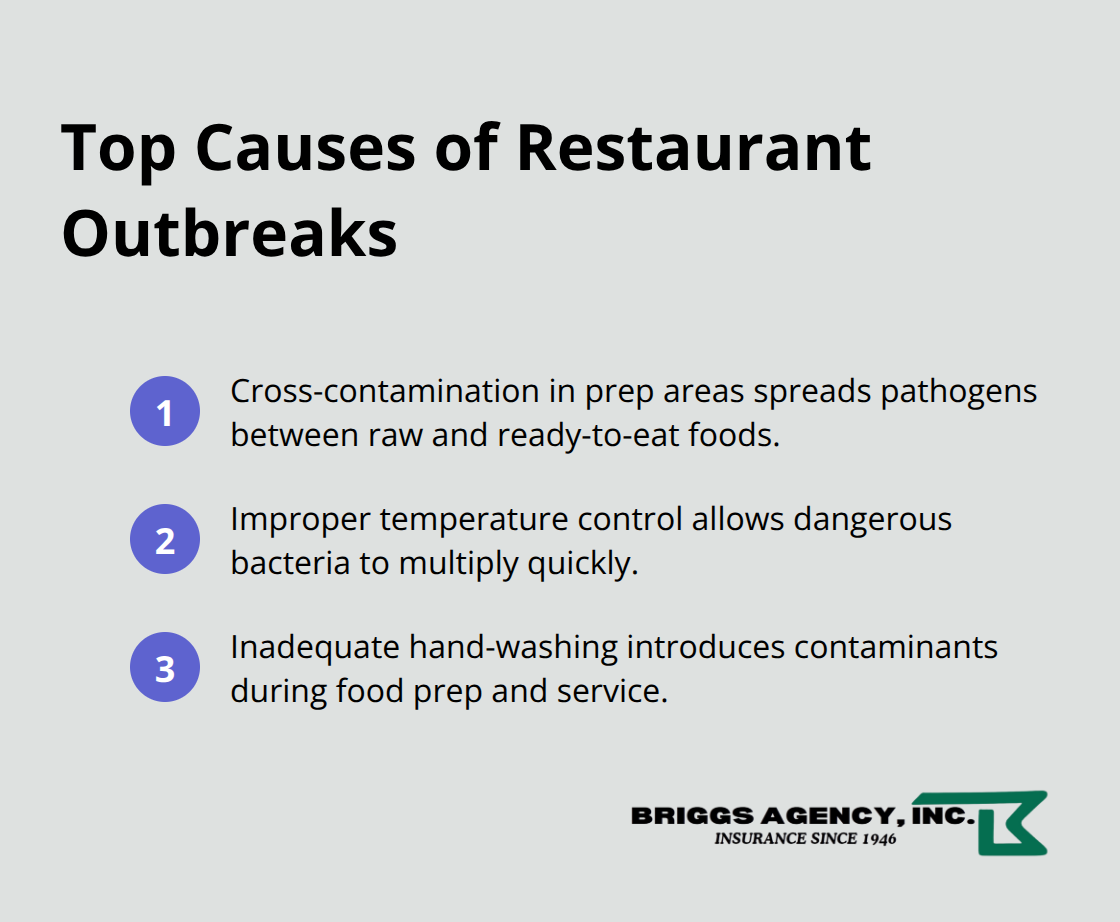
Foodborne illness outbreaks represent the most visible threat to restaurants, but the financial damage extends far beyond headlines. The CDC reports that foodborne illness costs the U.S. food industry approximately $15.5 billion annually in medical expenses and lost productivity. A single outbreak shuts down operations for weeks, destroys your reputation, and triggers lawsuits that drain resources for years. Cross-contamination in prep areas, improper temperature control, and inadequate hand-washing practices cause most outbreaks. Your staff needs hands-on training specific to your menu and equipment, not generic food safety videos watched once during onboarding.

Key causes of foodborne illness outbreaks in restaurants - restaurant loss prevention

Temperature logs demand daily checks, not weekly ones. Walk-in coolers fail without warning, and a thermometer on the wall won’t catch the problem until spoilage occurs. You need active monitoring systems that alert you to temperature fluctuations before food spoils.

Workplace Injuries and Safety Hazards

Workplace injuries cost restaurants an average of 42,000 dollars per incident when accounting for medical bills, workers’ compensation claims, and lost productivity, according to the National Safety Council. Slip-and-fall accidents dominate this category because kitchens are inherently wet and fast-paced environments where staff rush. Proper footwear requirements and non-slip flooring in high-traffic zones are non-negotiable, not nice-to-haves. Burns, cuts, and repetitive strain injuries follow close behind, often from inadequate training on equipment operation and ergonomics. Staff who understand proper lifting techniques and equipment safety reduce injury rates significantly.

Theft and Inventory Shrinkage

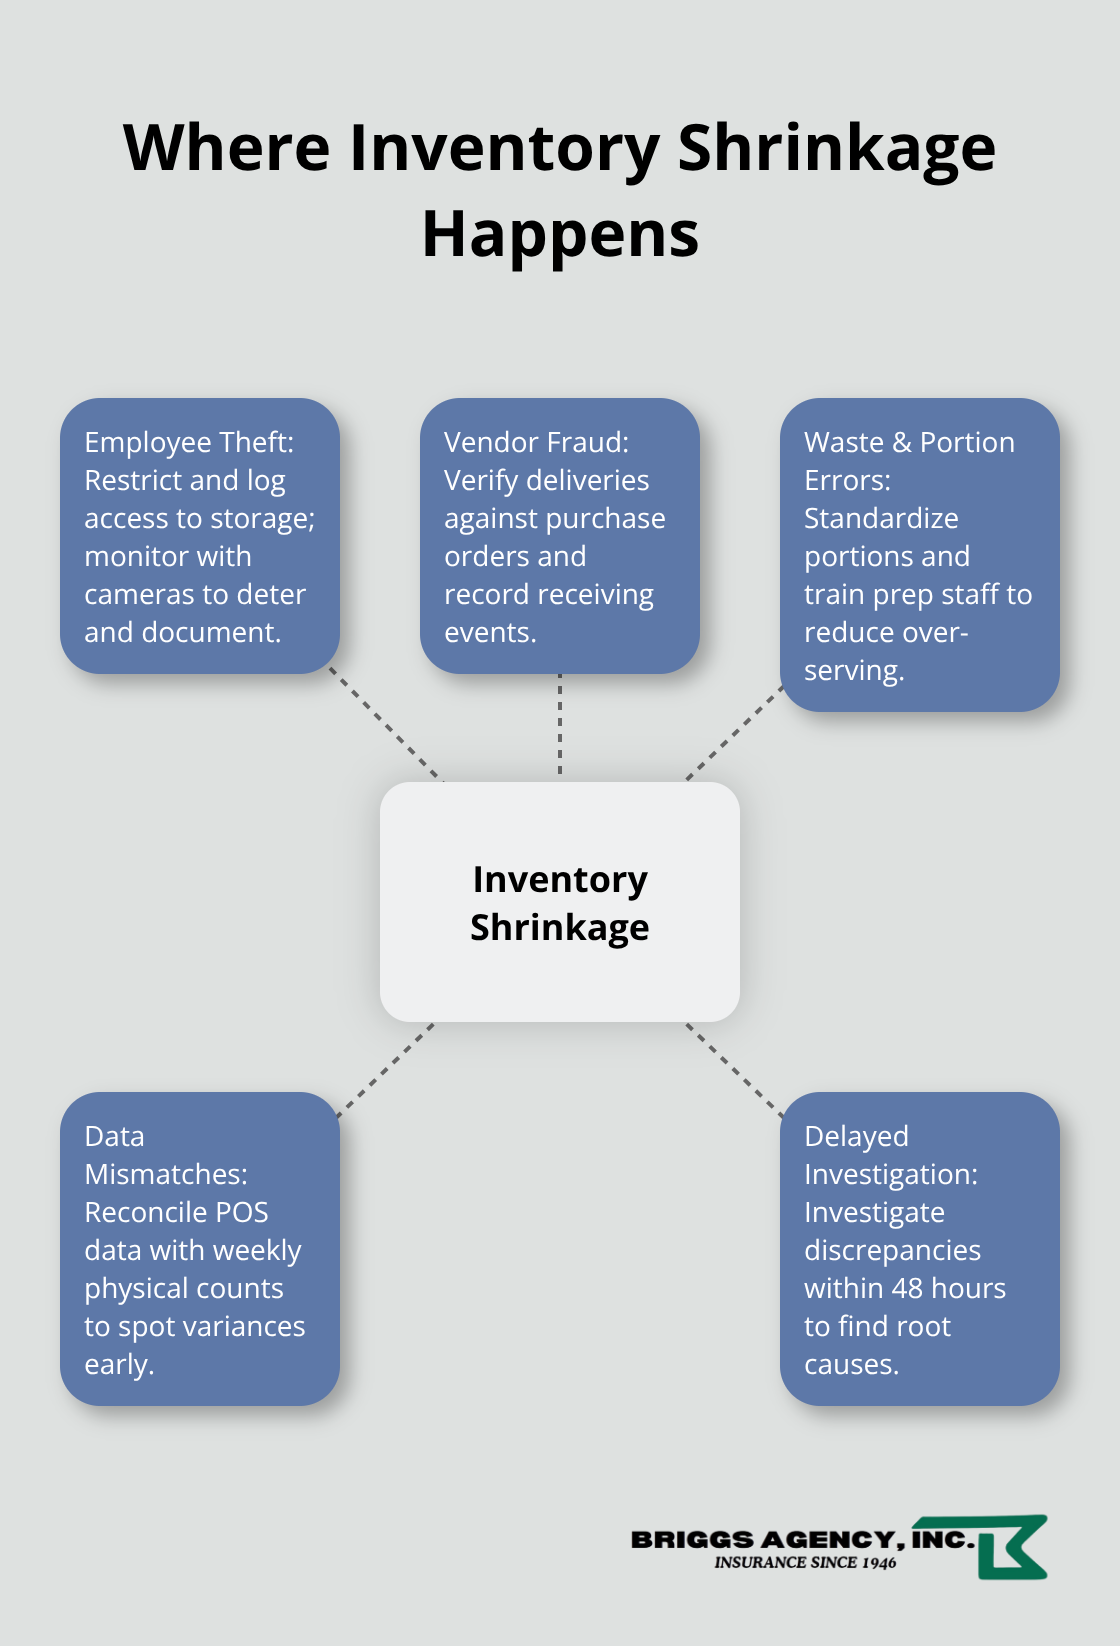
Theft and inventory shrinkage drain 2 to 4 percent of annual revenue for most restaurants, per the National Restaurant Association. This includes employee theft, vendor fraud, and simple waste from poor portion control. Without detailed inventory tracking against actual sales, you won’t know whether missing stock reflects theft, waste, or accounting errors. Point-of-sale data should match physical counts weekly, and discrepancies demand immediate investigation, not annual audits. Identifying where your money actually goes sets the foundation for the loss prevention strategies that follow.

Hub-and-spoke diagram showing common shrinkage sources and controls in restaurants

Loss Prevention Strategies That Work

Food Safety Training Tied to Your Operation

Food safety training works only when staff understand why temperature control matters to their paycheck and the restaurant’s survival, not because a poster says so. Implement a kitchen-specific training program tied directly to your menu and equipment, with quarterly refresher sessions that cover actual incidents from your operation. Staff who handle raw proteins need different knowledge than those working the fryer station.

Temperature monitoring should happen twice daily with written logs, and any reading below 41 degrees Fahrenheit or above 45 degrees Fahrenheit triggers immediate investigation and corrective action. A wireless temperature monitoring system that sends alerts to your phone works better than relying on wall thermometers checked during closing shift when energy runs low. Cross-contamination prevention requires color-coded cutting boards for different food types and separate hand-washing stations near prep areas, not a single sink shared with dishwashing. This costs under 500 dollars to implement but prevents outbreaks that cost tens of thousands.

Hazard Management and Workplace Safety

Workplace safety demands a written hazard management plan specific to your restaurant, not generic restaurant industry standards. Walk your kitchen with your safety-conscious staff member and identify every slip hazard, sharp edge, and burn risk, then document controls for each one. Non-slip flooring in high-traffic zones costs 2 to 8 dollars per square foot and prevents the slip-and-fall injuries that dominate restaurant claims.

Proper footwear policies stating no canvas shoes or sandals keep this control in place. Staff training on equipment operation and proper lifting techniques reduces injury rates significantly. These investments pay for themselves through lower workers’ compensation premiums and reduced downtime from injuries.

Inventory Controls and Theft Prevention

For theft and shrinkage, your point-of-sale system should generate daily inventory reports showing what sold versus what you recorded, with weekly physical counts of high-value items like spirits, seafood, and steaks. Staff access to storage areas must be restricted and logged, with cameras monitoring receiving and storage zones where most internal theft occurs. When discrepancies appear, investigate within 48 hours to identify whether the problem stems from waste, portion control errors, or employee theft, then address the root cause rather than assuming the worst about your team.

Implementing these strategies creates the foundation for sustainable loss prevention. The next section explores how technology amplifies these efforts and provides real-time visibility into your restaurant’s operations.

Technology and Tools for Restaurant Loss Prevention

Point-of-Sale Systems and Real-Time Data

Point-of-sale systems generate the data you need to catch problems before they become expensive. A modern POS tracks every item sold, when it sold, and which employee rang it up, then compares that against your physical inventory counts. When your system shows 40 steaks sold but physical count reveals only 35 steaks missing from inventory, you’ve identified a 5-steak discrepancy that demands investigation within 48 hours.

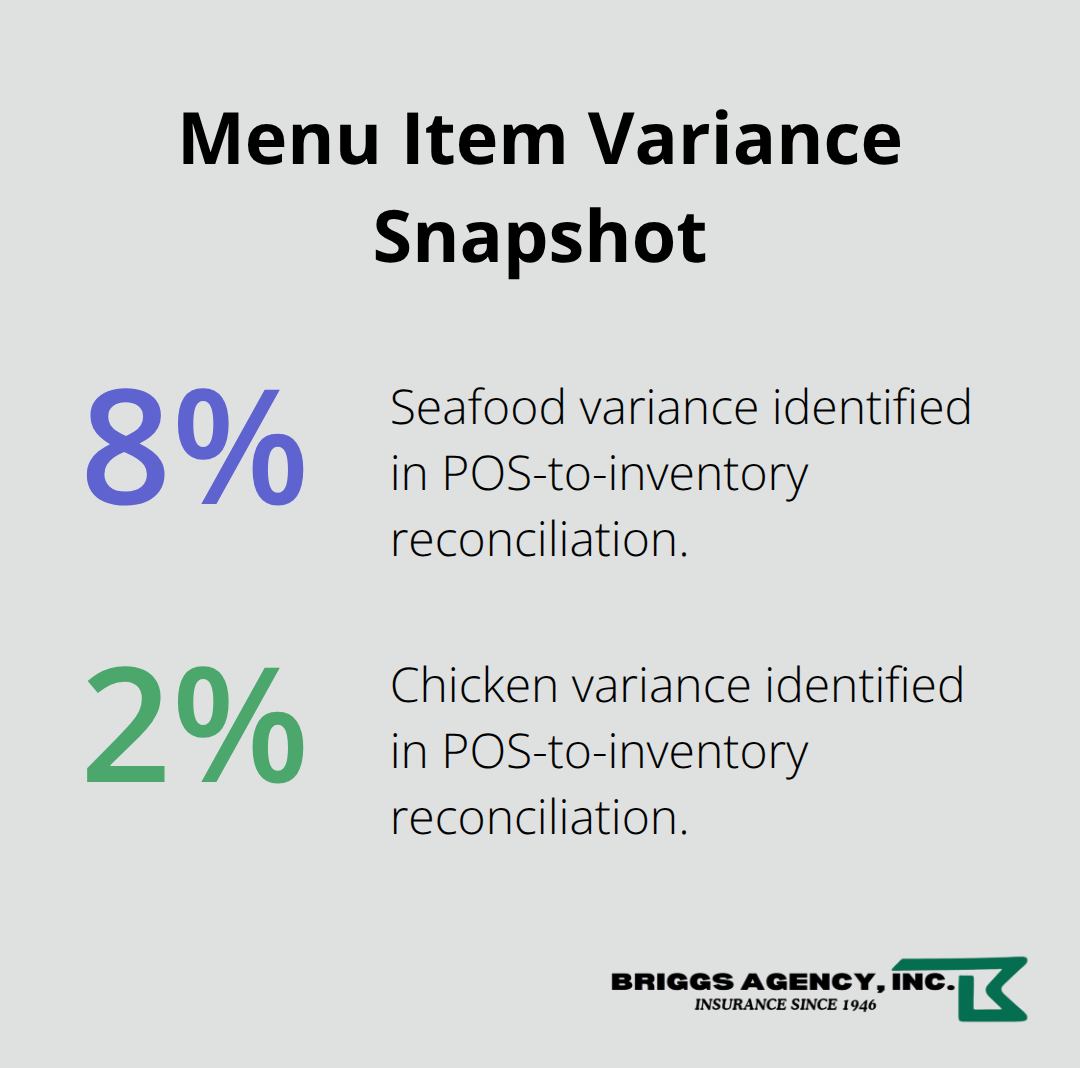
Systems like Toast and Square provide daily reconciliation reports showing variance percentages, and restaurants using daily reconciliation catch shrinkage faster than those relying on monthly audits. The data also reveals which menu items have the highest variance rates, pointing you toward specific training gaps or theft patterns. If your seafood consistently shows 8 percent variance while chicken shows 2 percent, your prep team needs targeted training on portion control for that category, not blanket accusations of theft.

POS variance example comparing seafood and chicken - restaurant loss prevention

Security Cameras and Strategic Monitoring

Security camera systems work best when positioned strategically rather than everywhere. Install cameras in receiving areas where vendor fraud happens, storage zones where employee theft concentrates, and cash handling stations where money disappears. High-resolution cameras recording at 30 frames per second cost between 400 and 800 dollars per unit installed, but they deter theft more effectively than any policy because staff know their actions are documented.

Cloud-based systems store footage for 30 to 90 days depending on your storage plan, and many allow remote viewing from your phone so you can monitor operations during days off. The visibility alone shifts staff behavior toward accountability without requiring constant oversight.

Employee Scheduling Software and Labor Cost Control

Employee scheduling software prevents losses by eliminating overstaffing during slow periods and reducing the scheduling errors that create overtime payouts. Systems like Deputy and ZipSchedule integrate with payroll to show labor cost as a percentage of sales in real time, revealing which shifts drain profitability. When you see that Tuesday lunch consistently runs at 32 percent labor cost while your target is 28 percent, you adjust staffing levels immediately rather than discovering the problem during monthly accounting reviews.

These tools also log who worked which shift and when, creating accountability that reduces time theft and scheduling manipulation. The combination of precise POS data, strategic camera placement, and integrated scheduling creates visibility across your operation, transforming loss prevention from reactive damage control into proactive cost management.

Final Thoughts

Restaurant loss prevention works best when you treat it as an ongoing system rather than a one-time fix. A single foodborne illness outbreak costs tens of thousands in medical claims and legal fees, one serious workplace injury raises your workers’ compensation premiums for years, and inventory shrinkage of 2 to 4 percent annually represents thousands of dollars walking out the door undetected. Start by conducting a risk assessment specific to your restaurant-walk your kitchen with your management team, review your POS data for shrinkage patterns, and identify which areas demand immediate attention.

Implement one major control at a time rather than overhauling everything simultaneously, and you’ll see measurable results within weeks. Temperature monitoring systems, non-slip flooring, and daily inventory reconciliation each address specific threats to your bottom line. Your insurance coverage forms the final layer of protection for risks you can’t prevent entirely (even the best loss prevention systems can’t eliminate every possibility).

We at Briggs Agency, Inc. specialize in restaurant insurance and understand the specific exposures your business faces. Our local agents work with you to identify coverage gaps and ensure your policies match your actual risk profile, not generic industry standards. Reach out to discuss how comprehensive coverage complements your restaurant loss prevention efforts and protects what you’ve built.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.

Insurance Terms Everyone Should Know

Insurance can be an important part of protecting your health, home, car, family, and finances. However, insurance policies often contain terms that can be confusing, especially when you are trying to understand what you are actually paying for.

Knowing common insurance terms can make it easier to compare policies, understand your coverage, and avoid surprises when you need to file a claim. Whether you are purchasing insurance for the first time or simply want to better understand your existing policy, learning the basics is a great place to start.

Do You Really Know What Your Insurance Covers?

Imagine that something unexpected happens—you get into a car accident, your home is damaged by a storm, or you need medical treatment. You turn to your insurance policy for help, only to discover that you are not sure what your deductible is, what your coverage limit means, or whether the situation is even covered.

Understanding a few key insurance terms beforehand can help you feel more prepared when you need your policy most.

1. Premium

A premium is the amount you pay to keep your insurance policy active. Depending on the type of insurance and the insurer, you may pay your premium monthly, quarterly, or annually.

For example, if your auto insurance premium is $150 per month, you pay that amount to maintain your coverage, subject to the terms of your policy.

2. Deductible

A deductible is the amount you generally have to pay out of pocket before your insurance begins paying for a covered claim.

For example, if you have a $1,000 deductible and experience a covered loss costing $5,000, you may be responsible for the first $1,000, while the insurer may cover the remaining eligible amount, subject to your policy.

3. Coverage Limit

A coverage limit is the maximum amount your insurance company will pay for a covered loss or claim.

Understanding your limits is important because having insurance does not necessarily mean every expense will be covered in full. If the cost of a covered loss exceeds your policy limit, you may be responsible for the difference.

4. Policy

Your policy is the contract between you and your insurance company. It explains what is covered, what is excluded, how much coverage you have, and what responsibilities you have as the policyholder.

Reading your policy can help you understand exactly what protection you are purchasing.

5. Claim

A claim is a request you make to your insurance company for payment or coverage after an event that may be covered by your policy.

For example, after a covered auto accident, you may file a claim so the insurer can evaluate the damage and determine what benefits or payments may apply.

6. Exclusion

An exclusion is something that your insurance policy specifically does not cover.

Exclusions can vary significantly between policies. That is why it is important not to assume that every type of damage, loss, illness, or accident is automatically covered.

7. Copayment and Coinsurance

These terms are especially common in health insurance.

A copayment, or copay, is typically a fixed amount you pay for a covered healthcare service.

Coinsurance is generally your percentage share of the cost of a covered service after you meet the applicable deductible.

Because health plans differ, it is important to review your specific policy to understand how copays, coinsurance, and deductibles work together.

8. Out-of-Pocket Maximum

An out-of-pocket maximum is a limit on what you pay toward covered healthcare services during a specific period under a health insurance plan.

Once you reach the applicable maximum, the plan generally pays 100% of covered services for the remainder of that period, subject to the plan’s rules. Premiums and certain non-covered expenses generally do not count toward this limit.

9. Liability Coverage

Liability coverage can help protect you when you are legally responsible for causing injury to another person or damage to their property.

For example, liability coverage is a common component of auto insurance and can help with covered expenses when you are legally responsible for an accident, subject to the policy’s terms and limits.

10. Replacement Cost and Actual Cash Value

These terms are commonly used in property insurance.

Replacement cost generally refers to the amount needed to replace damaged property with a similar item without subtracting depreciation, subject to the policy’s terms.

Actual cash value (ACV) generally takes depreciation into account when determining the value of damaged or lost property.

Understanding which method your policy uses can make a significant difference when you file a claim.

11. Endorsement or Rider

An endorsement, sometimes called a rider, is an addition or change to an insurance policy.

It can modify the coverage provided by the original policy. Depending on the circumstances, an endorsement may add coverage, remove coverage, or change certain policy terms.

12. Underwriting

Underwriting is the process an insurance company uses to evaluate risk and determine factors such as eligibility, coverage terms, and pricing.

The underwriting process can vary depending on the type of insurance and the insurer.

Conclusion

Insurance does not have to be difficult to understand. Learning basic terms such as premium, deductible, coverage limit, claim, exclusion, liability, and coinsurance can make it much easier to understand your policy and make informed decisions about your coverage.

Before purchasing or renewing an insurance policy, take time to review the coverage, limits, deductibles, exclusions, and other important terms. When something is unclear, ask your insurance company or licensed insurance professional to explain it.

The more familiar you are with your insurance policy, the better prepared you can be when you actually need to use it.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski
How to Prepare Your Home for Winter in Indiana

Indiana winters can bring freezing temperatures, snow, ice, and strong winds that can put extra stress on your home. Taking a few steps before winter arrives can help prevent damage, keep your home more comfortable, and potentially reduce the chance of having to file an insurance claim.

Here are a few ways Indiana homeowners can prepare their homes for winter.


Protect Your Home from Winter Damage

One of the biggest winter concerns for homeowners is frozen pipes. When temperatures drop, exposed pipes can freeze and potentially burst, leading to expensive water damage. Insulating pipes in basements, crawl spaces, garages, and other cold areas can help lower this risk. During extremely cold weather, keep your home heated and consider opening cabinet doors under sinks so warm air can circulate around the pipes.

It is also important to clean your gutters before winter. Leaves and debris can block water from draining properly and may contribute to ice dams. Ice dams can allow water to get underneath your roof and cause damage inside your home.

While checking your gutters, take a look at your roof for missing, loose, or damaged shingles. Snow and ice can make small roofing problems worse. Fixing damage before winter begins can help prevent leaks and other costly repairs.

Prepare for Cold Weather and Snow

Before temperatures drop, have your furnace or heating system checked and replace dirty filters. Make sure vents are not blocked and test your smoke detectors and carbon monoxide detectors.

If you use a fireplace, consider having the chimney inspected and cleaned. Keep furniture, decorations, and other flammable items away from fireplaces and space heaters.

Outside your home, trim dead or weak tree branches that could fall during heavy snow or ice. You should also keep sidewalks, driveways, porches, and steps clear of snow and ice to help reduce the chance of someone slipping and getting injured on your property.

Another important step is knowing where your main water shutoff valve is located. If a pipe bursts, turning off the water quickly can help limit the amount of damage.


Review Your Homeowners Insurance

Winter is also a good time to review your homeowners insurance policy. Make sure your coverage limits still reflect the value of your home and belongings.

You may also want to understand how your policy handles common winter-related losses, such as frozen pipes, falling trees, roof damage, and certain types of water damage. Coverage can vary depending on the policy and circumstances, so contact your insurance agent if you are unsure what is covered.


Preparing your home for winter can help protect your property and reduce the chance of unexpected damage during Indiana’s coldest months. Simple steps like protecting your pipes, checking your roof, maintaining your heating system, and clearing snow and ice can make a big difference.

It is also a good time to review your homeowners insurance and make sure your coverage still fits your needs before winter weather arrives.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

Common Causes of Workers’ Compensation Claims

Workers’ compensation provides financial and medical benefits to employees who suffer work-related injuries or illnesses. Workplace accidents can happen in almost any industry, whether employees work in an office, construction site, factory, warehouse, or healthcare facility. Understanding the common causes of workers’ compensation claims can help employers and employees identify workplace hazards and take steps to prevent injuries.


Slips, Trips, and Falls

Slips, trips, and falls are among the most common causes of workplace injuries. Employees may fall because of wet floors, uneven surfaces, poor lighting, cluttered walkways, or improperly maintained stairs. Accidents like this can result in injuries such as sprains, back injuries, and head injuries. Keeping work areas clean and addressing hazards promptly can reduce the risk of these incidents.

Machinery and Equipment Accidents

Employees who operate machinery or equipment may be injured when equipment malfunctions, safety procedures are not followed, or workers have not received adequate training. Injuries can range from minor cuts and bruises to serious crushing or amputation injuries. Regular equipment inspections, proper maintenance, protective equipment, and thorough safety training are important measures for reducing these risks.

Exposure to Hazardous Substances

Some workplaces involve exposure to chemicals, fumes, dust, or other hazardous materials. Without appropriate precautions, employees may develop burns, respiratory problems, skin conditions, or other work-related illnesses. Proper labeling, ventilation, protective equipment, employee training, and safe handling procedures can help minimize exposure.

Lack of Training or Safety Procedures

Insufficient training and unclear safety procedures can contribute to many types of workplace accidents. Employees who do not understand how to operate equipment, handle hazardous materials, or respond to emergencies may face a greater risk of injury. Regular training and clearly communicated safety policies can help employees recognize hazards and work safely.

Workers’ compensation claims can result from many different workplace hazards, including falls, equipment accidents, hazardous-substance exposure, workplace violence and many others. Although not every workplace injury can be prevented, employers and employees can reduce risks through proper training, regular maintenance, effective safety procedures, and prompt attention to hazards. Creating a strong culture of workplace safety benefits both employees and employers by helping prevent injuries and promoting a healthier work environment.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog written by: Sara Trajanoska

How Tool Theft Can Impact Your Business

For contractors and tradespeople, tools are more than just equipment—they are what keep the business running. When those tools are stolen, the impact can go far beyond the cost of replacing them.

Tool theft can create serious problems for a business, especially when expensive equipment is taken from a jobsite, work truck, trailer, or storage area. Missing tools can delay projects, interrupt daily operations, and lead to unexpected replacement costs. In some cases, a business may even lose income while waiting for essential equipment to be replaced.

Understanding how tool theft can affect your business can help you prepare for the unexpected and make sure you have the right insurance protection in place.\

Here are a few ways that tool theft can impact your business.

Project Delays

When important tools are stolen, work may have to slow down or stop completely until replacements can be found. This can push projects behind schedule and make it harder for employees to complete their work on time. Even the theft of a few commonly used tools can create major problems, especially if they are needed for specific parts of a job. Delays can also affect other projects that were scheduled afterward.

Unexpected Replacement Costs

Professional tools and equipment can be expensive to replace, especially when multiple items are stolen at once. Power tools, generators, specialty equipment, and other jobsite supplies can quickly add up to thousands of dollars. For a small business, having to replace these items unexpectedly can put a significant strain on the budget. These expenses may also take money away from other important business needs.

Lost Income

Tool theft can lead to lost income when a business is unable to complete work as planned. If employees cannot perform certain jobs without the stolen equipment, projects may need to be postponed or canceled. This can result in fewer completed jobs and less revenue coming into the business. In some situations, customers may also choose another contractor if the delay is too long.

Increased Labor Costs

Employees may still need to be paid even when work is delayed because important tools are missing. Once replacement equipment is available, workers may need to put in additional hours to catch up on delayed projects. This can increase overtime and labor costs. What starts as a simple theft can quickly become a much larger financial problem for the business.

Damage to Vehicles or Property

Tool theft can also cause damage beyond the missing equipment itself. Thieves may break windows, damage locks, force open trailers, or damage storage areas while trying to access tools. Businesses may then be responsible for repairing vehicles, doors, locks, or other property in addition to replacing the stolen items. These extra repair costs can make the situation even more expensive.

Customer Relationships Can Be Affected

Customers expect businesses to complete work on time and keep projects moving smoothly. If stolen tools cause delays, customers may become frustrated when jobs have to be rescheduled or extended. While many customers may understand the situation, repeated delays can still affect their overall experience. In some cases, it may also impact the business’s reputation and future referrals.

Insurance Can Help Protect Your Business

The right insurance coverage may help reduce the financial impact of tool theft. Depending on the policy, coverage may help pay for stolen tools, equipment, or certain related losses. However, coverage can vary depending on where the tools were stored, how they were being used, and the specific policy limits. Business owners should review their coverage regularly to make sure their tools and equipment are properly protected.

Conclusion

Tool theft can have a much bigger impact on a business than simply replacing a few missing items. It can lead to project delays, lost income, added labor costs, property damage, and unhappy customers. For contractors and other businesses that rely on tools every day, even one theft can quickly disrupt normal operations.

Taking steps to secure your equipment and reviewing your insurance coverage can help reduce the financial impact if theft does happen. Keeping an updated inventory of your tools, storing equipment securely, and understanding what your policy covers can help your business recover faster and get back to work.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes

Restaurant Insurance Quotes: Compare Top Rates Now

Running a restaurant means managing countless moving parts, and one of the most overlooked is proper insurance coverage. Without the right protection, a single incident-a customer injury, equipment failure, or property damage-can threaten your entire business.

At Briggs Agency, Inc., we help restaurant owners find restaurant insurance quotes that actually match their needs. Getting accurate quotes and comparing your options is the first step toward real peace of mind.

Why Your Restaurant Needs Real Insurance Protection

Real Risks That Threaten Your Business

A customer slips on a wet floor and breaks their arm. Your walk-in cooler fails overnight and spoils thousands of dollars in inventory. A kitchen fire damages the building structure. These aren’t hypothetical scenarios-they happen regularly in restaurants across the country. Without proper insurance, that single incident becomes an existential threat to your business.

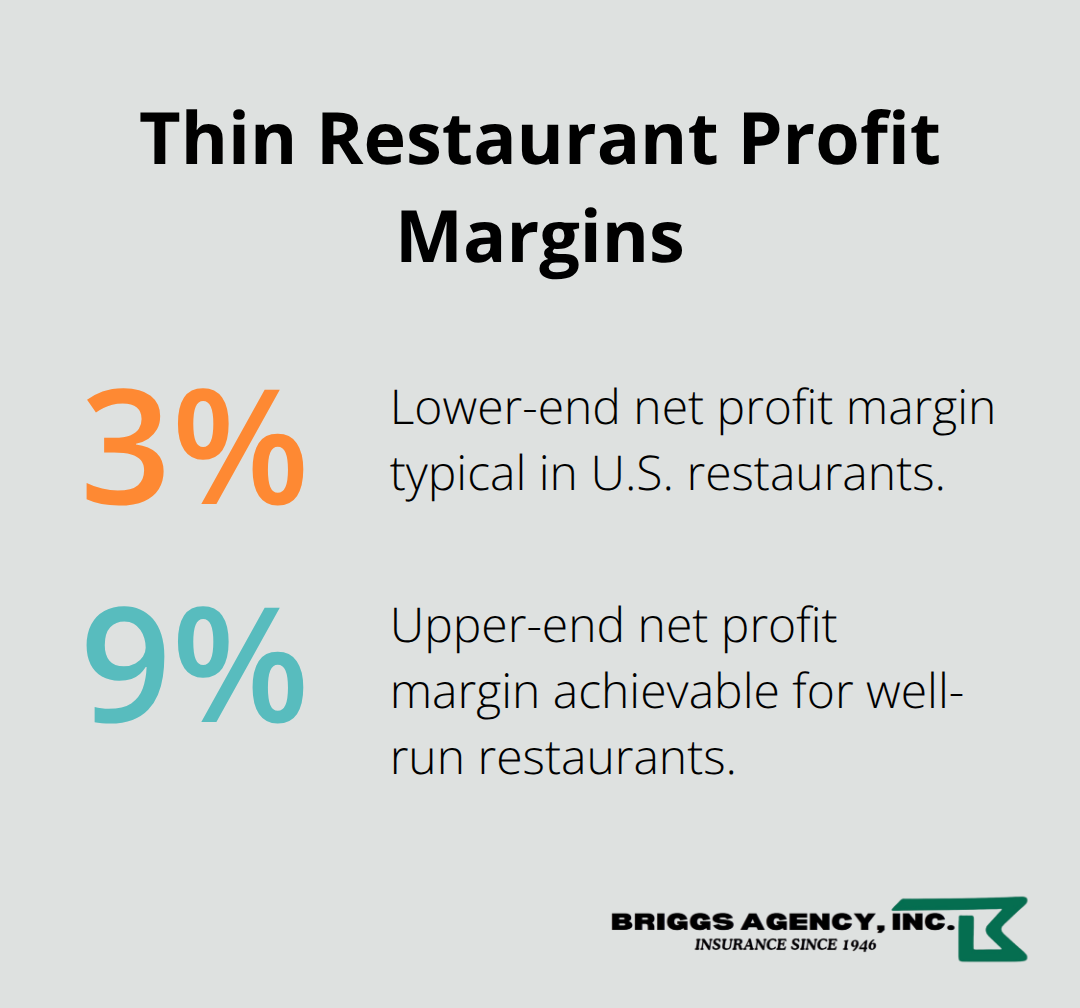
The restaurant industry operates on thin margins, typically ranging from 3% to 9% net profit, which means most owners lack the cash reserves to absorb major losses. A liability claim from a customer injury can easily exceed $100,000 when medical expenses and legal fees combine. Property damage claims average $50,000 to $200,000 depending on the extent of the loss. Insurance isn’t optional-it’s the difference between recovery and closure.

Visualization of typical U.S. restaurant net profit margins showing a narrow 3%–9% range.

Legal Requirements You Can’t Ignore

State and local regulations make insurance mandatory, not optional. Every state requires workers compensation insurance if you employ staff, and many jurisdictions mandate general liability coverage before you can obtain a business license. Indiana, where we operate, requires workers compensation for any business with employees.

Beyond legal requirements, lenders and landlords won’t finance or lease to restaurants without proof of adequate coverage. Your lease agreement almost certainly includes an insurance requirement clause that specifies minimum coverage amounts and names the landlord as an additional insured. Failing to maintain required coverage can result in fines ranging from $500 to $5,000 per violation, lease termination, or loss of your operating license.

Protecting Your Personal Assets

Operating without proper insurance exposes your personal assets-your home, savings, and future earnings-to liability judgments. Courts regularly award damages that far exceed business assets, meaning creditors can pursue personal property. A single lawsuit can wipe out decades of personal wealth (and your ability to rebuild).

Getting accurate quotes from multiple carriers and understanding exactly what each policy covers protects both your business legally and your personal finances practically. The next step involves identifying which specific coverage types your restaurant actually needs.

The Coverage Your Restaurant Actually Needs

General Liability: Your First Line of Defense

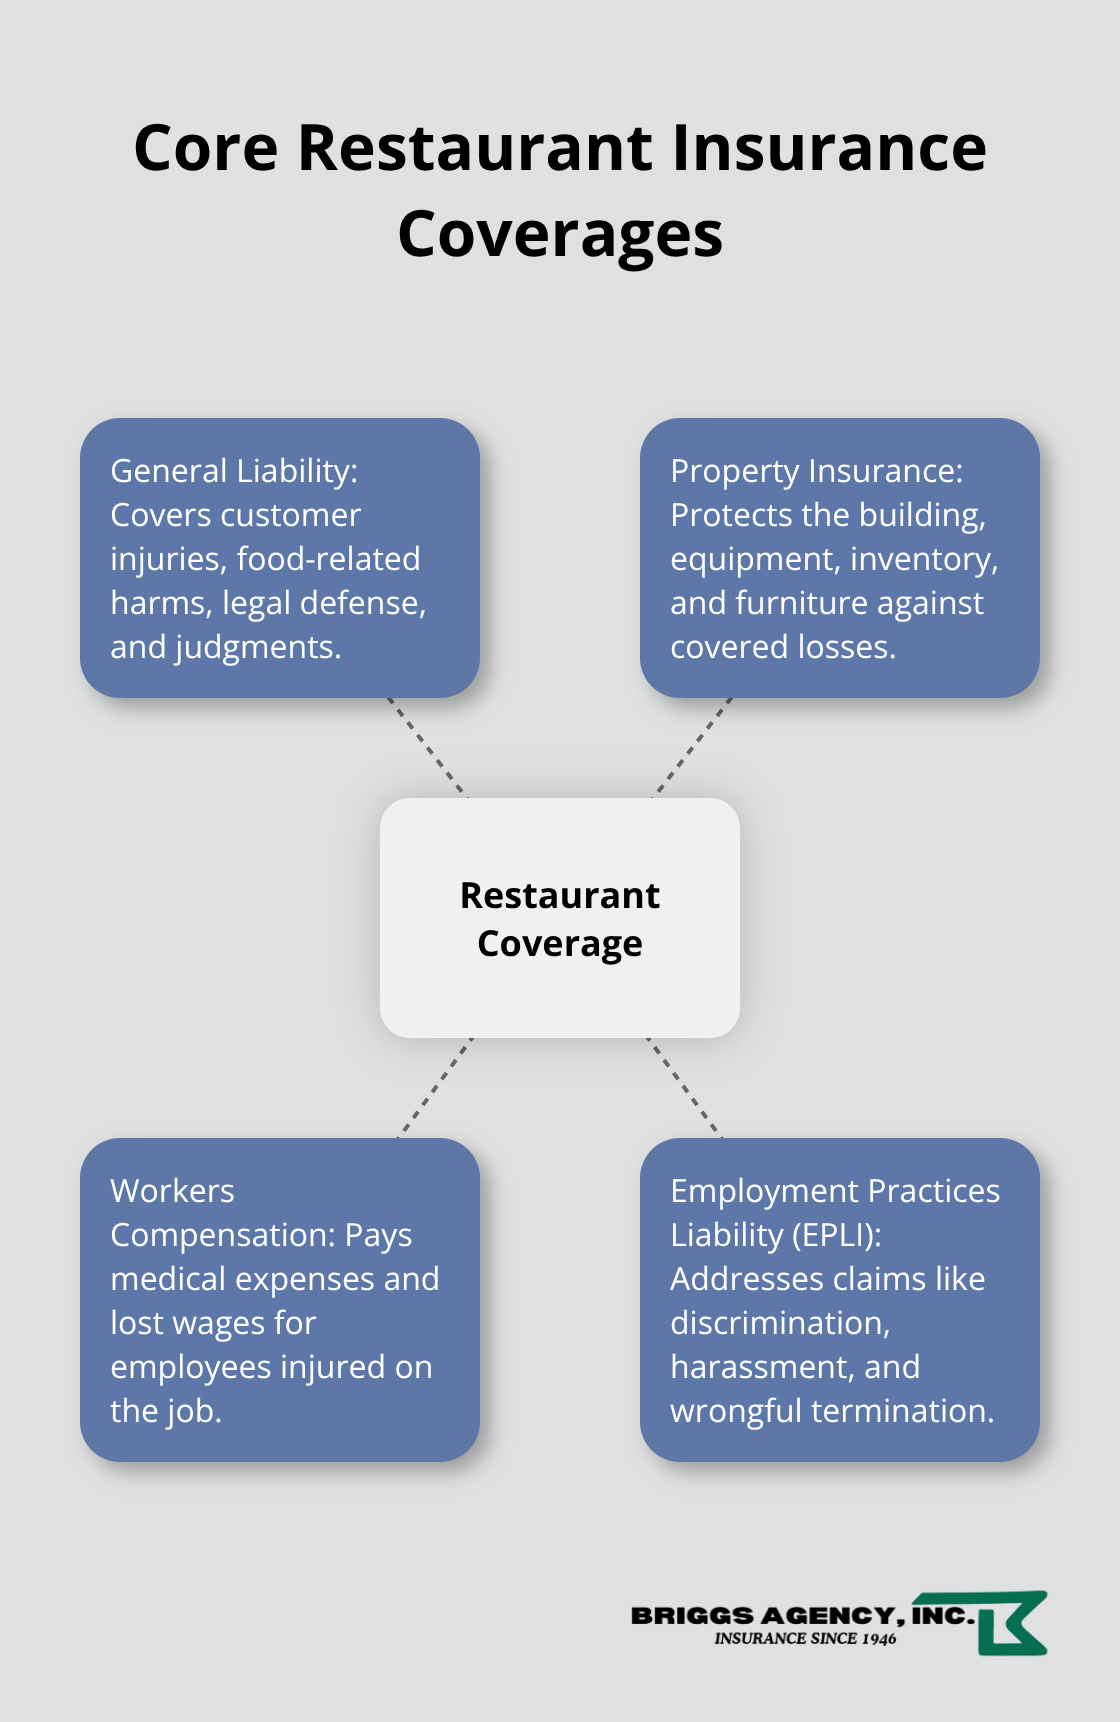
General liability coverage protects your restaurant when a customer gets injured on your premises or claims your food caused them harm. This covers medical expenses, legal defense costs, and court judgments-not just the occasional slip-and-fall. According to the National Restaurant Association, foodborne illness claims and customer injury lawsuits represent the second-largest expense category for restaurants after labor costs.

Hub-and-spoke diagram showing four essential restaurant insurance coverages and what each protects. - restaurant insurance quotes

Most restaurants need minimum coverage of $1 million per occurrence and $2 million aggregate, though higher-volume establishments should consider $2 million per occurrence. Your lease agreement almost certainly requires you to name the landlord as an additional insured on this policy, which means the coverage extends to protect them as well.

Property Insurance: Protecting Your Physical Assets

Property insurance covers your building, equipment, inventory, and furniture-the physical assets that generate revenue. A kitchen fire, roof collapse, or equipment failure can cost $75,000 to $300,000 depending on your restaurant size and equipment age. Standard property policies don’t cover everything, so you need to specify high-value items like commercial ovens, refrigeration units, and POS systems.

Spoilage coverage is critical for restaurants with significant inventory; it reimburses you when equipment failure causes food loss. Many restaurant owners underestimate their property values during the quote process and end up underinsured-document every piece of equipment and its replacement cost when gathering information for quotes.

Workers Compensation: A Legal Requirement with Real Impact

Workers compensation insurance is legally mandatory in Indiana for any restaurant with employees, and it covers medical expenses and lost wages when an employee gets injured on the job. Restaurant workers face higher injury rates than most industries; restaurants experience higher injury rates than the national average.

A serious kitchen burn or slip injury can cost $40,000 to $150,000 in medical bills and legal liability. Without proper coverage, these expenses fall directly on your business.

Employment Practices Liability: Protecting Against Workplace Claims

Employment practices liability insurance protects against claims of discrimination, wrongful termination, or harassment-issues that arise more frequently in high-turnover restaurant environments. This coverage addresses the reality of managing diverse teams and the legal exposure that comes with employment decisions.

When you request quotes, bundle these coverages together, as carriers often provide discounts when you stack multiple policies. The key to accurate quotes is providing detailed information about your payroll, number of employees, job duties, and safety procedures to each carrier you contact. This information directly affects your premium rates and determines whether you receive adequate coverage limits for your specific operation.

How to Get Accurate Restaurant Insurance Quotes

Compile Your Restaurant’s Operational Details

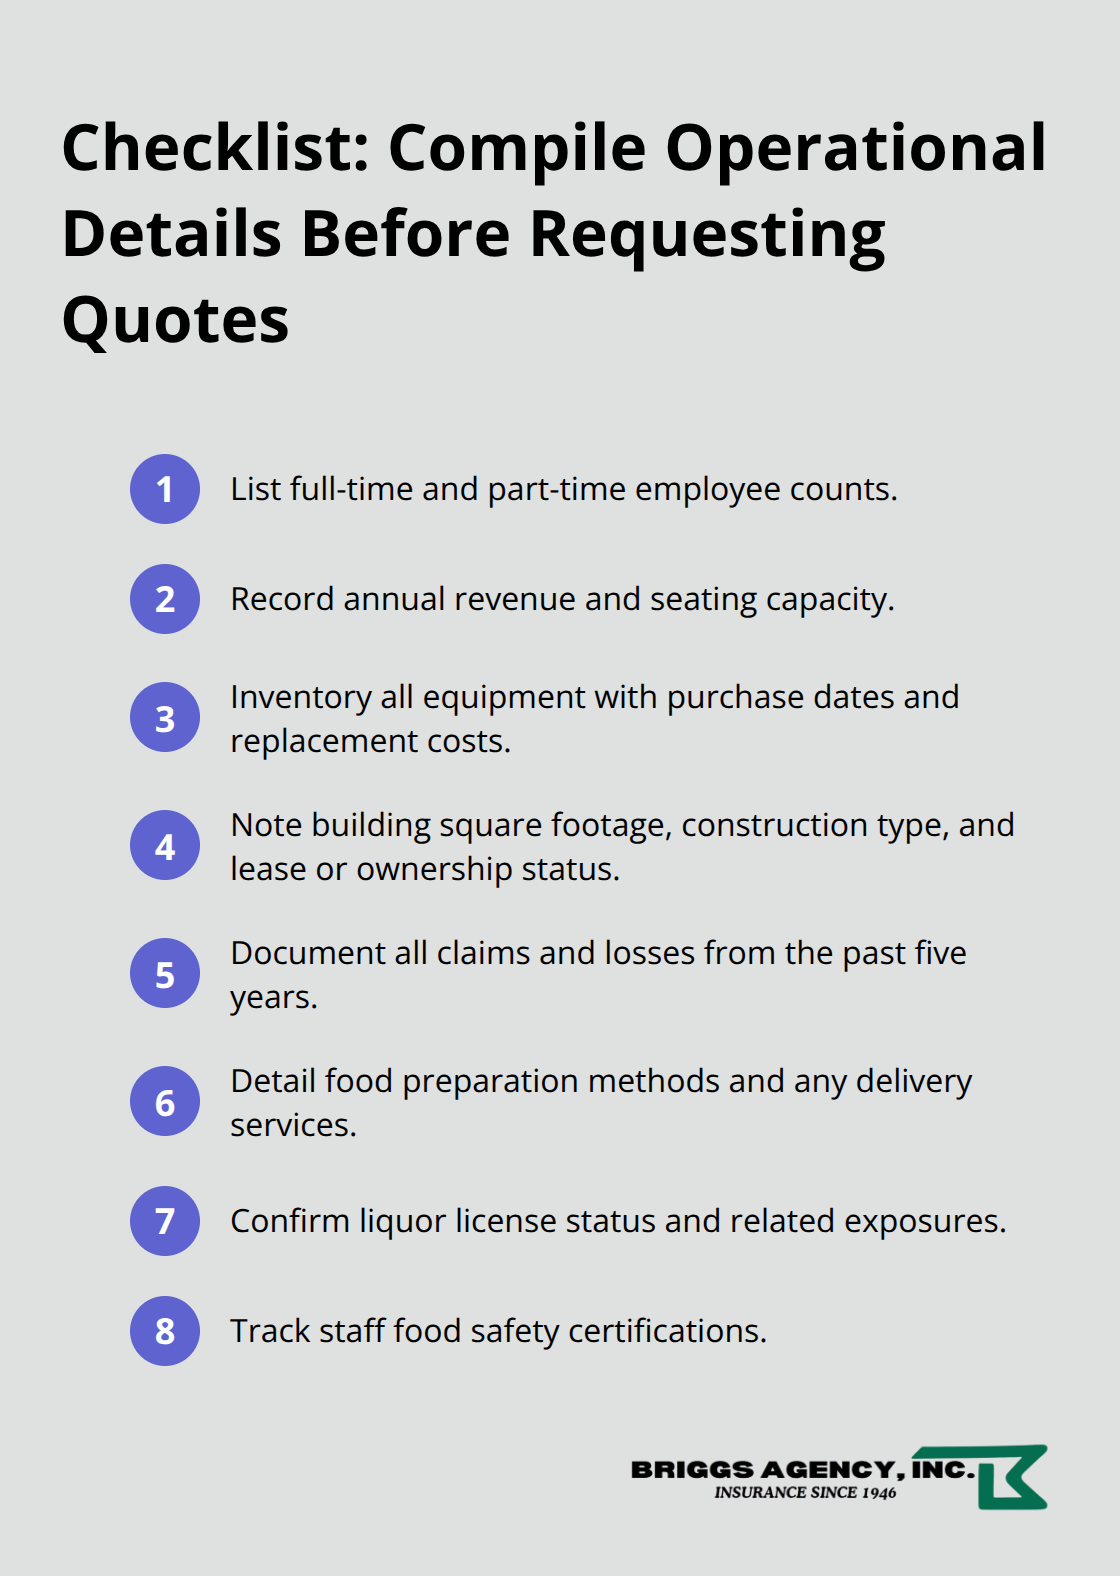
Requesting quotes without proper preparation wastes everyone’s time and produces inaccurate pricing. Insurance carriers base their rates on specific operational details, and incomplete information forces them to estimate-which means your quotes won’t reflect your actual risk profile. Start by documenting your restaurant’s exact staffing numbers, including full-time and part-time employees, since payroll directly affects workers compensation premiums. Record your annual revenue and seating capacity, as these metrics determine your liability exposure. List every piece of equipment in your kitchen with purchase dates and replacement costs-commercial ovens, refrigeration units, grills, and POS systems all factor into property insurance calculations. Note your building’s square footage, construction type, and whether you own or lease the space. Document any prior claims or losses from the past five years, including minor incidents, since carriers pull this history during underwriting. Include details about your food preparation methods, whether you have a liquor license, if you offer delivery services, and what food safety certifications your staff maintains. This level of detail takes time to compile, but it eliminates the frustration of receiving quotes that don’t match your actual situation.

Compact checklist of the key operational details to prepare for accurate restaurant insurance quotes.

Request Identical Coverage Across All Carriers

Many restaurant owners contact three to five carriers simultaneously and compare quotes side-by-side, but this approach fails if you’re not comparing identical coverage. A $500 monthly premium looks attractive until you realize it includes a $10,000 deductible and only $500,000 in general liability coverage-far below your actual needs. Request quotes that specify the same coverage limits across all carriers so you’re genuinely comparing apples to apples. Ask each carrier to explain what their policy excludes, since standard restaurant policies often exclude liquor liability, spoilage coverage, or high-value equipment without additional riders.

Verify Coverage Classifications and Rates

When you receive quotes, verify that each one includes workers compensation at the rate your state calculates for restaurants. A quote that seems significantly lower than others usually contains coverage gaps or higher deductibles that create financial risk when claims occur. Reputable agents will be transparent about pricing and won’t oversell unnecessary coverage. Review the deductibles carefully; a $2,500 deductible saves on premiums but means you pay that amount out-of-pocket before coverage kicks in, so choose a level your business can actually absorb during a loss.

Compare at Least Three Carriers

Try requesting quotes from at least three carriers, then ask each one to explain how their rates compare to competitors. This approach reveals which carriers offer competitive pricing for your specific operation and which ones price above market. Carriers that represent multiple top-rated insurers (rather than just one) can often deliver more competitive options tailored to your restaurant’s unique risk profile.

Final Thoughts

Your restaurant’s protection depends on three essential coverage types that work together to shield both your business and personal finances. General liability handles customer injuries and food-related claims, property insurance protects your building and equipment, and workers compensation covers your staff-employment practices liability rounds out your protection by addressing workplace disputes that arise in high-turnover environments. A single incident without proper coverage can force closure, so these policies represent the difference between recovery and financial devastation.

Accurate restaurant insurance quotes require you to document your staffing numbers, equipment inventory, annual revenue, and prior claims before contacting carriers. Request identical coverage limits across multiple carriers so you compare real options rather than chasing the lowest premium that might leave you underinsured, and verify that each quote includes the specific coverage types your operation needs. Deductibles matter significantly-choose a level your business can absorb during a loss rather than selecting the lowest premium available.

We at Briggs Agency, Inc. have helped restaurant owners across Indiana find competitive restaurant insurance quotes since 1946, and our independent agency represents multiple top-rated carriers to match your unique risk profile. Our local agents understand the specific challenges restaurants face and deliver both competitive pricing and the right protection for your business. Contact Briggs Agency, Inc. to request quotes and receive the hands-on guidance that transforms insurance from an overwhelming task into a straightforward decision.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.

Common Causes of Workers’ Compensations Claims

Workplace accidents can happen when you least expect them, and even one injury can lead to medical bills, lost wages, and unexpected costs for a business.

Workers’ compensation insurance is designed to help protect both employees and employers when a work-related injury or illness occurs. While every workplace has different risks, certain types of accidents are responsible for many workers’ compensation claims. Understanding the most common causes can help business owners recognize potential hazards, improve workplace safety, and reduce the chances of an injury happening in the first place.

Here are some of the most common causes of workers’ compensation claims

1. Slips, Trips, and Falls

Slips, trips, and falls can happen in almost any type of workplace. Wet floors, uneven flooring, loose cords, cluttered walkways, poor lighting, and icy sidewalks can all create hazards for employees. Workers in construction, restaurants, warehouses, offices, and retail stores may all be exposed to these risks.

These accidents can cause a wide range of injuries, including sprains, broken bones, back injuries, head injuries, and bruising. Employers can help reduce the risk by keeping walkways clear, cleaning spills quickly, using proper warning signs, and making sure employees have appropriate footwear when needed.

2. Overexertion From Lifting or Carrying

Overexertion injuries often happen when employees lift, carry, push, pull, or move heavy objects. These injuries are especially common in industries such as construction, manufacturing, warehousing, healthcare, and delivery services.

Lifting something incorrectly or repeatedly performing physically demanding tasks can lead to back pain, muscle strains, shoulder injuries, and other problems. Employers can help prevent these injuries by providing proper lifting training, encouraging employees to ask for help with heavy items, and using equipment such as carts, dollies, or lifting devices.

3. Vehicle-Related Accidents

Employees who drive for work may face a higher risk of vehicle-related injuries. This can include delivery drivers, sales employees, construction workers, truck drivers, and employees who travel between different locations during the workday.

Accidents may happen because of distracted driving, bad weather, heavy traffic, speeding, or another driver’s actions. Injuries from vehicle accidents can range from minor soreness to more serious head, neck, or back injuries. Businesses can help lower these risks by creating safe driving policies, maintaining company vehicles, and encouraging employees to avoid distractions while driving.

4. Workplace Violence

Workplace violence can occur in many different forms. It may involve conflicts between employees, aggressive customers, robbery attempts, or other threatening situations. Employees who work directly with the public, handle money, work late hours, or work alone may face a higher risk.

Physical injuries caused by workplace violence can sometimes result in workers’ compensation claims. Employers can help create a safer environment by having clear workplace conduct policies, providing conflict-resolution training, improving security measures, and encouraging employees to report threats or concerning behavior.

5. Cuts and Lacerations

Cuts and lacerations are common in workplaces where employees regularly use knives, tools, machinery, glass, metal, or other sharp materials. Restaurants, construction sites, manufacturing facilities, auto repair shops, and warehouses are just a few examples of workplaces where these injuries may occur.

Some cuts may only require basic first aid, while more serious injuries can require stitches, surgery, or time away from work. Employers can help reduce the risk by providing proper protective equipment, maintaining tools and machinery, training employees on safe procedures, and making sure sharp objects are stored correctly when not in use.

Conclusion

Workplace injuries can happen in almost any industry, which is why it is important for business owners to understand the risks their employees may face. Identifying common causes of workers’ compensation claims can help businesses take steps to create a safer work environment.

Even with strong safety procedures in place, accidents can still happen. Having the right workers’ compensation coverage can help protect employees while also helping businesses manage the financial impact of a workplace injury.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!


Blog Post written by: Alex Condes

How Much Business Insurance Does A Contractor Need

Running a contracting business comes with more than just completing projects and keeping customers satisfied. Contractors face risks every day, from accidental property damage and job-site injuries to damaged equipment and vehicle accidents. That is why having the right business insurance is an important part of protecting your company, your employees, and your financial future.

But how much insurance does a contractor actually need? The answer depends on several factors, including the type of contracting work you perform, the size of your business, the number of employees you have, and the requirements of your clients and contracts.

One Accident Can Change Everything

Imagine finishing a major project when a customer suddenly claims that your work caused significant property damage. Or imagine an employee is injured while working on a job site and files a claim against your business. Without adequate insurance coverage, an incident that takes only minutes to happen could potentially cost your business thousands—or even hundreds of thousands—of dollars.

The right insurance does not eliminate every risk, but it can help prevent one unexpected event from putting your entire contracting business in financial danger.

General Liability Insurance

General liability insurance is one of the most important types of coverage for contractors. It can help protect your business when someone claims that your work caused bodily injury, property damage, or certain other covered losses.

A common starting point for contractors is $1 million per occurrence and $2 million in aggregate coverage. However, the appropriate limit can vary depending on the size and type of your business.

For example, a contractor working on small residential projects may have different insurance needs than a contractor working on large commercial construction projects.

Workers’ Compensation Insurance

If you have employees, workers’ compensation insurance may be required by law depending on where your business operates and other factors. Workers’ compensation can help cover medical expenses and lost wages resulting from qualifying work-related injuries.

Contractors should understand their state’s requirements and make sure their coverage accurately reflects their workforce and payroll.

Commercial Auto Insurance

If you use trucks, vans, or other vehicles for your contracting business, personal auto insurance may not provide the protection you need for business use.

Commercial auto insurance can help cover certain accidents involving business vehicles. The appropriate liability limit depends on factors such as the vehicles you operate, the type of work you perform, and contractual requirements.

For contractors with multiple vehicles or significant driving exposure, reviewing commercial auto coverage regularly is especially important.

Tools and Equipment Coverage

Contractors often depend on expensive tools and equipment to earn their income. If those items are stolen, damaged, or destroyed, replacing everything out of pocket can be expensive.

Tools and equipment coverage can help protect the property your business relies on. Contractors should consider the total replacement value of their equipment rather than simply estimating what they think they could afford to replace.

Keeping an updated inventory of tools and equipment can also make it easier to determine appropriate coverage.

Builder’s Risk Insurance

Some construction projects require protection for the building and materials while construction is underway. Builder’s risk insurance can provide coverage for certain property losses during the construction process.

Whether you need this type of insurance depends on the projects you take on and who is responsible for insuring the property during construction. Contracts should be reviewed carefully to determine what coverage is required.

Umbrella and Excess Liability Coverage

Some contractors may need more liability protection than a standard policy provides. An umbrella or excess liability policy can provide additional limits above certain underlying liability policies.

For contractors working on larger projects or with significant assets, additional liability limits may be required by a contract or may be considered as part of a broader risk-management strategy.

So, How Much Insurance Does a Contractor Need?

There is no single insurance amount that works for every contractor. A small residential contractor and a large commercial contractor can have dramatically different risks and contractual requirements.

As a general starting point, many contractors look at:

  • General liability: $1 million per occurrence / $2 million aggregate

  • Workers’ compensation: As required by applicable state law

  • Commercial auto: Coverage appropriate for the business vehicles and contractual requirements

  • Tools and equipment: Enough coverage to replace covered business property

  • Builder’s risk: When required or appropriate for a construction project

  • Umbrella/excess liability: Additional limits when the contractor’s risks or contracts warrant them

These are general starting points, not a one-size-fits-all insurance prescription.

Conclusion

Business insurance is an important part of protecting a contracting company from unexpected financial losses. The amount of coverage you need depends on your trade, employees, equipment, vehicles, projects, contracts, and the laws that apply where you operate.

Rather than choosing coverage based only on the cheapest premium, contractors should evaluate the risks their business faces and make sure their insurance limits match those risks and their contractual obligations. Taking the time to review your coverage before an accident happens can help you avoid discovering that you are underinsured when you need protection the most.

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: David Stefanoski
Restaurant Insurance Costs: Balancing Premiums And Protection

Restaurant insurance costs often feel like a puzzle with no clear answer. You want solid protection without overpaying, but understanding what actually drives your premiums is half the battle.

At Briggs Agency, Inc., we’ve helped countless restaurant owners find that balance. This guide walks you through the real factors affecting your rates and practical ways to lower them without sacrificing coverage.

What Pushes Restaurant Insurance Rates Up

Location and Local Risk Factors

Your location matters more than most restaurant owners realize. Restaurants in high-crime areas or flood-prone zones pay significantly higher premiums than those in safer neighborhoods. Urban locations typically cost 20-40% more than suburban counterparts, according to insurance industry data. If your restaurant sits in a building with outdated electrical systems or poor fire suppression equipment, insurers will flag that immediately and adjust your rates accordingly. Local risk factors extend beyond crime-they include weather patterns, proximity to water sources, and even the density of other restaurants nearby, which affects competition for claims data in your area.

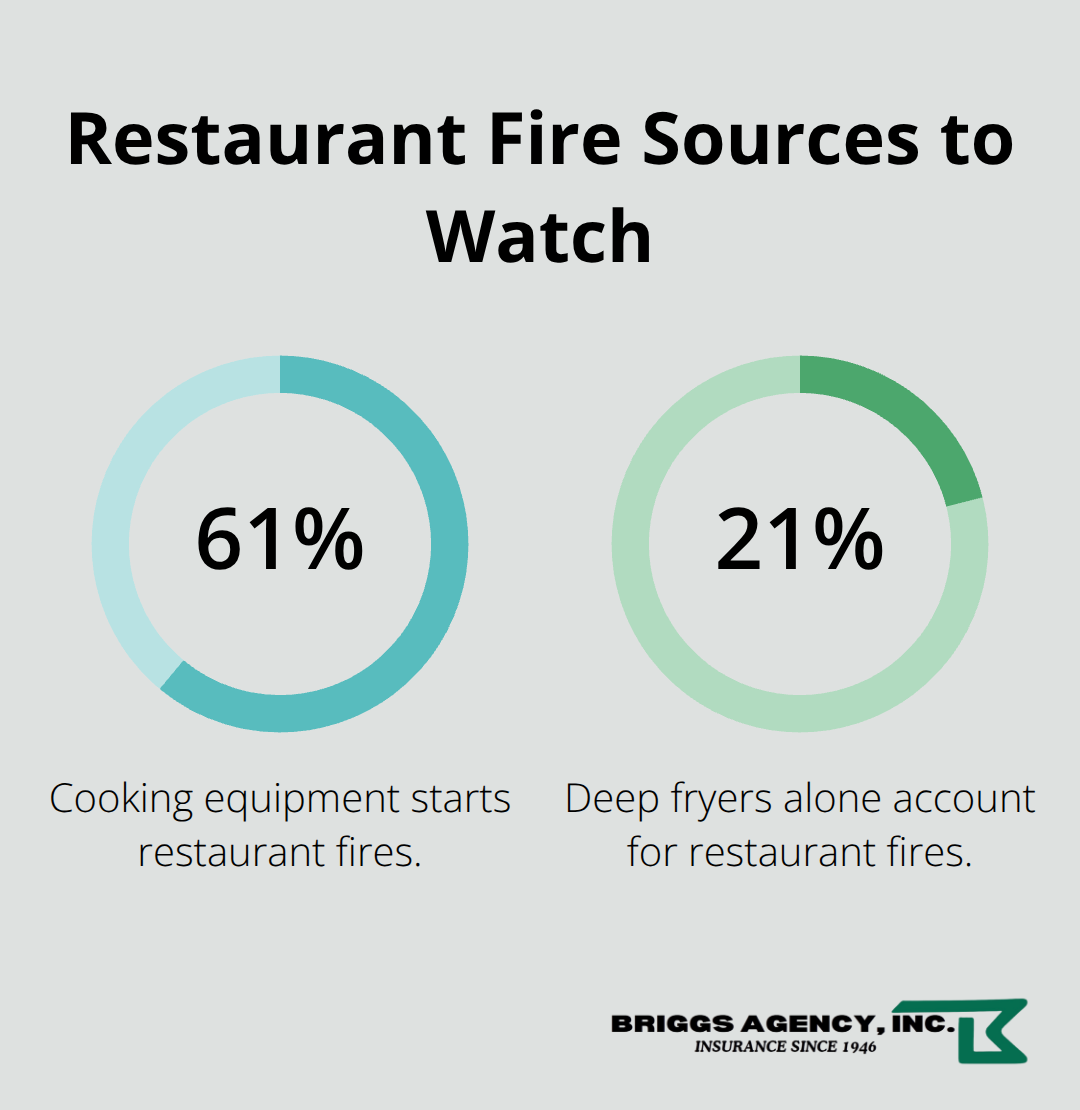
Percentage of restaurant fires by source in the United States - restaurant insurance costs

Kitchen Operations and Cuisine Type

Your kitchen operations and cuisine type directly influence what you’ll pay. A steakhouse with high-volume grilling operations faces different hazards than a pasta restaurant, and insurers price accordingly. Cooking equipment starts 61% of restaurant fires, with deep fryers alone accounting for 21%. Restaurants with wok stations, open flames, or extensive deep-frying operations pay more because the risk is measurably higher.

Employee Count and Payroll Size

Your employee count and total payroll size affect workers compensation costs, which typically represent 25-35% of overall restaurant insurance expenses. A 20-person operation with $400,000 in annual payroll will have substantially different rates than a 50-person restaurant with $1.2 million in payroll. This variable scales directly with your staffing decisions and wage structure.

Claims History and Building Condition

Your claims history carries enormous weight in rate calculations. One serious incident can increase premiums by 50% or more for three to five years. Insurers view restaurants with clean records as lower risk, rewarding them with better rates. Building age and safety features round out the equation-a restaurant in a recently renovated space with modern fire detection systems, updated electrical work, and current building code compliance will qualify for better rates than one in an older structure with deferred maintenance.

These five factors work together to create your baseline premium. Understanding each one helps you identify where you have actual control over costs, which is exactly what we’ll address next.

How to Actually Cut Your Restaurant Insurance Costs

Prove Your Restaurant Is Safer Than Average

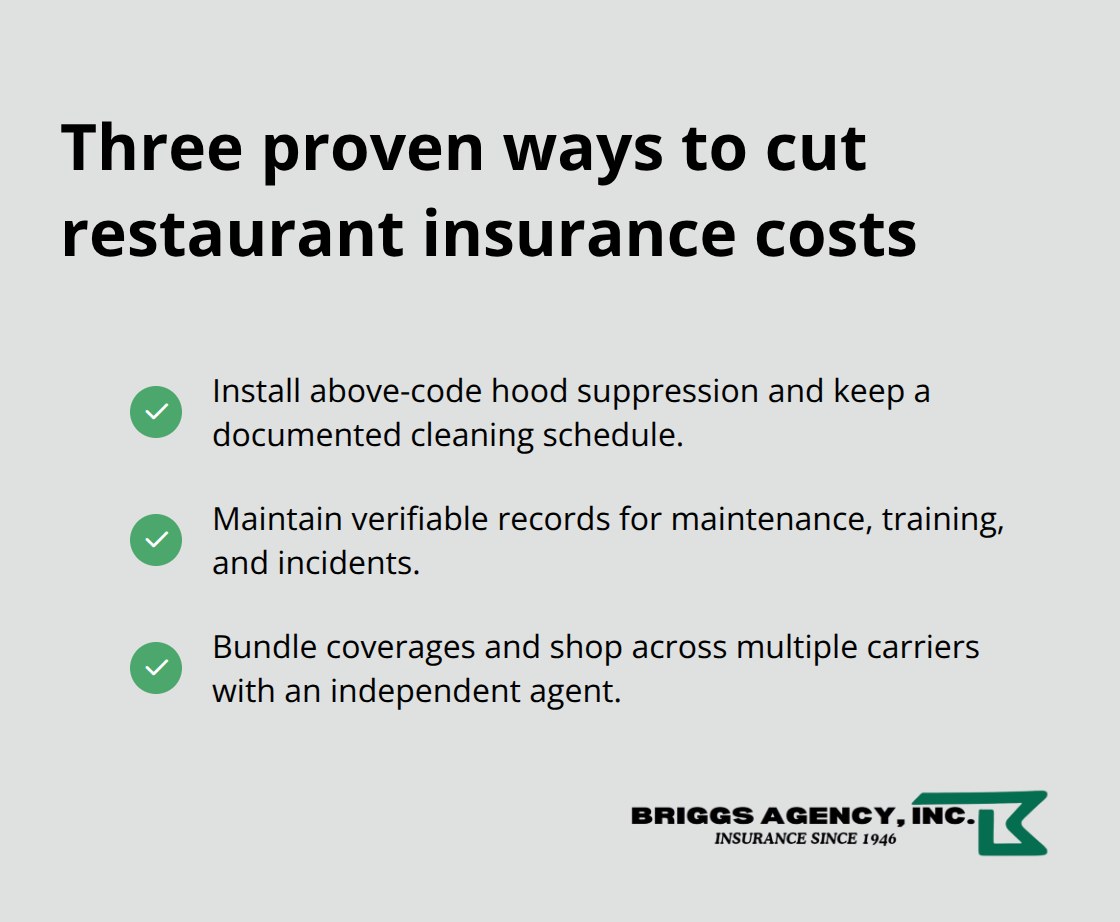
Insurers reward restaurants that implement specific, measurable safety improvements rather than simply meeting minimum code requirements. Install hood suppression systems that exceed code requirements, establish a documented cleaning schedule for cooking equipment, and require staff to complete food safety certifications like ServSafe. These aren’t just nice-to-haves-restaurants with documented safety programs see premium reductions of 10-15% compared to those without them. Your insurance agent needs to see written procedures for temperature control, chemical storage, and emergency response, not just hear that you care about safety.

Document Everything Insurers Care About

Documentation matters more than most owners realize because insurers make rate decisions based on what they can verify. Maintain detailed records of equipment maintenance, staff training completion dates, and any safety incidents with how you resolved them. When an insurer reviews your file, they’re looking for evidence that you take risk seriously. This documentation also protects you if you ever need to file a claim-clear records of what happened and when speed up the process significantly.

Checklist of actions to reduce restaurant insurance premiums in the U.S.

Bundle Your Coverages Strategically

Most restaurant owners carry general liability, workers compensation, and property insurance separately, but bundling these with a single carrier typically saves 15-25% compared to the total of separate policies. The savings come from reduced administrative costs that carriers pass along to you. Work with an independent agent who represents multiple carriers rather than being locked into one company’s rates. An agent working with ten different insurers can find carriers that specialize in restaurants and price accordingly-some carriers actively compete for restaurant business while others avoid it entirely, which means your rate depends heavily on who’s quoting you.

Invest in Employee Training Programs

Well-trained staff create fewer claims, and insurers recognize this when renewing your policy. Restaurants that invest in quarterly safety training and proper equipment operation instruction experience fewer workers compensation claims. Your team’s competence directly affects your bottom line through lower premiums and reduced incident frequency. This training investment pays for itself through rate reductions alone, before you factor in the operational benefits of having a safer, more skilled workforce.

These concrete actions address the three areas where restaurant owners actually control their costs: proving safety, documenting risk management, and shopping aggressively across carriers. But even owners who execute all three perfectly often miss significant coverage gaps that leave them exposed to unexpected expenses.

What Coverage Gaps Actually Cost Restaurant Owners

Liquor Liability Protection

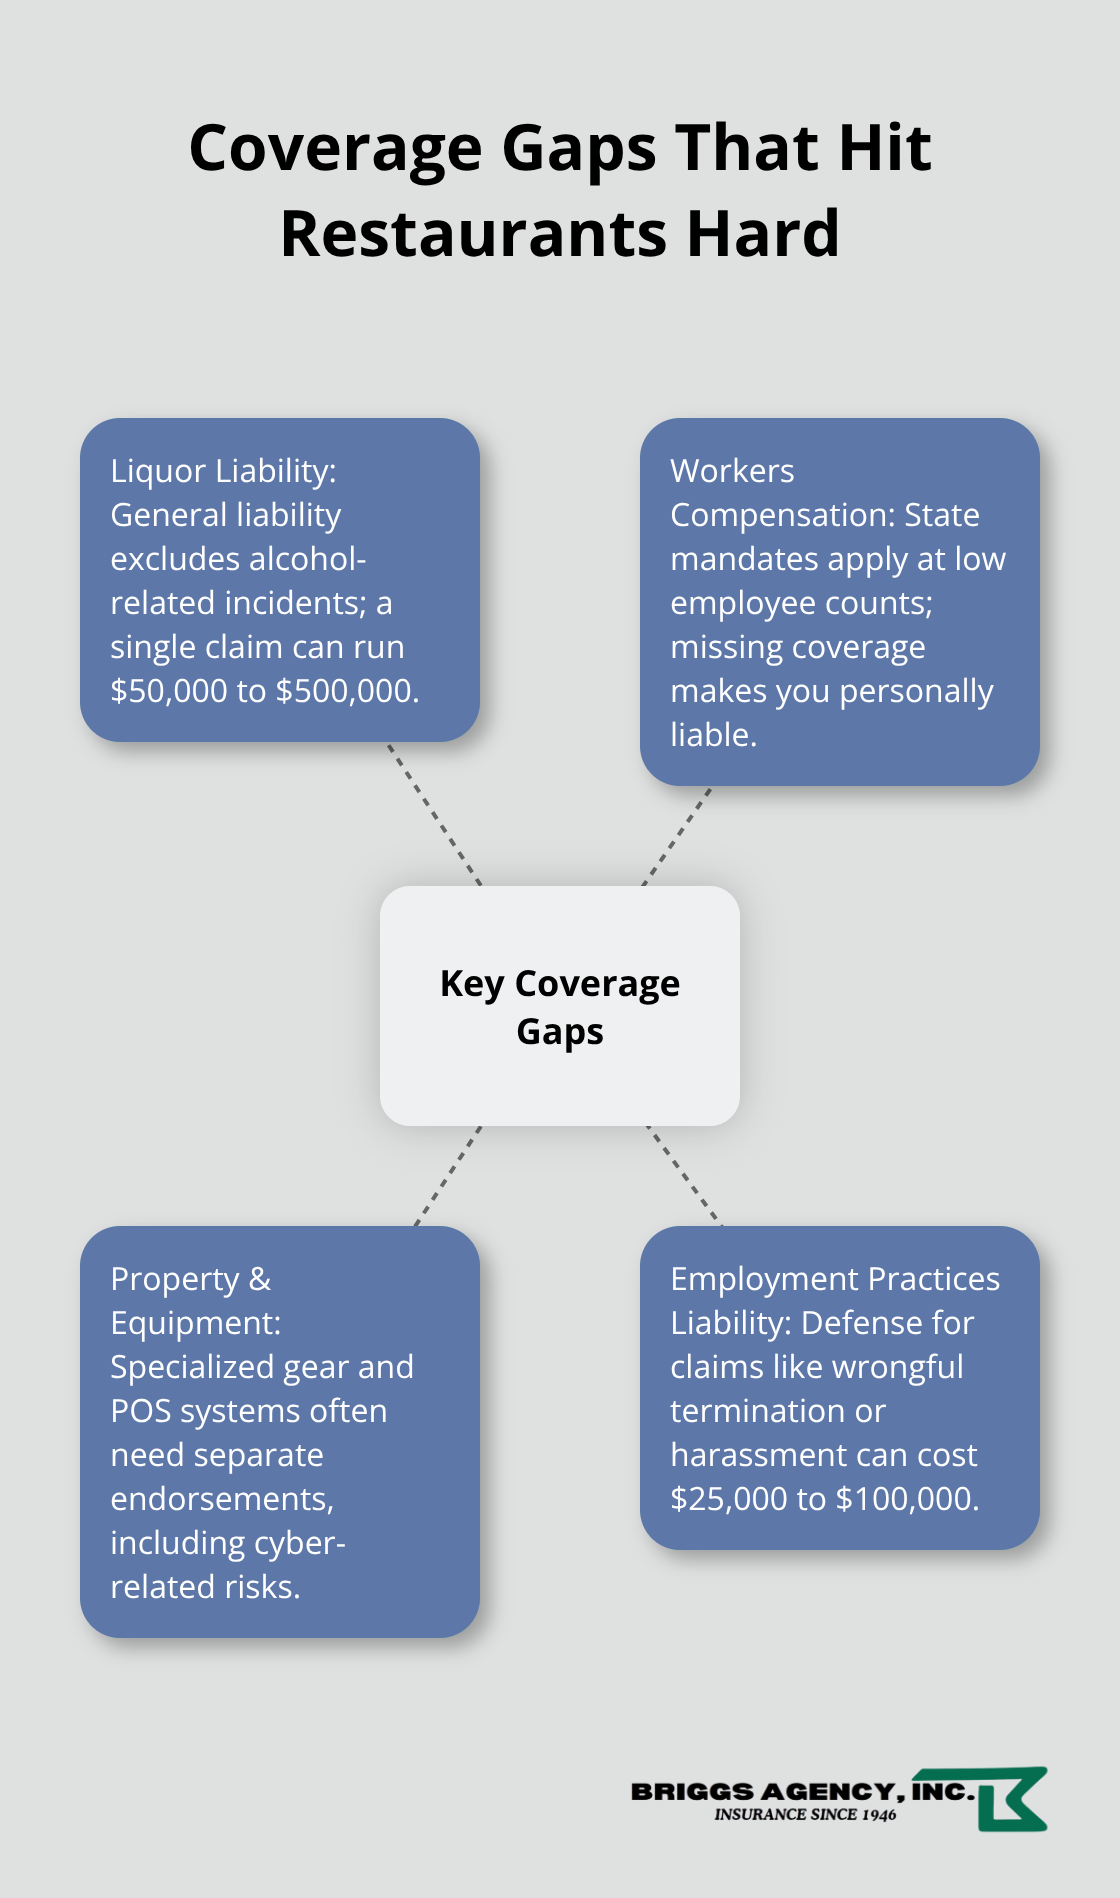
Most restaurant owners assume their general liability policy covers alcohol-related incidents. It doesn’t. If a customer becomes intoxicated at your bar and causes an accident outside your restaurant, or if someone gets ill from alcohol you served, your standard general liability won’t cover it. A single liquor liability claim can run $50,000 to $500,000 depending on severity. The cost of liquor liability coverage varies based on several factors including location, type of establishment, coverage limits, and insurance providers. Many owners think bundling their policies means comprehensive protection, then face shock when their insurer denies a claim.

Workers Compensation Requirements

Workers compensation requirements vary by state, but most states require coverage once you hit a specific employee threshold-typically three to five employees depending on your location. Indiana requires coverage for restaurants with three or more employees.

Hub-and-spoke diagram of common restaurant insurance coverage gaps in the U.S. - restaurant insurance costs

Many owners either skip this entirely or underestimate their payroll when calculating premiums, which leaves them either uninsured or underinsured. If an employee gets injured and you lack proper coverage, you become personally liable for medical bills and lost wages. This exposure can bankrupt a small restaurant operation.

Commercial Property and Equipment Coverage

Your building’s property insurance covers the structure, but it often excludes or limits coverage for specialized restaurant equipment like commercial refrigeration, ovens, and grills. If a fire destroys your $40,000 walk-in cooler, you’ll need specific equipment coverage to recover that cost. Point-of-sale systems have become critical infrastructure for modern restaurants, yet most owners don’t realize that standard property policies exclude cyber-related damage to these systems. A ransomware attack targeting your POS system can shut down operations for days while you rebuild, creating both direct costs and lost revenue.

Employment Practices Liability

Employment practices liability covers legal costs if an employee sues for wrongful termination, discrimination, or harassment. A single employment lawsuit can cost $25,000 to $100,000 in legal defense alone, regardless of whether you actually did anything wrong. Most restaurant owners never consider this coverage because they think employment lawsuits only happen to large corporations, but restaurants face employment claims regularly due to the high-turnover nature of the industry and the number of younger workers involved. The financial exposure here rivals your liquor liability risk, yet it receives far less attention from owners.

Final Thoughts

The gap between what you pay for restaurant insurance costs and what you actually need to pay shouldn’t exist. Most owners overpay because they haven’t shopped across multiple carriers or they’ve accepted coverage gaps that create real financial exposure. The restaurants paying the lowest premiums aren’t cutting corners on protection-they’re simply strategic about where they spend money and where they don’t.

Finding the right balance means addressing three things at once. First, prove to insurers that your restaurant operates safer than average through documented safety programs and staff training. Second, eliminate coverage gaps that could cost you tens of thousands of dollars, particularly liquor liability and employment practices liability. Third, work with an agent who represents multiple carriers instead of being locked into one company’s pricing.

Restaurant insurance costs feel complicated because most owners approach them in isolation, treating each policy as a separate expense rather than a coordinated strategy. When you bundle coverages, document your safety practices, and shop across carriers, your premiums drop while your actual protection improves. Contact Briggs Agency, Inc. to review your current coverage and get quotes from carriers that actively compete for restaurant business.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.