Commercial Property Insurance: Essentials for Indiana Businesses

Your building, equipment, and inventory represent significant investments. When disaster strikes-whether it’s a storm, theft, or unexpected business interruption-commercial property insurance protects what you’ve built.

At Briggs Agency, Inc., we help Indiana business owners understand their coverage options and find policies that match their actual needs. This guide walks you through what’s covered, the risks specific to our state, and how to choose the right protection for your operation.

What Your Policy Actually Covers

Commercial property insurance in Indiana protects three core areas of your business, and understanding exactly what falls under each one matters when you file a claim. Your building structure itself-the walls, roof, flooring, and permanent fixtures-receives coverage against damage from fire, wind, hail, theft, and vandalism. If a storm tears through your roof or a pipe bursts inside your walls, your policy pays for repairs or rebuilding. This protection applies whether you own the building outright or lease it, though landlords often require tenants to carry coverage on their own improvements and contents.

Equipment, Inventory, and Business Personal Property

Your equipment and inventory represent real money sitting in your operation every single day. Commercial property insurance covers machinery, tools, furniture, display cases, stockroom contents, and other business personal property up to the limits you select. If a fire destroys your kitchen equipment or theft clears out your inventory overnight, replacement cost coverage pays for brand-new items to get you back in business-not depreciated values. This matters significantly because actual cash value policies, which some insurers offer at lower premiums, only reimburse what your equipment was worth after years of use, leaving you short when rebuilding. Most policies cover items under five years old without restriction, though older equipment may face scrutiny. The average deductible for commercial property in Indiana hovers around $1,000, so selecting a higher deductible can reduce your premium if cash flow allows you to absorb that out-of-pocket cost.
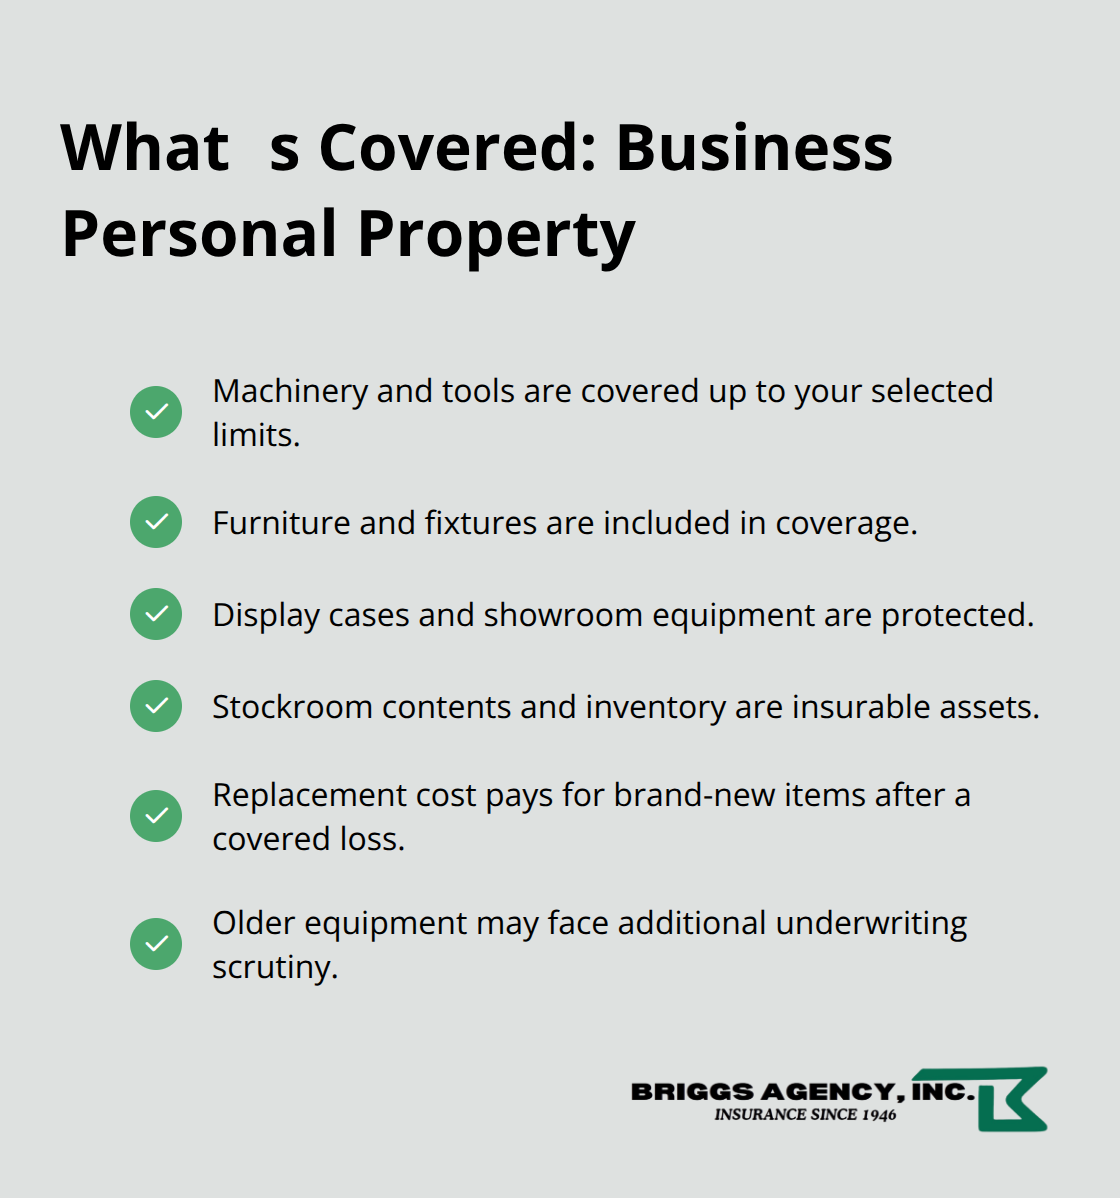
Key items covered under business personal property in Indiana - Commercial property insurance

When Your Business Can’t Operate

Business interruption coverage, sometimes called business income protection, steps in when a covered loss forces you to temporarily close your doors. If a water main breaks and floods your storefront, this coverage replaces the income you would have earned during repairs plus reasonable extra expenses like temporary relocation costs or employee payroll you must maintain. Without this protection, you absorb every dollar of lost revenue while still facing rent and overhead. Indiana businesses in high-traffic retail, restaurants, and service industries face particular risk here-a three-week closure can wipe out monthly profits. Most policies cover business interruption for the time it takes to repair or rebuild, though you’ll want to verify the waiting period your policy imposes before coverage kicks in.

Building Your Complete Protection Strategy

The three core protections work together, but your specific operation may need additional layers. High-risk sectors in Indiana-construction sites, farms, and healthcare facilities-typically benefit from specialized endorsements that extend beyond standard coverage. Tools and equipment that move between job sites or sit at locations you don’t own often require inland marine coverage to stay protected. A Business Owner’s Policy (BOP) bundles building coverage, business personal property, and business income into one package, and many small businesses find this approach delivers both comprehensive protection and cost savings. Your industry, location, building age, and claims history all influence what you pay, so comparing quotes from multiple carriers reveals significant differences in pricing and available options.

What Puts Indiana Businesses at Risk

Storm and Wind Damage: Indiana’s Most Common Threat

Indiana’s geography creates specific property threats that generic national policies often miss. Storm and wind damage ranks as the most common property claim in our state, with hail and tornado activity hitting hard during spring and early summer months.
Three most common Indiana property loss drivers

The National Weather Service data shows Indiana averages 22 tornadoes per year, and hail storms cause millions in dollars of damage to roofs, siding, and equipment each year. A single severe thunderstorm can destroy a metal roof or shatter storefront windows in minutes, leaving your operation exposed to further loss.

Water Damage from Aging Building Systems

Water damage from burst pipes ranks second among Indiana claims, particularly in older buildings where plumbing systems fail without warning. A pipe rupture in an unheated storage area or basement can saturate inventory and equipment before anyone notices, turning a $500 repair into a $50,000 loss. Your building’s age and condition directly influence claim likelihood. Older roofs, electrical systems, and HVAC units fail more often, triggering water damage and fire risks that insurers scrutinize closely when underwriting your policy. Insurers assess these factors carefully because aging infrastructure creates predictable loss patterns.

Theft and Vandalism Across Indiana Locations

Theft and vandalism plague Indiana businesses at rates that vary dramatically by location and industry. Urban areas like Indianapolis and Fort Wayne see higher rates of break-ins and smash-and-grab theft targeting electronics, tools, and merchandise. Rural operations face different risks-equipment theft from construction sites and farms happens frequently, especially when sites sit unattended overnight or during off-season months. Your location and the security measures you maintain both influence your premium and your actual loss exposure.

Liability Exposure Beyond Property Damage

Liability claims from customers or employees represent a separate but serious threat that commercial property insurance alone cannot handle. A customer slips on a wet floor and breaks their arm, then sues for medical bills and lost wages. An employee gets injured on the job and files a workers compensation claim that balloons beyond standard coverage limits. These situations demand general liability and workers compensation insurance working alongside your property protection. The Hartford reports that bundling property coverage with general liability through a Business Owner’s Policy costs small Indiana businesses approximately $141 per month on average, making comprehensive protection more affordable than carrying property coverage in isolation.

Industry-Specific Liability Risks

Your location and industry determine your actual liability exposure. High-traffic retail locations, restaurants with busy dining areas, and service businesses with clients visiting your premises face elevated slip-and-fall and injury risks. Construction sites present extreme liability exposure-equipment operation, working at heights, and machinery all create serious injury potential. Healthcare facilities and medical offices deal with patient liability claims at higher frequency than most industries. Understanding which liability scenarios pose genuine threats to your operation (rather than applying one-size-fits-all assumptions about your industry) helps you select the right coverage limits and endorsements. A local agent who understands Indiana’s business environment can identify these specific exposures and recommend protection that matches your actual operations.

How to Choose the Right Coverage for Your Business

Assess Your Property Value and Assets

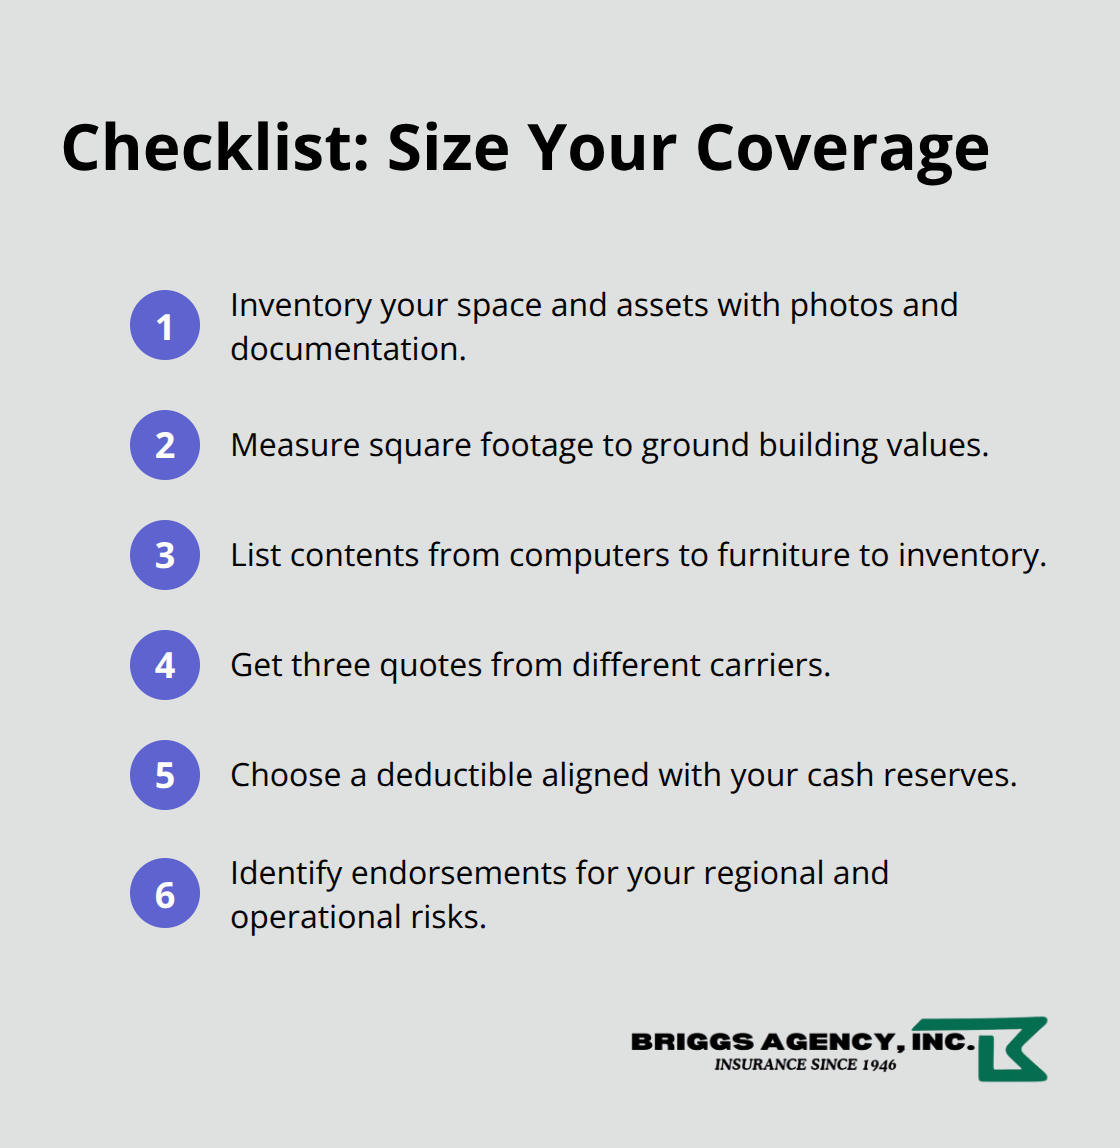
Start by walking through your facility with a notepad or camera and document everything that would cost money to replace. Most Indiana business owners underestimate their total property value, then face claim denials or partial payouts when loss strikes. Calculate the replacement cost of your building structure separately from your equipment and inventory.

If you own the building, you need coverage that reflects current construction costs in your area, not what you paid for it years ago. If you lease, your landlord’s policy protects the building shell, but you must cover your own improvements, fixtures, and contents. Next, list every piece of equipment your operation depends on, including items you might overlook: the security system, HVAC equipment, kitchen appliances, computers, machinery, and tools.

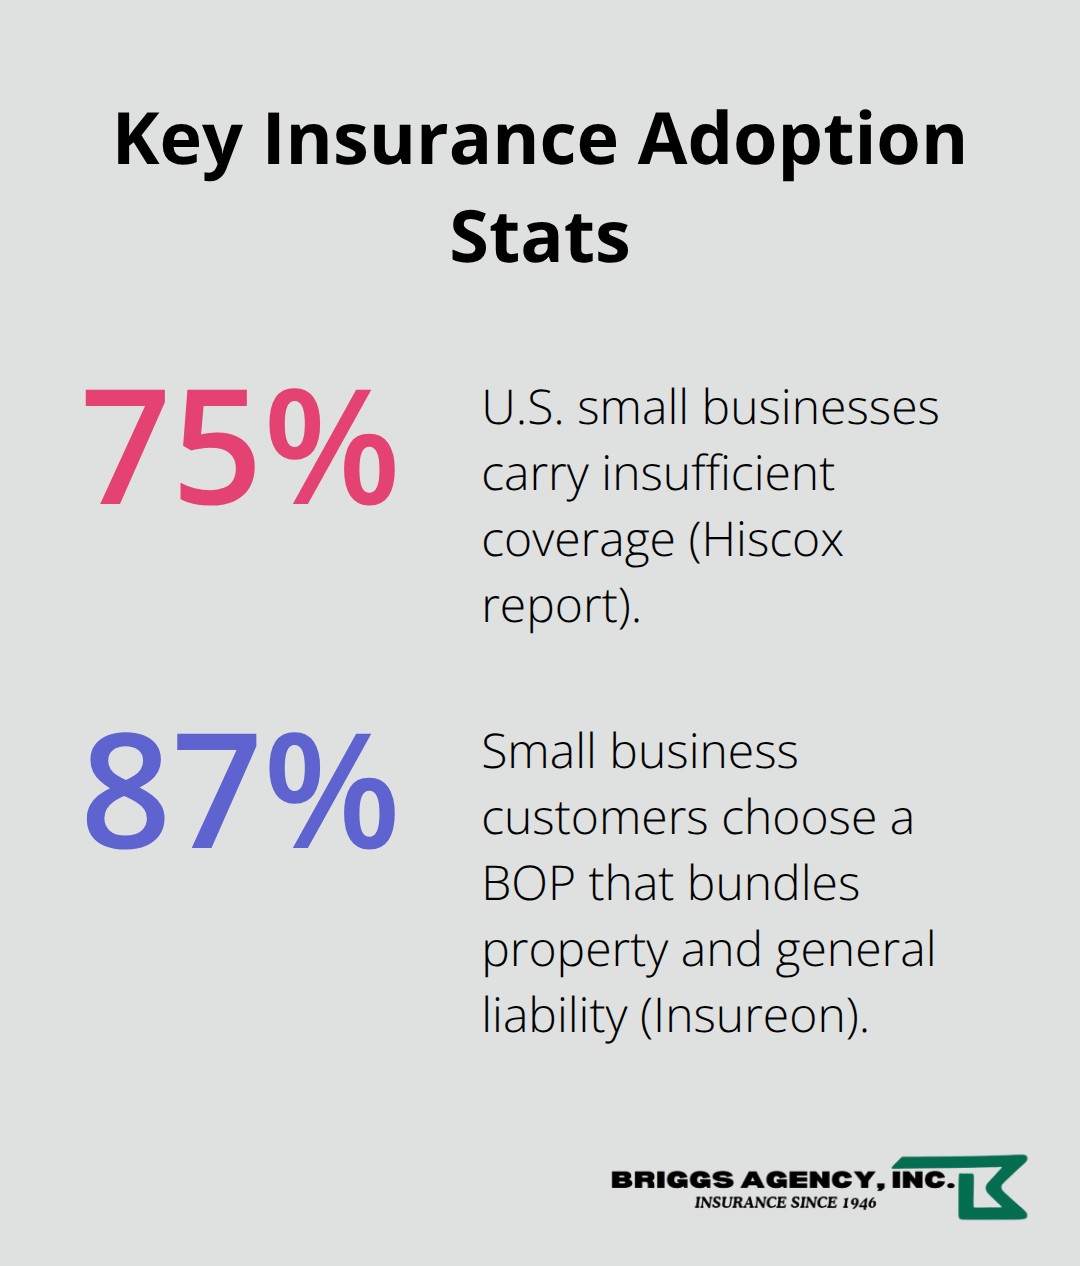
Inventory requires separate valuation because it fluctuates seasonally. A restaurant’s food stock differs vastly between summer and winter; a retail shop’s merchandise changes with seasons. Document peak inventory value, not average value, because that’s what you need to protect. Most Indiana businesses need between $250,000 and $2 million in business personal property coverage once they complete this exercise. The Hartford data shows that 87 percent of small business customers choose a Business Owner’s Policy with $1 million per occurrence and $2 million aggregate limits, which covers many operations adequately, but construction companies, manufacturers, and high-inventory retailers frequently need higher limits.
Share of small business customers opting for a BOP with standard limits - Commercial property insurance

Evaluate Industry-Specific Risks

Your industry determines which risks demand specialized attention beyond standard coverage. A restaurant faces kitchen fire exposure that a software consulting firm never encounters, so your premium and endorsement needs diverge dramatically. Construction businesses absolutely require builder’s risk coverage during active projects to protect unfinished work, materials, and equipment from fire, weather, and theft.

Farms need coverage for equipment stored at multiple locations plus livestock exposure. Healthcare facilities must address patient liability and specialized equipment protection. Tools and equipment that travel between job sites or sit in storage at locations you don’t own require inland marine coverage, not standard property policies. The Hartford’s average small business customer pays about $141 per month for a BOP, but restaurants and gas stations typically pay 40-60 percent more due to kitchen fire and fuel explosion risks, while IT consulting firms pay substantially less.

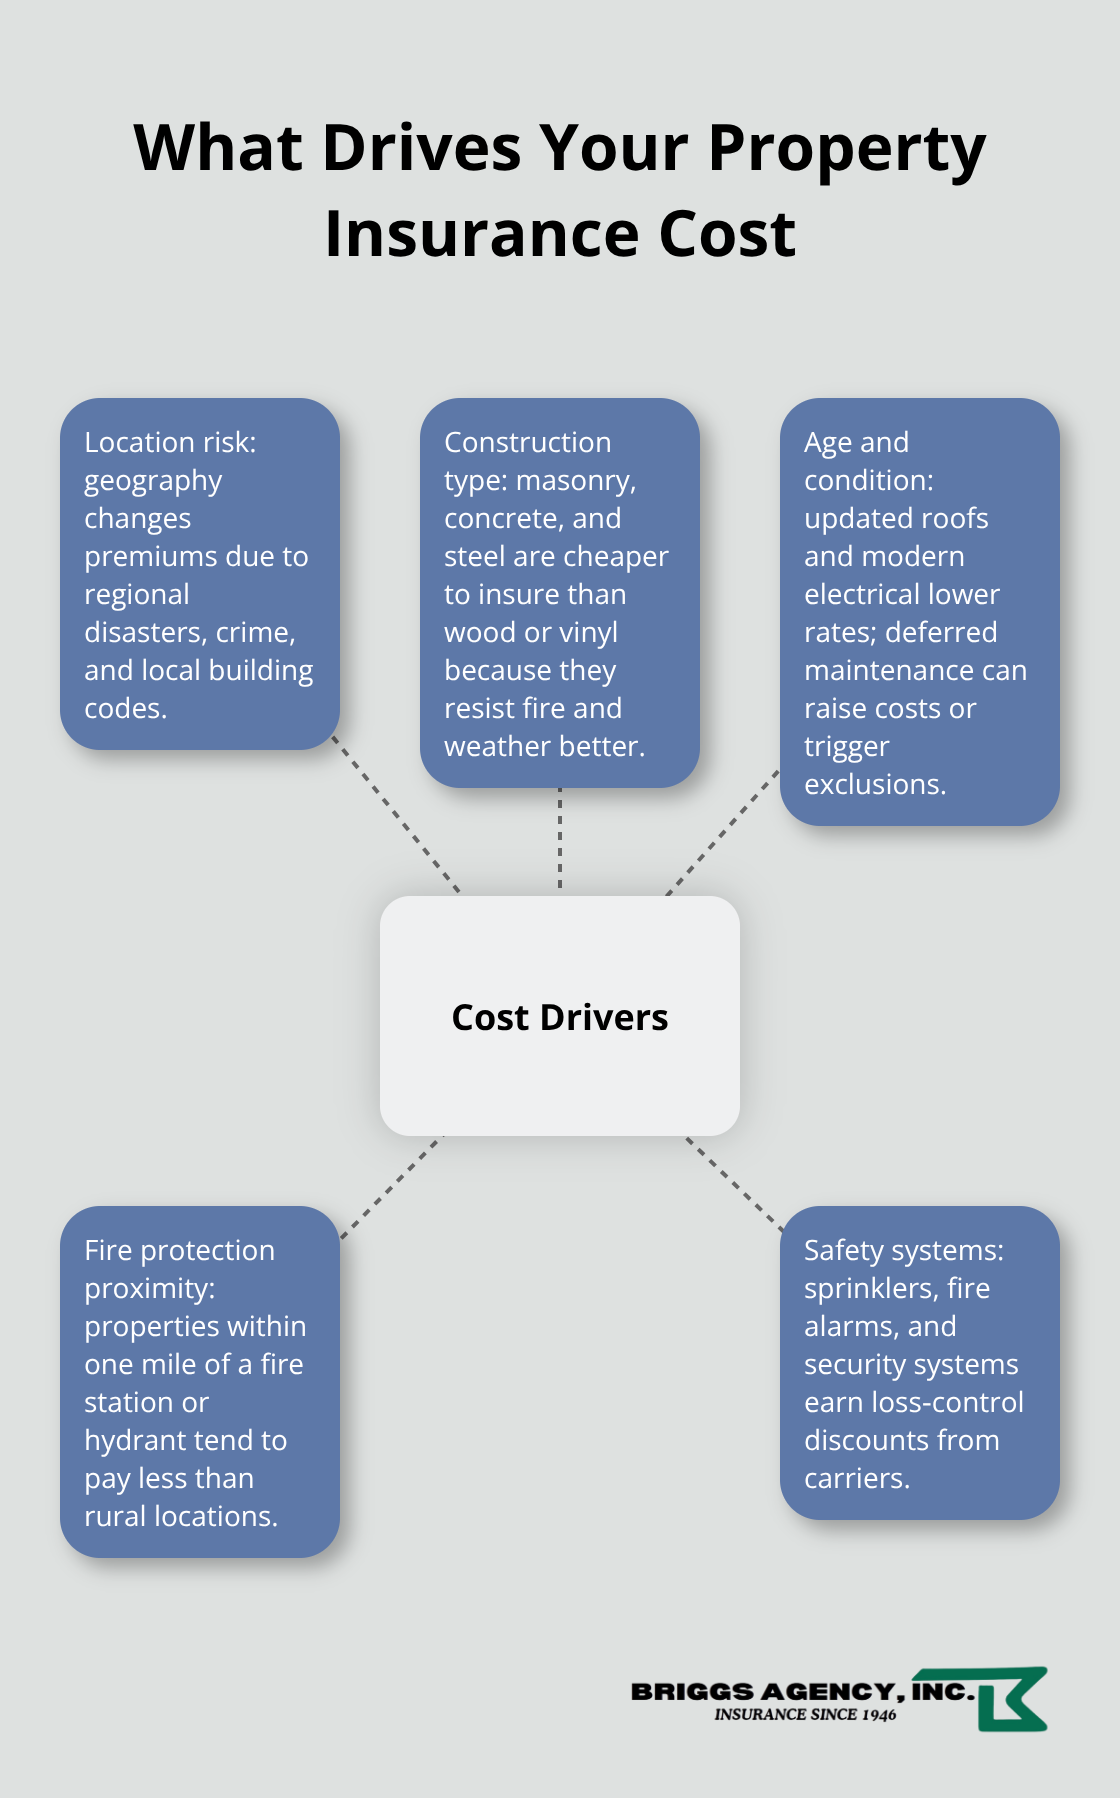
Your location matters equally: an Indianapolis storefront in a high-crime area costs more to insure than an identical operation in a lower-crime suburb. Older buildings with outdated electrical, plumbing, or roofing systems face higher premiums because failure rates climb dramatically after systems reach 25-30 years old.

Work with a Local Agent to Customize Your Policy

A local agent who understands Indiana’s business environment identifies which endorsements actually protect your operation versus which ones represent unnecessary expense for your particular situation. At Briggs Agency, Inc., our experienced local agents compare options across multiple top-rated carriers and tailor policies to deliver competitive pricing and the right protection for your specific needs. We help Indiana business owners understand their actual exposure and match coverage limits to what you own and operate, not to generic industry assumptions.

Final Thoughts

Commercial property insurance protects the assets you’ve worked hard to build, but only when you understand what your policy actually covers and whether those protections match your real operation. The three core components-building structure, business personal property, and business interruption coverage-form the foundation of protection that Indiana businesses need. Storm damage, water loss, theft, and liability exposure create genuine financial threats across our state, and standard policies leave gaps that specialized endorsements fill.

A national online quote tool cannot account for Indiana’s tornado frequency, aging building stock in older commercial districts, or the specific liability exposure your operation faces. We at Briggs Agency, Inc. compare options across multiple top-rated carriers and tailor policies to deliver both competitive pricing and genuine protection. Our experienced local agents understand the difference between a restaurant’s kitchen fire exposure and a consulting firm’s liability profile, between a construction site’s builder’s risk needs and a retail operation’s inventory protection requirements.

Contact Briggs Agency, Inc. to discuss your property, assets, and actual business risks. We’ll help you build a protection strategy that covers what matters most without paying for unnecessary coverage. Commercial property insurance safeguards your business’s financial future when loss strikes.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Apartment Owner Insurance: Protecting Your Multiunit Investments

Owning a multiunit apartment building comes with significant financial exposure. Standard homeowners policies won’t cover the unique risks you face as a landlord.

Apartment owner insurance fills that gap by protecting your building, your tenants, and your rental income. At Briggs Agency, Inc., we help property owners understand what coverage they actually need and how to avoid costly gaps in protection.

What Apartment Owner Insurance Actually Covers

The Core Protection Your Multiunit Property Needs

Apartment owner insurance is a specialized commercial property policy built specifically for multiunit residential buildings. Unlike homeowners insurance, which assumes you live in the property, apartment owner insurance recognizes that you operate a rental business with tenants, common areas, and income streams that require protection. The policy typically covers building structure and common areas, liability protection, and loss of rental income, among other elements.

Key coverages landlords rely on in a U.S. apartment owner policy - Apartment owner insurance

Building and System Coverage

Standard policies from carriers like State Farm and Liberty Mutual include fire, wind, hail, theft, and vandalism coverage on the building itself. Water damage coverage extends to burst pipes and HVAC leaks but excludes flood damage, which requires a separate rider. Most policies also cover building systems like boilers and HVAC equipment, plus landlord-owned appliances and furniture used in the rental business.

Liability and Income Protection

Liability coverage in apartment policies typically ranges from $300,000 to $2,000,000 and covers medical expenses and legal costs when a tenant or visitor suffers injury due to property conditions or negligence. Loss of rental income protection reimburses you for income lost while units undergo repairs after a covered loss, which is critical for maintaining cash flow and meeting mortgage obligations.

What Drives Your Premium Costs

The cost of apartment owner insurance varies significantly by location and property characteristics. Annual premiums typically range from $1,000 to $3,000 per million dollars of coverage, meaning a 10-unit building might cost $3,000 to $6,000 annually while a 20-unit property could run $6,000 to $12,000 per year. Location matters enormously: Florida and California properties cost substantially more due to hurricane and flood exposure, while properties in low-disaster areas pay less.

Main factors affecting premium costs for U.S. apartment owners

Building age is another major driver-older structures with outdated wiring or plumbing face higher premiums or coverage restrictions. Installing security systems, fire detection devices, and sprinkler systems can lower your costs by a meaningful margin. Your claims history also affects pricing; properties with frequent damage or liability claims will pay more. Short-term rentals like Airbnb properties cost significantly more to insure than long-term rentals because the higher turnover and guest volume increase liability exposure.

Getting the Right Quote for Your Property

Multiple carriers assess risk differently, so quotes from different insurers can vary considerably for the same property. Comparing quotes from several carriers reveals how underwriting standards and risk assessments differ between companies. The specific details of your building-its age, location, safety features, and rental model-all influence which carrier offers the best rate and coverage fit for your situation.

What Actually Gets Covered in Your Multiunit Policy

Building Structure and Systems

Your apartment owner policy protects three distinct areas of your investment, and understanding where each type of coverage applies prevents nasty surprises when you file a claim. The building structure itself-walls, roof, floors, and permanent fixtures-receives coverage under standard policies, along with systems like boilers, HVAC units, and electrical wiring. Common areas including hallways, lobbies, laundry facilities, and exterior structures also fall under this protection.

Water damage coverage specifically addresses burst pipes, frozen lines, and HVAC leaks, though it excludes flood damage entirely. If your property sits in a flood zone, you need a separate flood rider. Landlord-owned appliances, furniture, and equipment used for the rental business all receive coverage, but tenant personal belongings do not-that’s why pushing tenants toward renters insurance protects both parties.

Age and Location Restrictions

In high-risk areas like Florida or California, carriers often impose stricter requirements on older buildings. A property built before 1980 with original plumbing might face coverage limitations or higher deductibles unless you upgrade systems first. These restrictions exist because older infrastructure carries higher risk of failure and costly claims.

Liability Coverage for Injuries and Accidents

Liability coverage in your policy typically ranges from $300,000 to $2,000,000 and covers medical bills, legal defense costs, and settlements when a tenant or visitor gets injured on your property due to negligence or unsafe conditions. This is where most landlords face real exposure-a slip-and-fall lawsuit or injury from faulty stairs can easily exceed $100,000 in legal and medical costs alone.

Loss of Rental Income Protection

Loss of rental income protection reimburses you for rent you’d normally collect while units sit empty during repairs after a covered loss. If a fire damages three units in your ten-unit building, this coverage replaces that lost income while reconstruction happens. This matters more than most owners realize because your mortgage, property taxes, and insurance don’t pause while repairs happen-loss of income coverage prevents you from depleting reserves or taking on debt to cover obligations. Properties in disaster-prone regions benefit most from this coverage. Understanding these three coverage pillars helps you assess whether your current policy truly protects your investment or leaves gaps that could cost you thousands when disaster strikes.

Choosing the Right Coverage for Your Specific Building

Understand What Makes Your Property Unique

Finding apartment owner insurance that actually fits your property requires moving beyond generic quotes and understanding what makes your building unique. A 10-unit complex in Indianapolis faces entirely different risks than a 10-unit building in Miami, yet many property owners treat insurance shopping as a commodity purchase rather than a critical business decision. Your building’s age, location, safety features, tenant profile, and rental model all affect which carrier offers the best combination of price and protection.

Document Your Property’s Specifics

Start by documenting your property’s specifics: construction year, number of units, square footage, roof condition, presence of security systems, and whether you operate long-term or short-term rentals. Properties built before 1980 with original plumbing and wiring typically face higher premiums or coverage restrictions, so knowing your building’s systems matters. If you’ve made recent upgrades like installing fire detection devices or sprinkler systems, these reduce your premium meaningfully-sometimes by 10 to 15 percent depending on the carrier. Your claims history over the past three to five years also influences pricing significantly; properties with multiple claims pay substantially more than those with clean records.

Actionable steps that may lower U.S. apartment owner insurance costs

Request Quotes from Multiple Carriers

Getting actual quotes requires contacting multiple carriers because underwriting standards vary dramatically. State Farm, Liberty Mutual, Farmers Insurance, Steadily, and Travelers all assess the same property differently based on their risk models and appetite. Request quotes from at least three carriers using identical property information so comparisons stay apples-to-apples. Ask each carrier specifically about their requirements for older buildings, their flood and earthquake rider costs, and what discounts apply to your situation-bundling landlord and homeowners policies often saves 10 to 20 percent.

Compare Coverage Details, Not Just Price

When you review quotes, examine the liability limits, deductible amounts, and what’s actually included versus excluded. A policy quoting $2,200 annually with $500,000 liability and a $1,000 deductible differs significantly from one at $2,100 with $300,000 liability and a $2,500 deductible. Work with an agent who understands your local market and can explain why one carrier’s quote differs from another’s, rather than simply choosing the lowest price. Your agent should also stress-test your coverage against realistic scenarios-if a fire damages half your units, would your loss of income coverage hold up, or would you face gaps? This conversation prevents costly surprises when you actually need your insurance to work.

Final Thoughts

Apartment owner insurance protects your multiunit investment from financial disaster in ways that standard homeowners policies simply cannot. A single liability claim can exceed six figures, a fire can eliminate months of rental income, and building damage can force you to tap reserves or take on debt while repairs happen. Your coverage must reflect the unique risks that come with operating a rental business across multiple units, not some generic template that ignores your specific property.

The right policy covers your building structure, protects you against liability claims from tenant injuries, and replaces lost income when a covered event makes units uninhabitable. Getting there requires moving beyond generic quotes and actually understanding what your specific property needs-a 10-unit building in Indiana faces different risks than one in Florida. Document your property’s details (age, location, safety features, and rental model), request quotes from multiple carriers using identical information, and examine liability limits, deductibles, and what’s actually covered versus excluded when you review those quotes.

At Briggs Agency, Inc., our experienced agents represent multiple top-rated carriers and can compare options to find apartment owner insurance that actually fits your building and your budget. We’ve served property owners and businesses in our community since 1946, and we know what it takes to protect multiunit investments properly. Contact us to discuss your coverage needs with someone who understands your local market.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Apartment Building Insurance: Comprehensive Coverage for Landlords

Owning an apartment building comes with real financial exposure. One unexpected event-a tenant injury, a fire, or months of vacancy-can wipe out years of profit.

At Briggs Agency, Inc., we’ve seen landlords face devastating losses because they didn’t have the right apartment building insurance in place. The good news is that proper coverage protects your investment and gives you peace of mind.

What Your Apartment Building Insurance Actually Protects

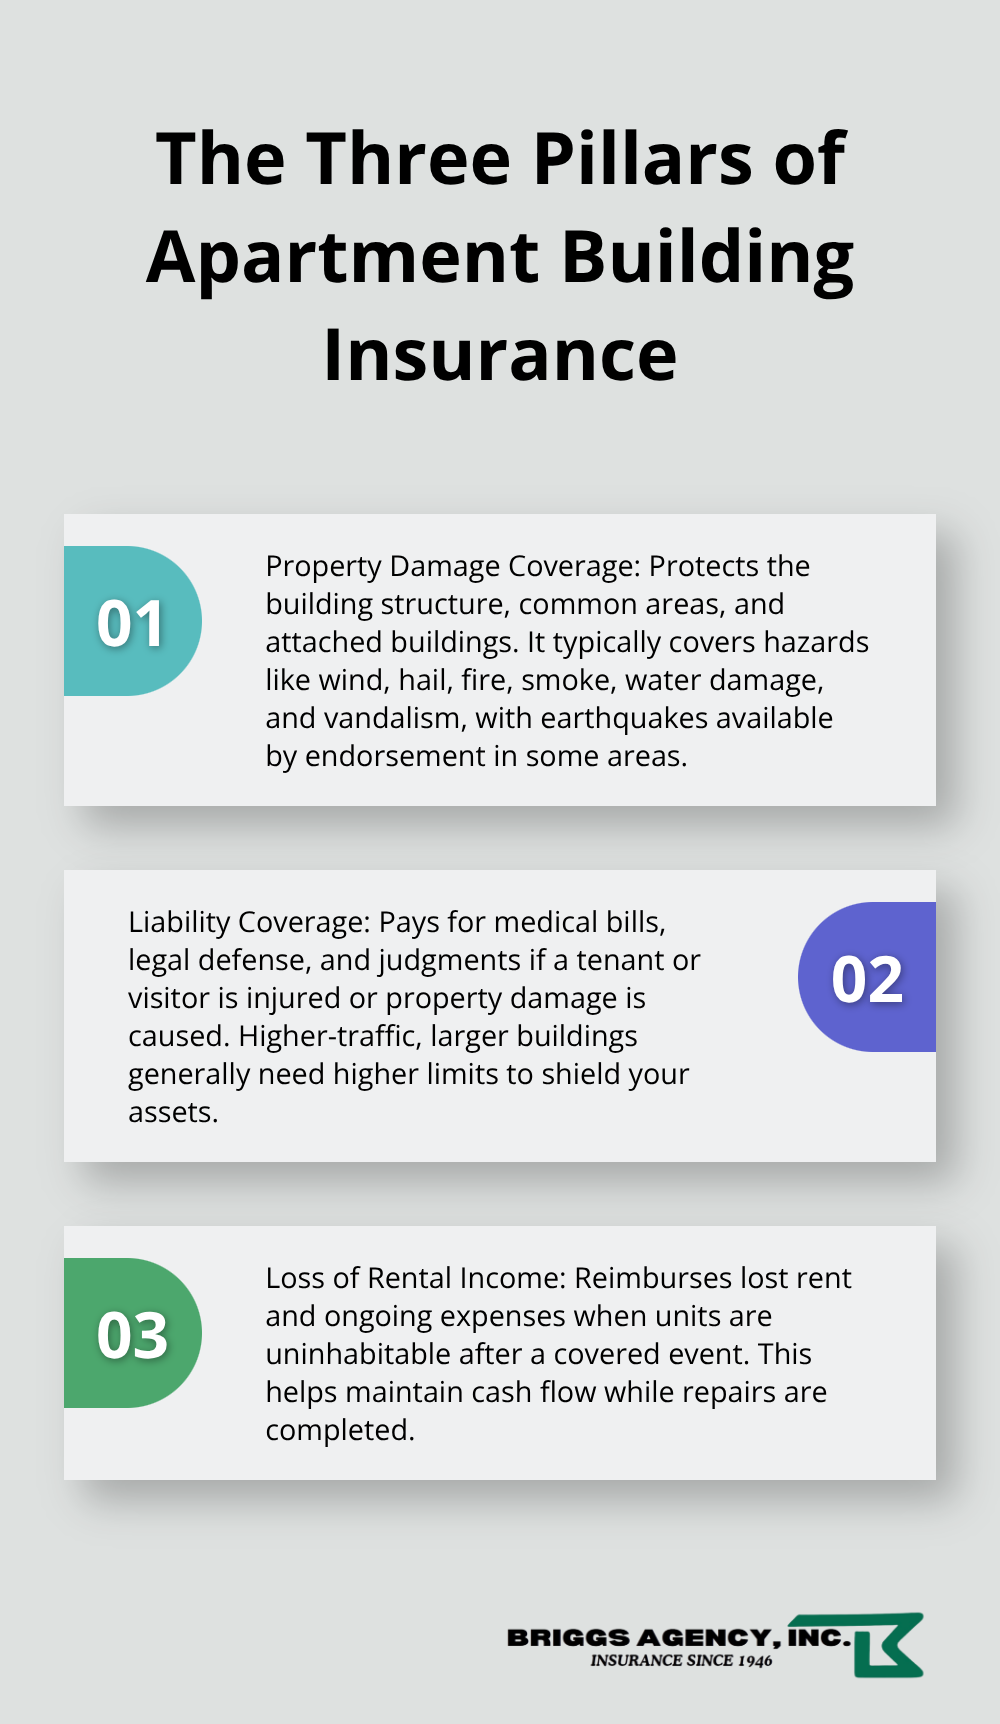
Apartment building insurance combines three essential protections that standard homeowners policies simply don’t cover. Property damage coverage protects the physical structure, common areas like hallways and parking lots, and attached buildings such as storage sheds or garages.

Infographic outlining property damage, liability, and loss of rental income protections for apartment buildings in the United States. - Apartment building insurance

This covers perils including wind, hail, fire, smoke, water damage, vandalism, and sometimes earthquakes if you add them as an endorsement. Liability coverage handles medical expenses, legal fees, and court judgments when a tenant or visitor gets injured on your property or when you cause damage to someone else’s property. Loss of rental income coverage reimburses you for lost rent and ongoing expenses like mortgage payments, property taxes, and staff wages when your building becomes uninhabitable due to a covered event. According to Federal Reserve research, property insurance costs for multifamily buildings rose from about $39 per unit monthly in 2019 to about $68 per unit in 2024-a 75% increase-making it essential to understand exactly what you’re paying for and what gaps remain.

Property Damage Coverage Requires the Right Limits

Your building’s replacement cost should be your coverage limit, not its market value. If your apartment building would cost $2 million to rebuild from scratch, your property coverage limit should reflect that full amount. Many landlords underestimate reconstruction costs and end up short after a total loss. Water backup coverage is a separate endorsement worth adding if your building has basement systems or drainage vulnerabilities, since standard policies exclude sewer backups and clogged drains. Flood coverage is not included in any standard apartment building policy and must be purchased separately through the National Flood Insurance Program or private carriers. If you’re in a coastal or flood-prone area, excess flood coverage beyond NFIP limits often makes sense for larger multifamily properties. Earthquake coverage is another separate purchase in areas where seismic risk exists.

Code Upgrades and Ordinance Coverage Matter

Enhanced ordinance and law coverage reimburses costs to bring your building up to current code after a loss, including upgrades to undamaged portions, demolition expenses, and increased construction costs. This matters especially in older buildings where code changes are substantial. Without this endorsement, you pay out of pocket to meet new building codes, which can add tens of thousands of dollars to your repair bill.

Liability Protection Shields Your Assets

Liability coverage protects you when a visitor slips on ice in your parking lot or when your negligence causes injury. Medical expenses from a single incident can easily reach $100,000, and legal defense costs add significantly to that. Your policy should reflect the size and occupancy of your building; a 50-unit building needs higher liability limits than a 10-unit property. Require your tenants to carry renters insurance with appropriate liability extensions; this protects their personal property and creates a second layer of liability protection for your building. If tenants cause damage, their insurance may cover it rather than your policy, reducing your claims and protecting your premium history.

Loss of Rental Income Prevents Cash Flow Collapse

Loss of rental income coverage becomes your financial lifeline when fire, severe weather, or other covered events make units uninhabitable. If repairs take four months, this coverage replaces the rent you would have collected, preventing a cash flow crisis. Many landlords skip this coverage or buy limits too low, then face months of financial strain when a major event occurs. This protection also covers ongoing expenses like mortgage payments and property taxes during the repair period, not just lost rent.

Understanding what your policy covers is only half the battle. The real challenge lies in identifying which risks your current coverage leaves exposed-and that’s where many landlords discover costly gaps.

What Gaps in Coverage Actually Cost Landlords

Inadequate apartment building insurance leaves you exposed to three categories of loss that can severely damage your finances. Tenant-caused damage represents a blind spot many landlords overlook. Standard apartment building policies do not cover damage that tenants cause, which means if a tenant deliberately punches a hole through drywall, floods a unit through negligence, or causes structural damage, you absorb the full cost. Your only recourse is pursuing the tenant in small claims court, which rarely recovers the full amount and consumes time you don’t have. This gap explains why requiring renters insurance with damage liability extensions is non-negotiable. When a tenant’s renters policy covers their negligence, your building policy stays protected and your claims history remains clean. Without this requirement in your lease, a single tenant incident can cost you $5,000 to $25,000 in uninsured repairs depending on the damage type.

Vacancy Gaps Drain Cash Flow Faster Than You Expect

Vacancy gaps create another financial drain that many landlords underestimate. If a covered event makes units uninhabitable and your loss of rental income coverage has a low limit or short benefit period, you’ll face months where rent stops but your mortgage, taxes, and maintenance expenses continue. This makes every dollar of coverage matter, yet many policies limit loss of rental income to 6 or 12 months when major reconstruction can take longer. Set your benefit period to match realistic repair timelines for your building’s age and condition to prevent this cash flow catastrophe.

Liability Limits Can Leave You Personally Exposed

Lawsuits from injuries or accidents on your property can exceed your liability coverage limits faster than most landlords expect. A single slip-and-fall injury requiring surgery and ongoing physical therapy easily generates $150,000 in medical costs plus legal defense expenses. If your liability limit sits at $300,000 and the injured party’s attorney pursues a $500,000 judgment, you personally cover the gap above your policy limit. Liability limits should reflect the size and traffic patterns of your property. For example, general liability insurance can cover you in the event that someone gets injured on your property due to negligence and sues you.

Natural Disasters and Weather Leave Predictable Gaps

Natural disasters and weather-related losses hit differently depending on your location and what you’ve actually purchased. Flood damage alone costs billions annually across the United States, yet standard policies exclude all flood losses. If your building sits in a flood-prone ZIP code or even a moderate-risk area, NFIP coverage capping at $500,000 for structures with five or more units may fall short on a larger property. Coastal properties face hurricane wind and hail damage, which drives premium increases but still leaves gaps if your ordinance and law coverage is weak. Earthquake coverage does not exist in standard policies anywhere, meaning a seismic event in California or other active zones leaves your building unprotected unless you purchase it separately.

The Cost of Discovering Gaps Too Late

Most landlords discover these gaps only after experiencing a loss, when the cost of learning becomes permanent financial damage. The question isn’t whether your building will face one of these risks-it’s when. Understanding which specific gaps apply to your property and your location allows you to close them before a loss occurs.

How to Choose the Right Apartment Building Insurance Policy

Calculate Your Building’s True Replacement Cost

Start with your building’s actual replacement cost, not its market value or purchase price from years ago. Reconstruction costs have climbed sharply alongside insurance premiums. If your 20-unit building sold for $1.8 million but would cost $2.4 million to rebuild to code with current labor and materials, your property coverage limit must be $2.4 million. Underinsuring by even 10 percent means you absorb reconstruction costs above your limit after a total loss. Contact local contractors or use replacement cost calculators specific to your building’s age, materials, and square footage to establish an accurate figure. Once you know your replacement cost, you can set appropriate coverage limits across all policy sections.

Set Liability and Loss of Income Limits to Match Your Exposure

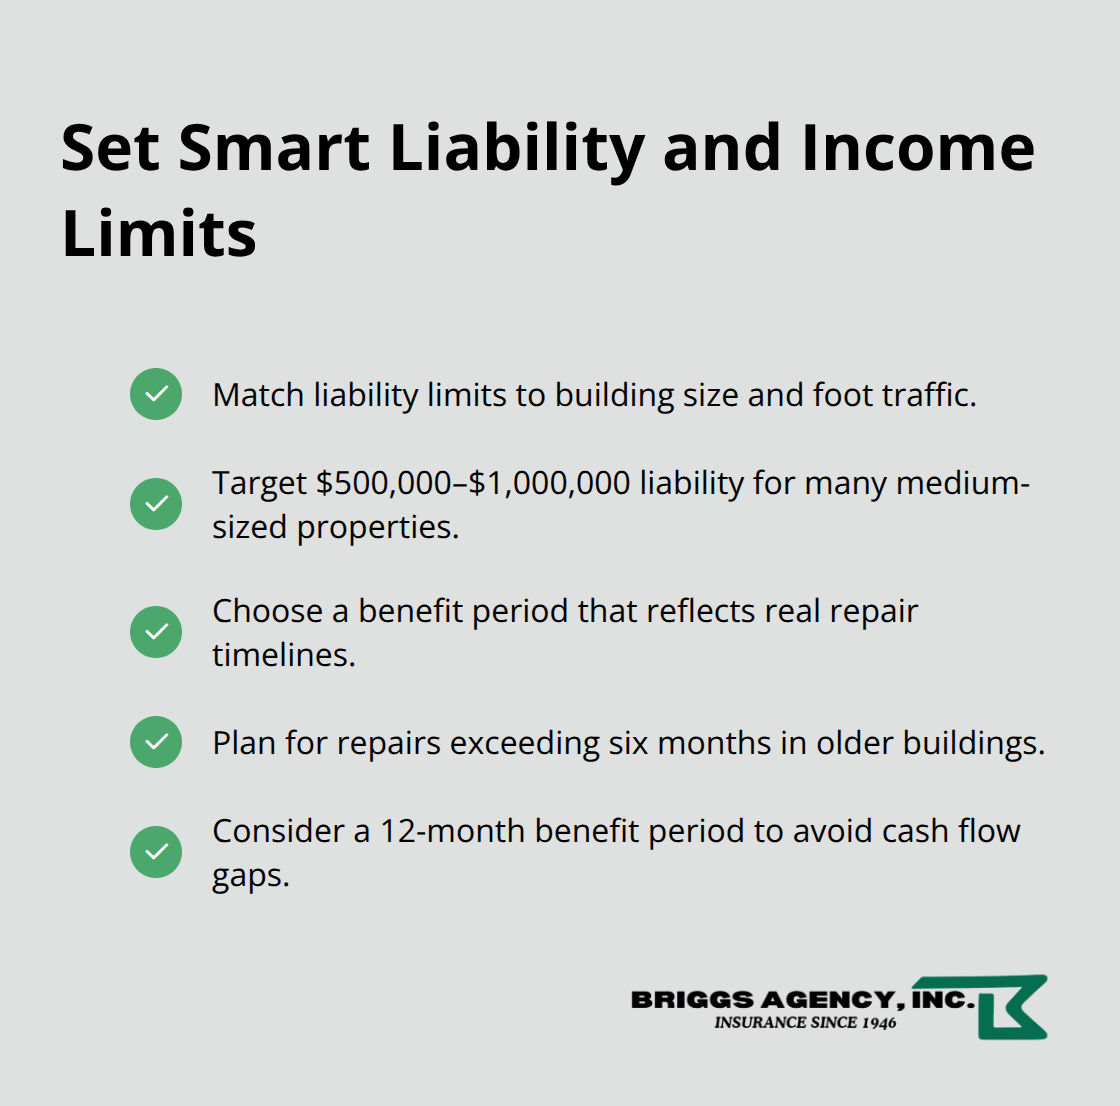
Determine your liability limits based on occupancy and traffic patterns. A 50-unit building with common areas, parking facilities, and regular foot traffic warrants higher liability limits than a smaller property. Most landlords carrying $300,000 in liability coverage are underprotected; $500,000 to $1 million is more realistic for medium-sized multifamily properties. Set your loss of rental income benefit period to match how long repairs realistically take for your specific building. If your structure is 40 years old and major damage occurs, reconstruction easily extends beyond six months. A 12-month benefit period protects against this common gap.

Checklist of actions for U.S. landlords to set appropriate liability and loss of rental income limits for apartment buildings. - Apartment building insurance

Add endorsements for water backup, ordinance and law coverage, and flood insurance if your location warrants it. Flood coverage is non-negotiable in moderate or high-risk zones since almost one third of NFIP claims come from areas located outside of high-risk areas, meaning many landlords in supposedly safe zones still face losses.

Compare Quotes Using Identical Coverage Parameters

Comparing quotes from multiple carriers reveals dramatic pricing differences for identical coverage. Request quotes from at least three carriers using the same coverage limits, deductibles, and endorsements so you can compare apples to apples. Insurance costs for apartment buildings rose 75 percent between 2019 and 2024 according to Federal Reserve research, but regional variation is extreme. ZIP code factors explain more than 42 percent of cost variation, meaning your specific location drives pricing far more than national trends.

Percentage chart showing the rise in multifamily insurance costs and the impact of ZIP code factors in the U.S.

A property in coastal Texas or Florida pays vastly more than an identical building inland. Test different deductible levels, since raising your deductible from $1,000 to $2,500 or $5,000 can significantly lower premiums while keeping your out-of-pocket exposure manageable.

Partner with a Local Independent Agent

Work with a local independent agent who represents multiple carriers rather than a captive agent locked into one company. Independent agents access non-admitted carriers when standard markets tighten or refuse to renew policies, a critical advantage given the current Texas and coastal insurance environment. A local agent also monitors your policy annually, catching coverage gaps before losses occur and renegotiating rates when markets shift in your favor. At Briggs Agency, Inc., we serve Indiana landlords with comprehensive coverage options tailored to your specific property rather than offering a one-size-fits-all approach. Our experienced local agents compare options across multiple top-rated carriers to deliver competitive pricing and hands-on service that helps you reduce risk and safeguard your investment.

Final Thoughts

Apartment building insurance protects your investment from property damage, liability claims, and lost rental income-the three risks that destroy landlord finances. Without proper coverage, a single event eliminates years of profit and leaves you personally liable for costs exceeding your policy limits. The landlords we work with at Briggs Agency, Inc. understand that adequate coverage forms the foundation of sustainable property ownership.

Calculate your building’s true replacement cost using current construction prices in your area, then set realistic liability limits based on your property’s size and occupancy. Determine your loss of rental income benefit period to match how long repairs actually take for a building of your age and condition, and add endorsements for water backup, ordinance and law coverage, and flood insurance if your location requires it. Request quotes from at least three carriers using identical coverage parameters so you can compare pricing fairly-ZIP code factors drive more than 42 percent of cost variation, meaning your specific location matters far more than national trends.

Work with a local independent agent who represents multiple carriers rather than being locked into one company. An independent agent accesses non-admitted carriers when standard markets tighten, monitors your policy annually for gaps, and renegotiates rates when market conditions shift. Contact Briggs Agency, Inc. to discuss apartment building insurance options tailored to your specific property and receive competitive quotes from multiple top-rated carriers.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Truckers Liability Insurance: Protecting Your Driving Team

One accident can devastate a trucking business financially. At Briggs Agency, Inc., we’ve seen how quickly a single liability claim can threaten operations and drain resources.

Truckers liability insurance isn’t optional-it’s the foundation of responsible fleet management. This guide walks you through what coverage actually protects you, why it matters legally, and how to select the right policy for your operation.

What Truckers Liability Insurance Actually Covers

Truckers liability insurance protects you when someone else gets hurt or their property gets damaged because of your trucking operations. This coverage pays for medical bills, lost wages, and property repairs when a third party files a claim against you. If you haul freight for a customer and your truck damages their loading dock, or if a passenger gets injured at a truck stop while you work, liability insurance covers those costs. The coverage includes bodily injury claims, which handle medical expenses and ongoing care, and property damage claims, which reimburse for damaged vehicles, buildings, equipment, or other assets. Without this protection, a single accident costs you tens of thousands of dollars out of pocket. Federal Motor Carrier Safety Administration requirements mandate that interstate truckers carry liability coverage, with minimums varying based on cargo type and vehicle weight. Even local operators face state-level requirements, so compliance isn’t optional.

Who Pays When Accidents Happen

When an accident occurs, your liability policy covers legal defense costs and settlement payments on your behalf. If someone sues you for injuries or property damage, the insurance company provides an attorney and handles court proceedings, which typically cost $10,000 to $50,000 or more depending on case complexity. You avoid paying these expenses directly from your business account. The policy also covers settlements and judgments up to your coverage limits. For example, if a truck accident injures three people and damages property, your bodily injury coverage pays medical costs while property damage coverage handles vehicle and building repairs.

Hub-and-spoke showing legal defense, bodily injury, property damage, settlements, and coverage limits. - Truckers liability insurance

Your coverage limits matter enormously here. A combined single limit sets the maximum payout per incident, so if you carry $1,000,000 in coverage and damages exceed that amount, you pay the difference. Selecting adequate limits based on your cargo value and route density protects your business from catastrophic exposure.

Third-Party Injury Claims Create Real Exposure

Third-party injury claims arise from accidents where your truck causes harm to someone else’s body or property. If your truck collides with another vehicle, the other driver’s medical bills and vehicle repairs fall under your liability coverage. If you make a delivery and someone slips on wet pavement at a customer’s loading dock, that person’s injury claim becomes your responsibility. Cargo-related incidents create additional exposure. If your truck’s cargo shifts during transit and damages a customer’s production equipment, your liability coverage protects you. These scenarios occur regularly in trucking. Heavy truck accidents cause significantly greater damage than standard vehicle crashes due to weight and size differences, making liability claims more expensive and more likely to exceed basic coverage limits. Operating in congested areas, making frequent stops, or hauling high-value cargo increases your exposure to third-party claims. This is why many shippers, including major carriers like FedEx and Amazon, require drivers to carry specific liability minimums before accepting loads. Understanding your actual risk exposure based on your routes, cargo types, and customer requirements helps you select coverage limits that actually protect your business. The right policy prevents gaps that could leave you financially vulnerable when an accident happens.

Why Truckers Need Liability Insurance

Federal law mandates that interstate truckers carry liability coverage, with minimums set by the Federal Motor Carrier Safety Administration based on cargo type and vehicle weight. In-state operations face their own state-level requirements, and many major shippers including FedEx and Amazon require carriers to maintain specific liability minimums before accepting loads. Operating without mandated coverage means fines, loss of operating authority, and personal liability exposure. Beyond legal compliance, a single accident exposes your business to financial devastation that no owner-operator can absorb alone.

A moderate truck accident involving two vehicles and three injured people easily generates $500,000 to $2 million in combined medical costs, lost wages, vehicle repairs, and property damage. Without liability insurance, you pay these costs directly from business revenue or personal assets. Courts can garnish future earnings and freeze business accounts to satisfy judgments, effectively shutting down operations. Progressive’s 2025 analysis shows national average monthly premiums for commercial truck insurance range from $734 for specialty truckers to $926 for transport truckers, making the cost of coverage modest compared to the financial exposure of a single claim.

Cargo Claims Create Substantial Exposure

Cargo-related liability incidents represent a distinct category of exposure that many owner-operators underestimate. If your truck’s cargo shifts during transit and damages a customer’s production equipment, your liability coverage pays the claim. If you make a delivery and your cargo damages the customer’s loading dock or storage facility, that damage falls under your policy. Shippers frequently require proof of liability coverage specifically because cargo incidents happen regularly and costs mount quickly.

A damaged manufacturing line can cost tens of thousands per hour in lost production, and your liability policy must cover that exposure. Heavy truck accidents cause substantially greater damage than standard vehicle crashes due to weight and size, making cargo-related claims more expensive. Your operating radius and cargo type directly affect your actual exposure level.

How Your Routes and Cargo Mix Determine Coverage Needs

Regional and interstate routes with high-value cargo carry significantly higher liability risk than local operations with standard freight. Assessing your specific cargo mix, delivery locations, and customer requirements reveals your true exposure and helps determine appropriate coverage limits. The right coverage limit protects your business when accidents happen; inadequate limits leave you financially vulnerable despite carrying a policy.

Understanding these exposure factors positions you to select coverage that actually matches your operation. The next section walks you through how to evaluate your specific needs and choose a policy that protects your driving team and business.

How to Choose the Right Coverage Limits for Your Operation

Selecting adequate coverage limits starts with calculating your actual financial exposure based on cargo value, vehicle weight, and operating geography. If you haul high-value equipment or operate in densely populated areas with frequent stops, your exposure climbs significantly compared to long-haul dry freight on interstate highways. Progressive’s 2025 analysis shows monthly premiums range from $734 for specialty truckers to $926 for transport truckers, reflecting how cargo mix and routes drive risk assessment.

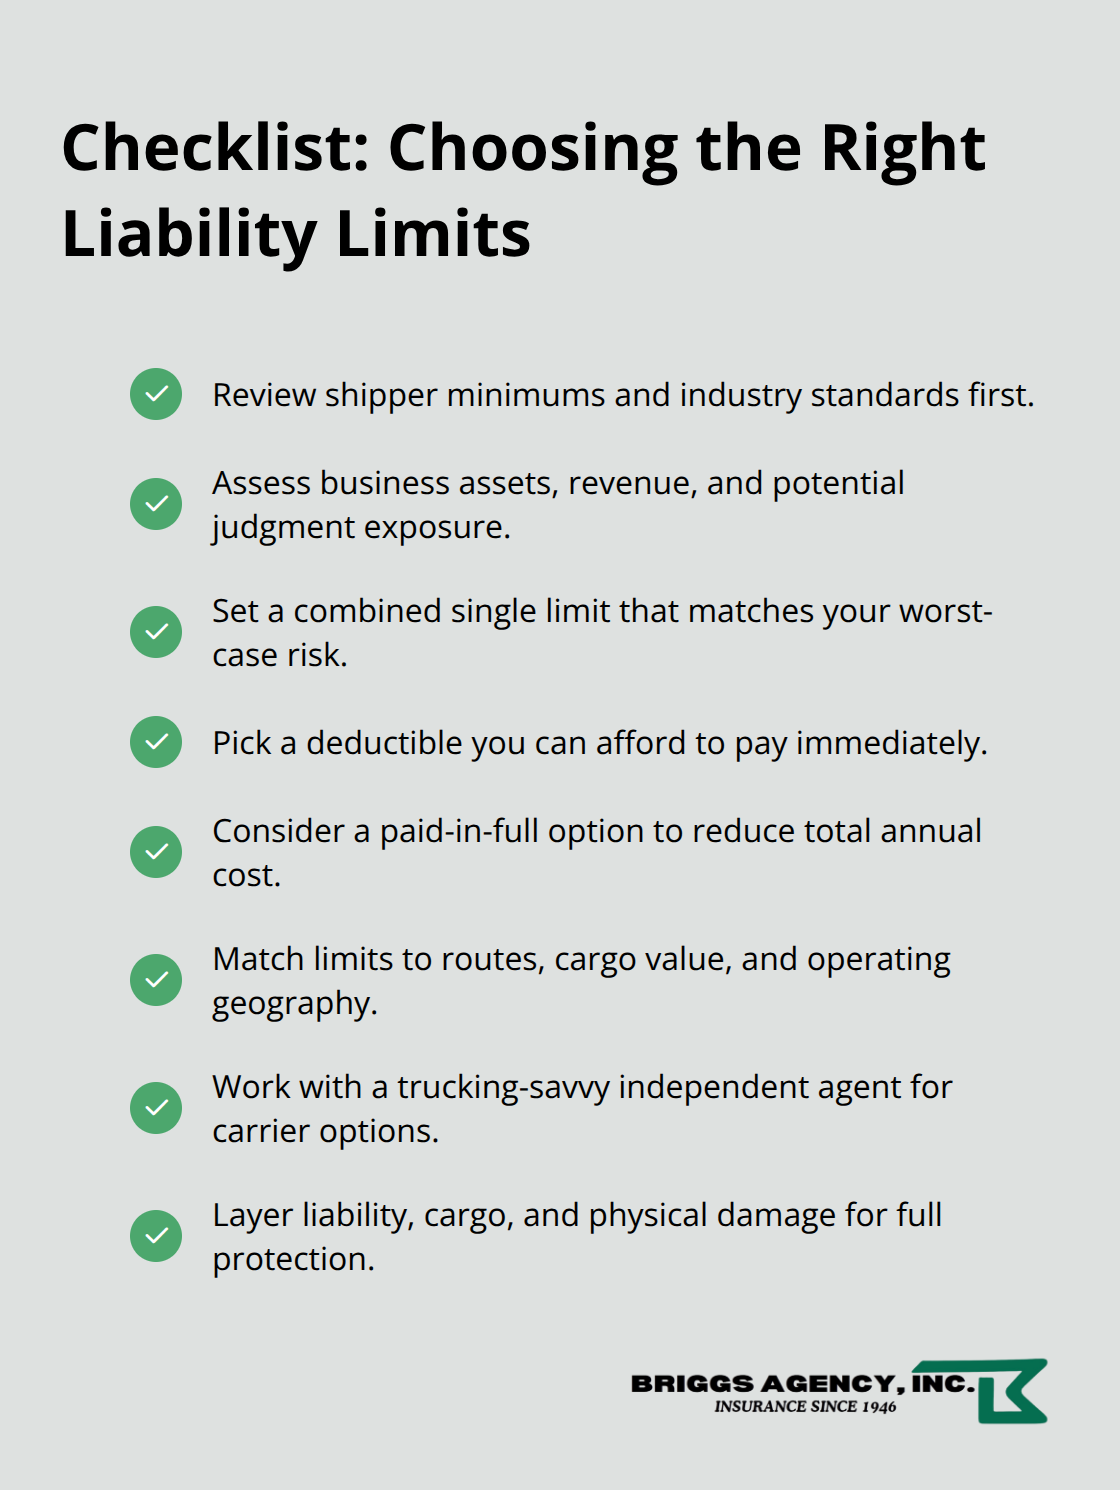
Checkmark list of steps to select truckers liability coverage. - Truckers liability insurance

Start with Shipper Requirements and Industry Standards

Review shipper requirements first-major carriers like FedEx and Amazon specify minimum liability limits before accepting loads, and those requirements reveal what the industry considers adequate protection for your cargo category. These minimums exist because shippers understand the real costs of cargo incidents and third-party claims. Your shipper’s requirements provide a practical baseline for coverage selection rather than guessing at appropriate limits.

Calculate Your Assets and Financial Exposure

Examine your assets and revenue next. If a judgment exceeds your coverage limit, courts can garnish future earnings and freeze business accounts. A combined single limit sets the maximum payout per incident, so if you carry $500,000 or $1,000,000 in coverage and damages exceed that amount, you absorb the difference. Most owner-operators carrying high-value cargo need minimums between $1,000,000 and $2,000,000 in combined single limit coverage to avoid catastrophic exposure.

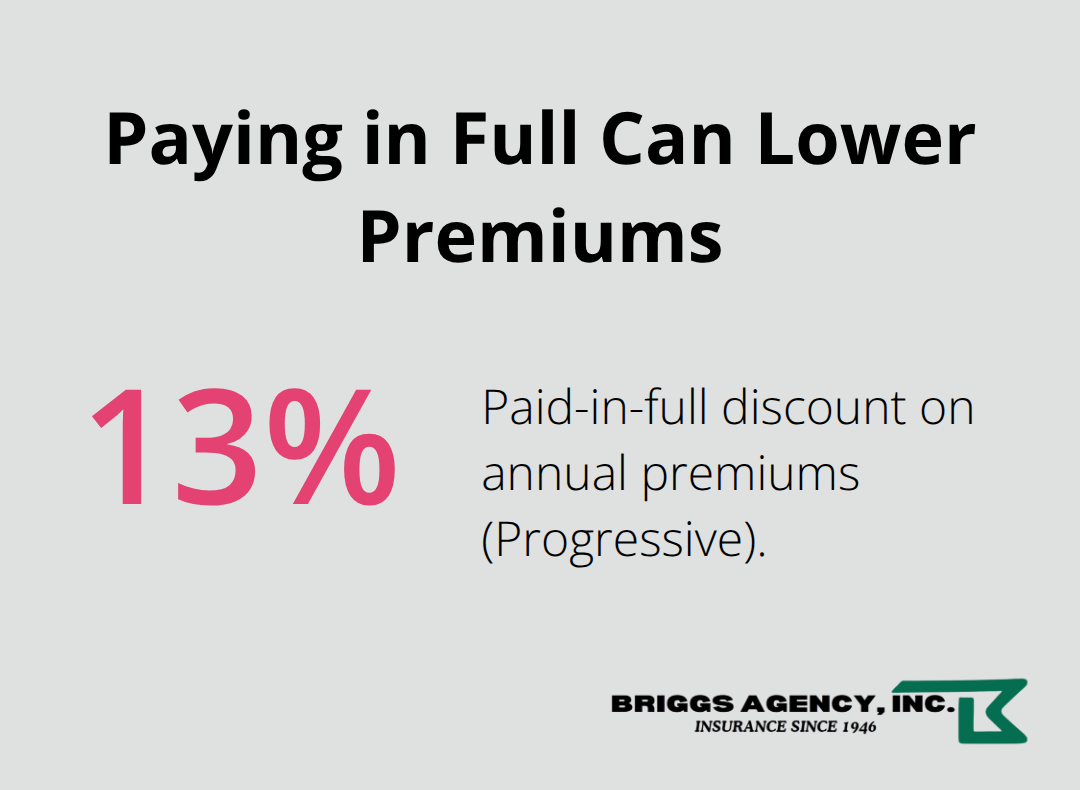
Your deductible directly affects your monthly premium-increasing it from $500 to $2,500 can reduce costs substantially, but only if you can actually pay that amount out of pocket when a claim occurs. Calculate your cash reserves realistically. If an accident happens and you cannot cover the deductible, you cannot file a claim, defeating the purpose of carrying insurance. Paid-in-full discounts can save 13% or more on annual premiums according to Progressive, reducing total cost upfront and improving cash flow management.

Match Coverage to Your Routes and Equipment

Route density and vehicle age influence coverage selection significantly. Regional operators making frequent stops face higher per-mile accident risk than long-haul drivers on interstate routes, justifying higher limits. Newer trucks with advanced safety features lower accident risk and insurance costs, while older equipment carries higher premiums and may require physical damage coverage if financed. State location matters-commercial truck insurance varies by jurisdiction due to traffic patterns, road conditions, and accident prevalence.

Work with an Agent Who Understands Trucking Operations

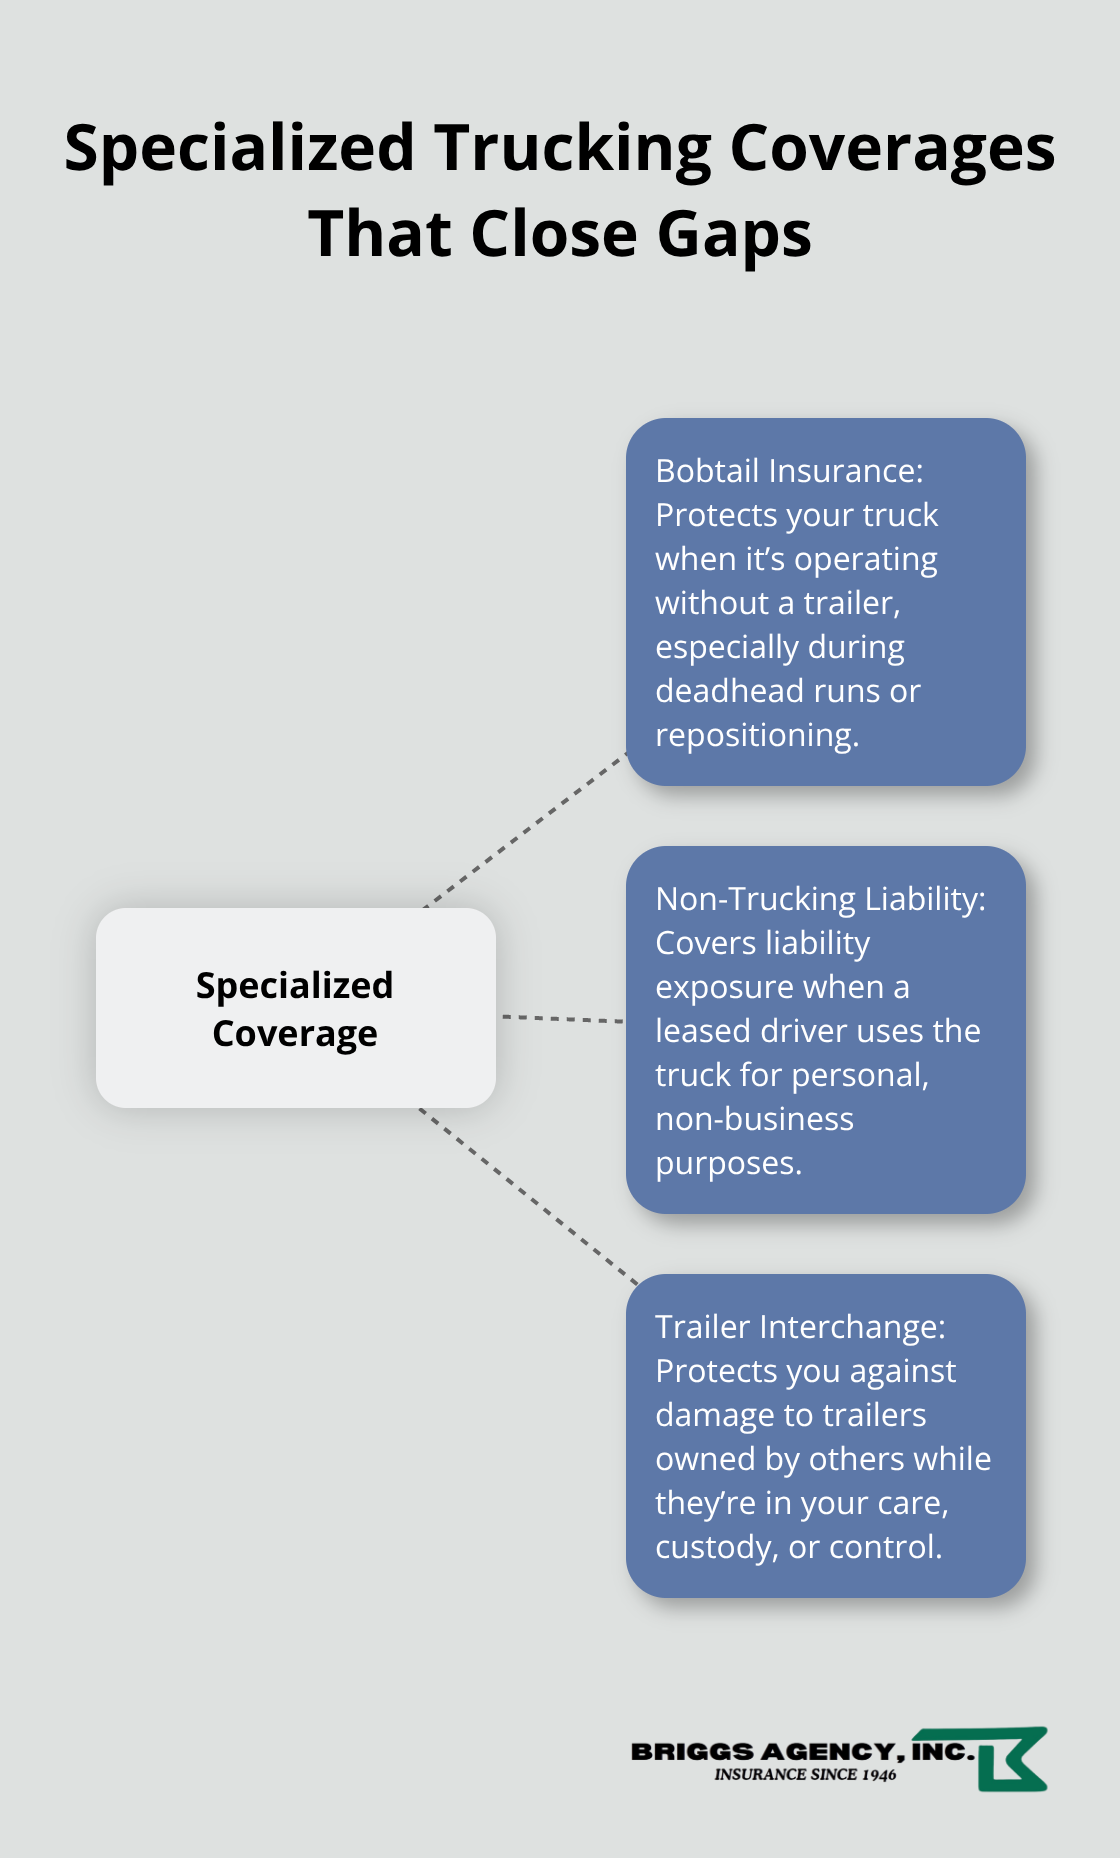
An agent who understands trucking operations can access multiple carriers and identify which insurers offer the best rates for your specific configuration. Rather than accepting a generic quote, work with an agent who asks detailed questions about your cargo mix, delivery locations, customer requirements, and fleet composition. This conversation reveals gaps in coverage you might miss alone. For example, if you operate outside dispatched routes or haul loads during non-working hours, bobtail or non-trucking liability coverage fills that gap when you are not actively moving cargo.

Layer Your Coverage for Complete Protection

Cargo insurance protects the goods themselves from damage or loss during transit, complementing liability coverage that protects against third-party claims. A comprehensive program combines liability, cargo, and physical damage coverage tailored to your operation rather than relying on a one-size-fits-all policy. This layered approach addresses the full range of exposures your trucking business faces.

Final Thoughts

Truckers liability insurance protects your driving team and business from the financial devastation that follows an accident. A single claim involving injuries or property damage can cost hundreds of thousands of dollars, and without adequate coverage, that expense comes directly from your business account or personal assets. Federal law requires interstate truckers to carry liability coverage, and major shippers like FedEx and Amazon mandate specific minimums before accepting loads.

Selecting the right policy means matching your coverage limits to your actual exposure based on cargo value, routes, and operating geography. A combined single limit between $1,000,000 and $2,000,000 protects most owner-operators carrying high-value cargo from catastrophic exposure. Your deductible affects your monthly premium significantly, and paying in full can save 13% or more on annual costs.

Percentage savings from paid-in-full discount on truck insurance.

We at Briggs Agency, Inc. have served individuals and businesses in Crown Point, Indiana since 1946, helping trucking operations select comprehensive coverage that reduces risk and protects what matters most. Our independent agents represent multiple top-rated carriers and compare options to deliver competitive pricing and hands-on service tailored to your fleet. Contact us to discuss your trucking insurance needs and secure the protection your driving team deserves.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Commercial Truck Liability: Navigating Risk on the Road

One accident involving your commercial truck can expose your business to significant financial and legal liability. At Briggs Agency, Inc., we’ve seen how quickly a single incident can threaten a trucking operation’s future.

Commercial truck liability coverage protects you when your vehicles cause injury or damage to others on the road. This guide walks you through what your policy actually covers, the risks you face, and concrete steps to reduce your premiums.

What Commercial Truck Liability Coverage Actually Covers

The Three Core Components of Your Policy

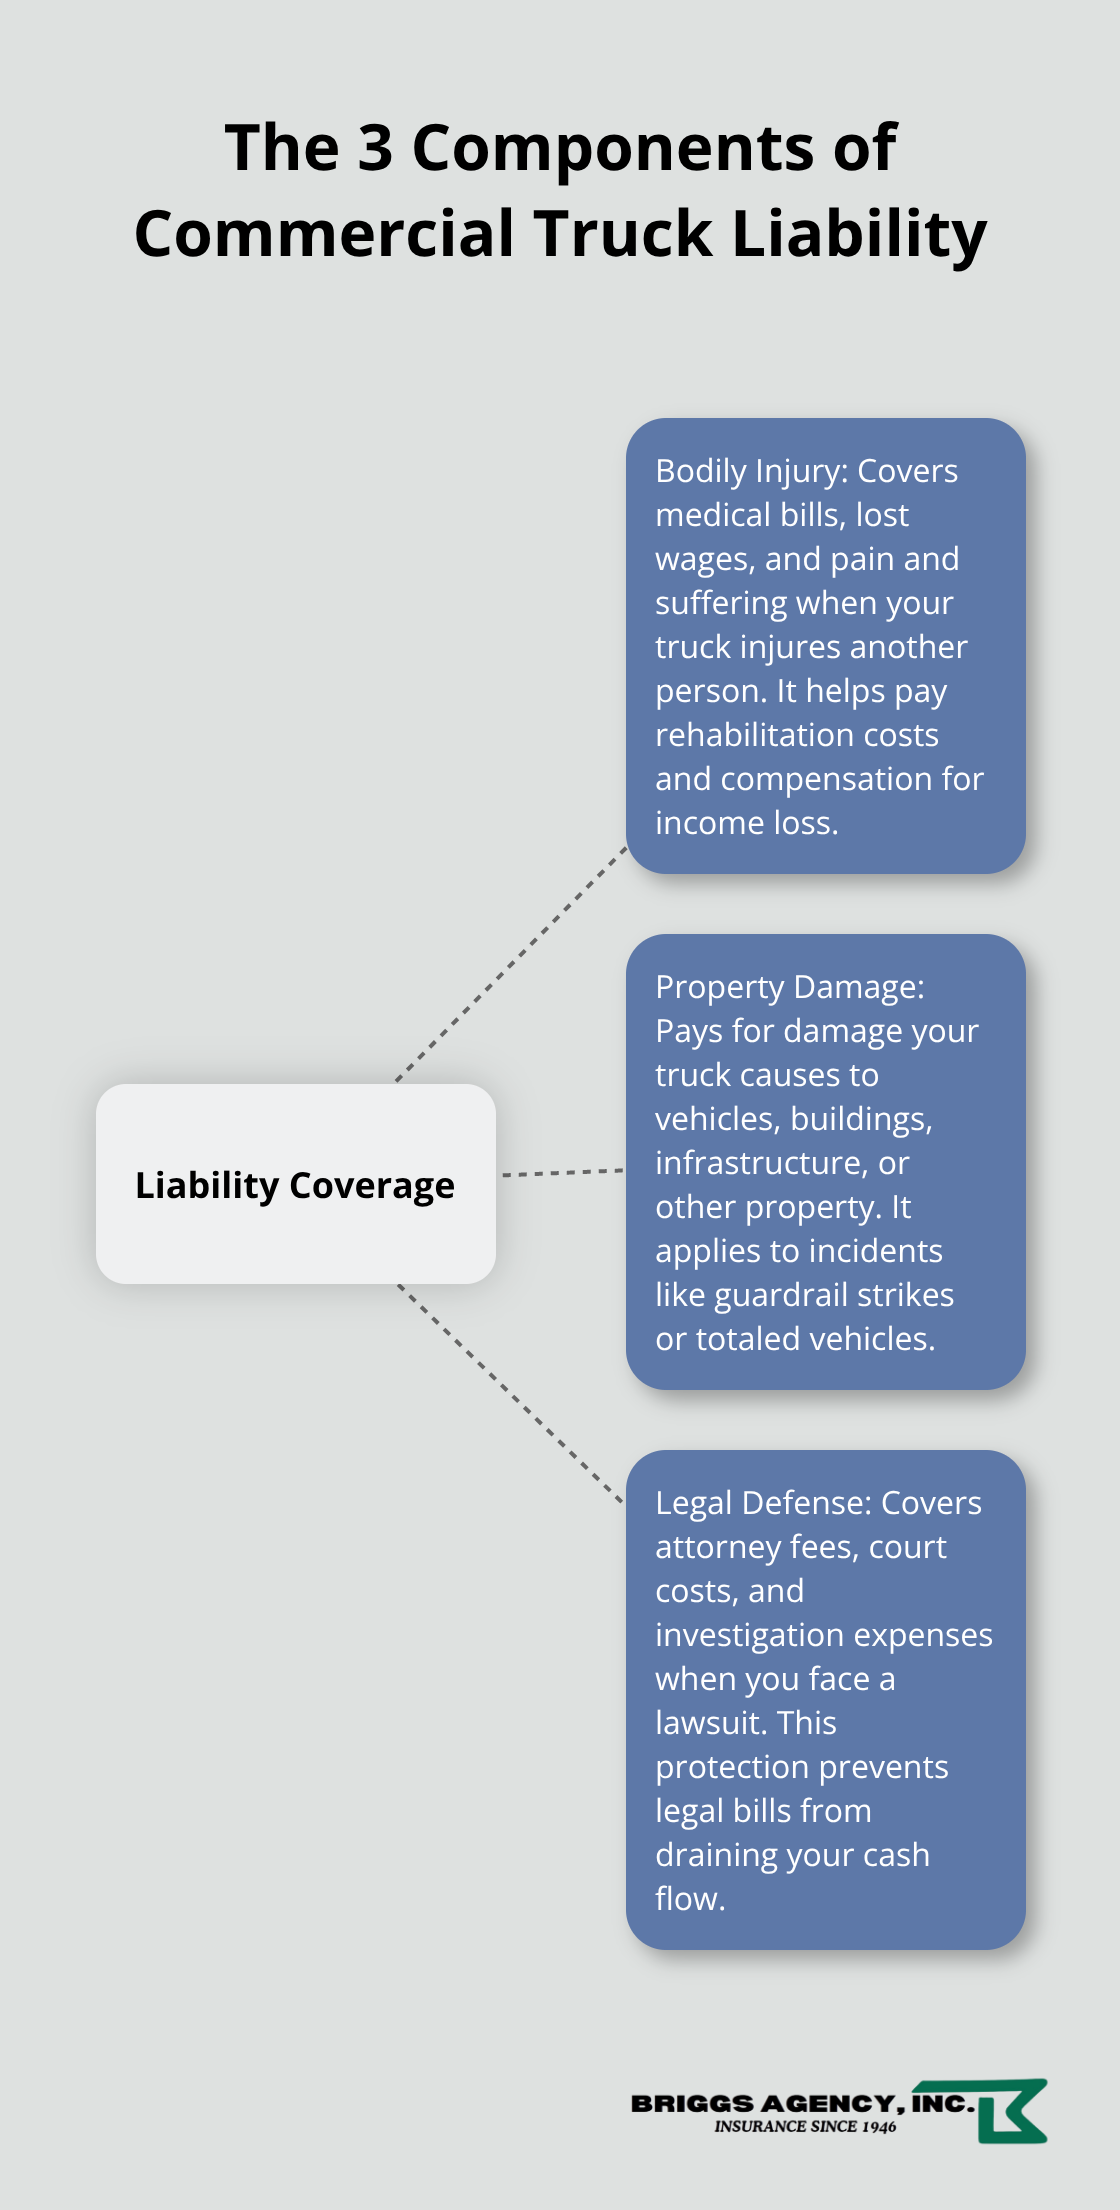
Commercial truck liability coverage protects your business through three distinct components when your truck causes harm to someone else on the road. Bodily injury liability covers medical expenses, lost wages, and pain and suffering when your truck injures another person. If your driver causes a collision that puts another driver in the hospital, their medical bills, rehabilitation costs, and compensation for lost income all fall under this coverage. Property damage liability pays for damage to vehicles, buildings, infrastructure, or other property your truck causes. A side-swipe collision that damages a guardrail, a rear-end crash that totals another vehicle, or cargo that falls and damages someone’s storefront all qualify for this protection.

Legal Defense: A Hidden but Essential Layer

Legal defense costs represent the third critical component-your insurer covers attorney fees, court expenses, and investigation costs when you face a lawsuit. This matters because legal defense costs in truck accident cases can quickly add up. Without this coverage, you would shoulder these costs out of pocket while your case proceeds, straining your cash flow and operations.

Federal Minimums vs. Real-World Requirements

Federal regulations require a minimum of $750,000 in liability coverage for most interstate trucking operations, according to the FMCSA. However, that minimum serves only as a baseline. Many shippers and brokers demand higher limits before they’ll contract with you, and your actual liability exposure depends on the cargo value you haul, the routes you operate, your driver’s experience, and your vehicle condition. If your coverage falls short and you’re found liable for damages exceeding your policy limits, your personal assets and business face direct risk.

Why Annual Reviews Matter

Your liability needs shift as your operation grows or changes. An experienced agent who understands trucking operations-not just general commercial insurance-can identify gaps in your coverage and recommend adjustments that align with your actual exposure. The difference between adequate protection and underinsurance often comes down to a conversation with someone who knows your business inside and out.

Understanding what your policy covers is only half the battle. The risks you actually face on the road determine whether your coverage is sufficient.

Infographic showing bodily injury, property damage, and legal defense as core parts of liability coverage

Common Risks Trucking Companies Face on the Road

Multi-Vehicle Collisions and Chain-Reaction Liability

Multi-vehicle collisions represent one of the most expensive liability exposures you face, and they happen more often than most trucking companies anticipate. When your truck triggers a chain-reaction crash on a highway, you become potentially liable for injuries and damages across multiple vehicles-medical bills for several drivers and passengers, vehicle repairs or total losses, and lost income for everyone affected. A single rear-end collision involving your truck and three other vehicles can easily generate $500,000 to $2 million in liability claims depending on injury severity and vehicle damage.

The FMCSA data shows that most truck crashes result from human error, but investigations frequently reveal that regulatory violations like hours-of-service fatigue contributed to the incident. These violations strengthen claims against your company and expose deeper liability. Driver negligence citations compound your exposure because they create a documented pattern that plaintiffs use to argue your company failed in hiring, training, or supervision. If your driver receives multiple speeding tickets or violations within a short period, insurance companies view your operation as higher risk, and that directly impacts your premiums at renewal.

Cargo Liability: A Threat Many Operators Underestimate

Cargo liability presents a different but equally serious threat that many trucking operators underestimate. When cargo shifts during transit, falls from your truck, or damages a shipper’s facility during loading or unloading, you face liability for those losses even if your driver followed standard procedures. Overweight loads and improperly secured cargo increase both your crash risk and your liability exposure-a load that falls onto another vehicle or pedestrian creates catastrophic injury claims that far exceed the cargo’s actual value.

Shippers and brokers now commonly demand that you carry cargo coverage as a contract requirement, and without it, you lose business opportunities. The value of loads you haul likely changes as your customer base evolves, which means your cargo coverage limits need regular attention. If you haul high-value goods like electronics or pharmaceuticals, your standard cargo coverage may be insufficient, and specialized endorsements become necessary to protect your business from underinsurance.

How Driver Violations Escalate Your Risk Profile

Your driver’s record directly shapes how insurers assess your operation’s risk level. Citations for speeding, hours-of-service violations, or unsafe lane changes signal to underwriters that your company may lack adequate supervision or training protocols. Each violation adds weight to your risk profile and can trigger premium increases at renewal, even if no accident occurred. Insurance companies track these patterns because they predict future claims-a driver with multiple violations statistically poses higher risk than one with a clean record.

Understanding these specific risks helps you identify where your coverage gaps exist and what steps reduce your exposure most effectively.

How to Lower Your Commercial Truck Liability Costs

Driver Training and Safety Programs Reduce Your Premiums

Driver training and safety programs lower your premiums because insurers measure risk through concrete metrics: accident frequency, violation citations, and claims history. When your drivers complete formal safety training, your company demonstrates to underwriters that you take prevention seriously, and that translates to measurable rate reductions. Progressive’s Smart Haul program shows this principle in action-new customers who share driving data via electronic logging devices save an average of $1,261 annually by proving safer operational practices. Even without telematics, Snapshot ProView saves approximately 6% for new customers and includes free fleet management tools for operations with three or more vehicles.

Percentage savings for new commercial trucking customers using Snapshot ProView - Commercial truck liability

These aren’t marginal discounts; they represent real money that compounds year after year.

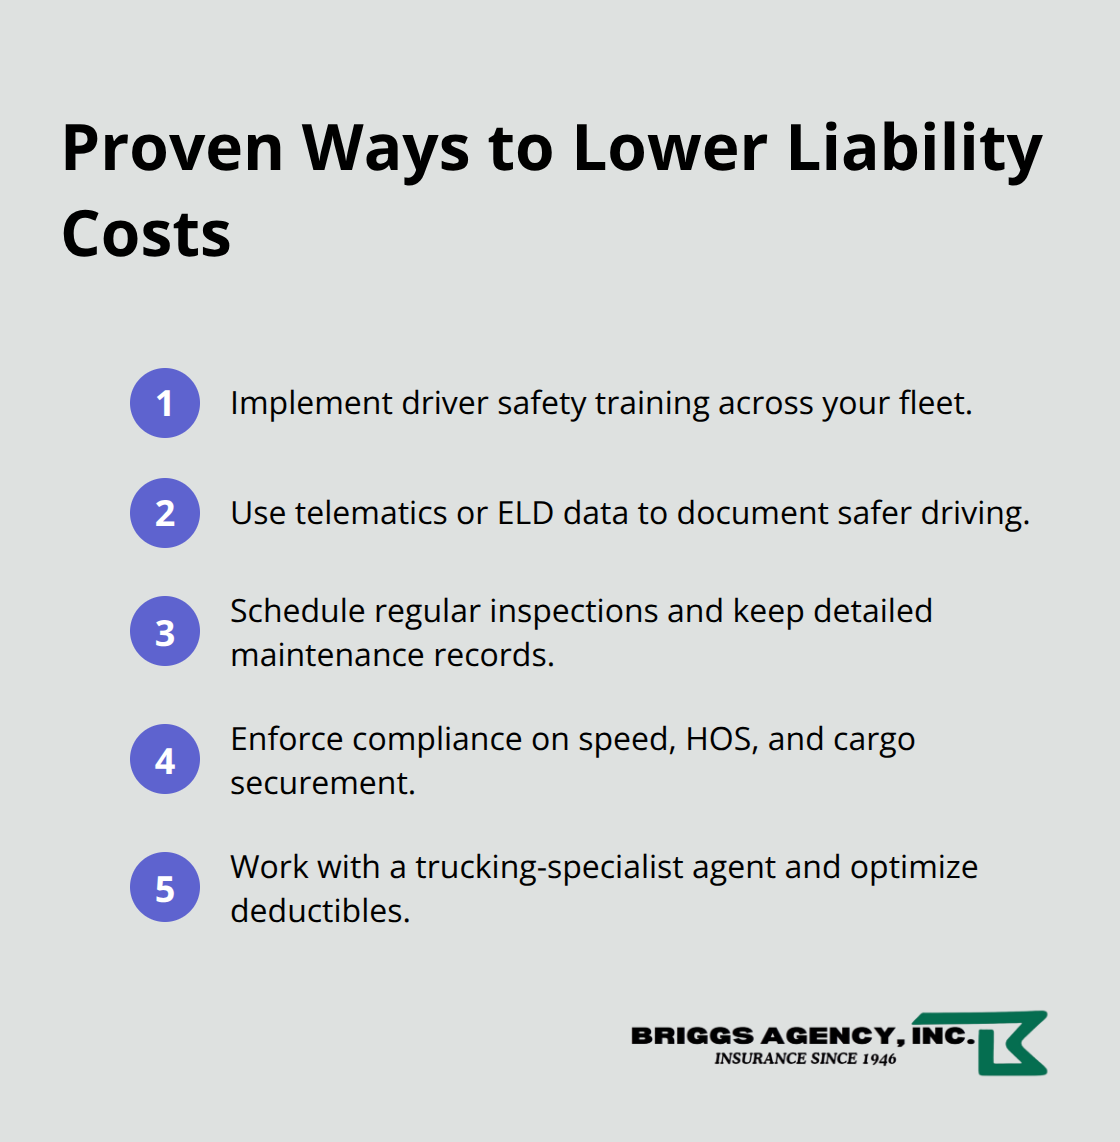
Your drivers need hands-on instruction on speed management, following distance, load securing, and hours-of-service compliance because citations for violations directly increase your risk profile with insurers. A single driver with multiple speeding tickets or hours-of-service violations signals to underwriters that your supervision practices may be weak, and that justifies premium increases across your entire fleet.

Vehicle Maintenance and Inspection Programs Prove Your Responsibility

Vehicle maintenance and inspection programs operate the same way-insurers reward documented proof that your trucks are mechanically sound and regularly serviced. A truck with faulty brakes, worn tires, or poor maintenance history increases your liability exposure substantially because mechanical failure contributes to accidents that might otherwise be preventable. Scheduling regular inspections, maintaining detailed maintenance records, and addressing safety issues immediately before they escalate shows insurers you manage your fleet responsibly.

Compact list of actionable steps to reduce commercial truck liability premiums

The FMCSA requires these inspections anyway, so compliance becomes your foundation. Carriers reducing their insurance costs most aggressively treat maintenance as an investment that pays for itself through lower premiums and fewer downtime incidents.

Work with an Agent Who Understands Trucking Operations

An experienced insurance agent who specializes in trucking operations matters more than most operators realize because they understand which rate factors actually move your premiums and which ones don’t. An agent focused on general commercial insurance may quote you standard rates without recognizing that your specific operation qualifies for safety discounts or specialized coverage arrangements that reduce your overall cost. At Briggs Agency, Inc., our agents understand trucking operations because we’ve served this industry since 1946, and we compare multiple carriers to identify where your operation gets the best combination of coverage and pricing.

An agent who knows your business can also recommend deductible strategies-increasing your deductible from $1,000 to $2,500 or $5,000 lowers your premium significantly, and that makes sense if your operation can absorb that out-of-pocket exposure without straining cash flow. The conversation with your agent should focus on your actual risk profile, not generic coverage recommendations. Reviewing your current premiums, deductibles, and coverage limits helps identify which adjustments deliver the most value for your specific operation.

Final Thoughts

Commercial truck liability coverage protects your business when accidents happen, and one collision can expose you to hundreds of thousands of dollars in medical bills, vehicle damage, legal fees, and lost income claims. Without adequate protection, your personal assets and business operations face direct risk. The federal minimum of $750,000 provides only baseline protection; your actual exposure depends on the cargo you haul, your routes, and your driver’s experience.

The steps to reduce your liability costs work because they address what insurers actually measure: accident frequency, violation citations, and claims history. Driver training programs that produce measurable safety improvements, regular vehicle maintenance that prevents mechanical failures, and documented inspection records all signal to underwriters that your operation manages risk responsibly. These investments pay for themselves through premium reductions that compound year after year.

Review your current coverage limits against your actual liability exposure, assess whether your drivers need additional safety training, and schedule a conversation with an agent who understands trucking operations. We at Briggs Agency, Inc. have served trucking operations since 1946, and we compare multiple carriers to identify where your operation gets the best combination of coverage and competitive pricing.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Business Property Insurance: Safeguarding Your Company’s Assets

Your company’s physical assets represent years of investment and hard work. From your building to your equipment and inventory, these assets keep your business running-but they’re also vulnerable to damage, theft, and disasters.

Business property insurance protects what you’ve built by covering the costs of repairs or replacement when the unexpected happens. At Briggs Agency, Inc., we help local business owners understand their coverage options so they can focus on what matters most: running their operation with confidence.

What Your Business Property Insurance Actually Covers

Your building, equipment, and inventory each face different risks-and your insurance needs to reflect that reality. Commercial property insurance protects the physical structures your business occupies, whether you own or rent the space. This includes the building itself, attached structures like loading docks or storage sheds, and permanent fixtures such as built-in shelving or HVAC systems. If you operate from a leased space, your landlord’s policy covers the building structure, but your policy protects your tenant improvements and the assets inside. The Hartford reports an average annual cost of around $1,605 for commercial property insurance, though this varies significantly based on your property’s age, construction materials, and location. Older buildings or those in higher-risk areas typically cost more to insure, while fire-resistant construction materials can lower your premiums.

Equipment and Tools Represent Real Value

Machinery, tools, computers, furniture, and specialized equipment all fall under your coverage. Business owners often underestimate how quickly equipment replacement costs accumulate-a restaurant’s kitchen equipment, a contractor’s power tools, or a salon’s styling stations represent substantial investments. If your business relies on specialized or high-value equipment, equipment breakdown insurance becomes particularly important. This coverage helps protect businesses from financial losses caused by mechanical, electrical or pressure system failures that standard property policies don’t cover. The Hartford includes equipment breakdown as an add-on endorsement, giving you flexibility to protect only what your business genuinely needs.

Inventory and Stock Demand Specific Attention

Your inventory-whether it’s retail products, raw materials, or perishable goods-needs separate consideration from your building and equipment. Standard property policies cover inventory against fire, theft, and vandalism, but gaps exist. If you stock perishable items like bakery ingredients or meat products, spoilage coverage becomes essential; without it, a refrigeration failure wipes out your inventory at your own expense. You need an accurate, current inventory list with replacement costs to determine appropriate coverage limits. Underinsuring your inventory means you absorb losses out of pocket; overinsuring wastes premium dollars. Getting your asset valuation right from the start matters significantly-this is where an experienced agent identifies exactly what needs protection and at what level.

Determining Your Coverage Limits

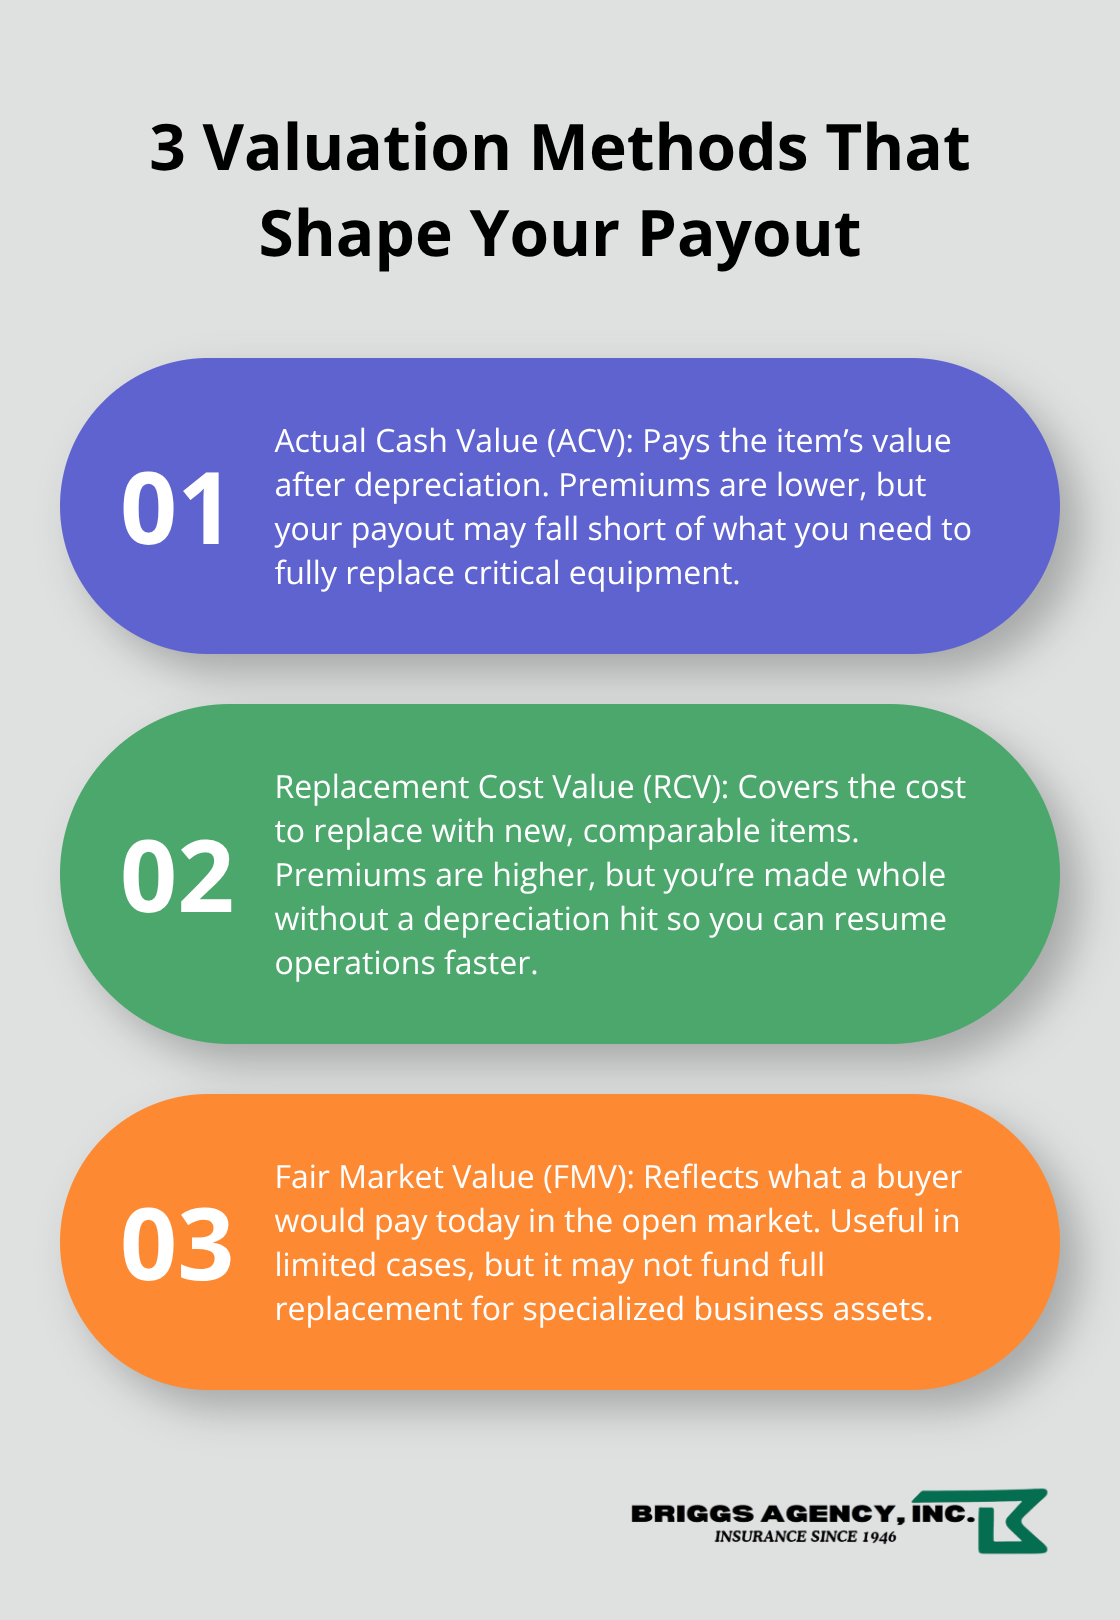
The three main valuation methods shape your coverage decisions: actual cash value (replacement cost minus depreciation), replacement cost value (cost to replace with similar items), and fair market value (current market price). Each method produces different coverage amounts and premium costs. Your choice affects how much you receive after a loss and how much you pay in premiums.

Overview of actual cash value, replacement cost value, and fair market value for business property insurance.

Higher deductibles generally lower your premium, but they also mean you pay more out of pocket when a loss occurs. Selecting the right balance between deductible and coverage limit requires understanding your financial capacity to absorb losses and your asset replacement timeline.

Building the Right Protection Strategy

Your specific risks determine which coverages you actually need. A retail store faces different exposures than a manufacturing facility or a professional services office. Location matters too-businesses in flood-prone areas need separate flood coverage through the National Flood Insurance Program, as standard policies exclude water damage. Construction materials, safety features (alarms, sprinklers, detectors), and the number of people on-site all influence both your risk profile and your premium. Once you understand what your business owns and what risks threaten those assets, you can work with an agent to build a protection strategy that fits your operation and budget. This assessment forms the foundation for choosing appropriate coverage limits and identifying any gaps that additional endorsements should fill.

Why Business Property Insurance Protects Your Bottom Line

A single fire, theft, or storm wipes out years of investment in equipment, inventory, and your physical space. Without property insurance, you absorb the full replacement cost yourself-and that’s money most businesses simply don’t have sitting in reserve. The Hartford reports an average annual cost of around $1,605 for commercial property insurance, which sounds substantial until you consider what happens without it. A restaurant owner whose kitchen equipment burns in a fire faces $50,000 to $100,000 in replacement costs plus weeks or months of lost revenue while rebuilding. A retail store robbed of its entire inventory loses not just the products but the cash flow those sales would have generated. Property insurance transforms a catastrophic loss into a manageable claim payout.

Lenders and Landlords Require Coverage

Beyond the direct financial protection, lenders and landlords won’t let you operate without it. If you financed your building, your mortgage lender requires proof of coverage-they’re protecting their investment in your property. Landlords writing commercial leases demand the same assurance. Many service contracts and customer agreements also stipulate that you maintain adequate property coverage. Without it, you violate those agreements and expose yourself to legal liability. The Hartford’s experience serving 1.3 million small business customers shows that most owners start with a Business Owner’s Policy bundling general liability, commercial property, and business income insurance.

Business Interruption Fills the Hidden Gap

Business interruption coverage, often included in property policies or available as an add-on, addresses the hidden cost of disasters. When a covered loss forces you to temporarily close, this coverage replaces lost income and covers ongoing expenses like payroll, rent, and utilities while you rebuild. A contractor with a fully equipped office and fleet loses more than the physical property if forced to shut down-they lose every job they can’t complete, every client they can’t service, and every dollar of revenue that stops flowing.

Location and Risk Profile Shape Your Costs

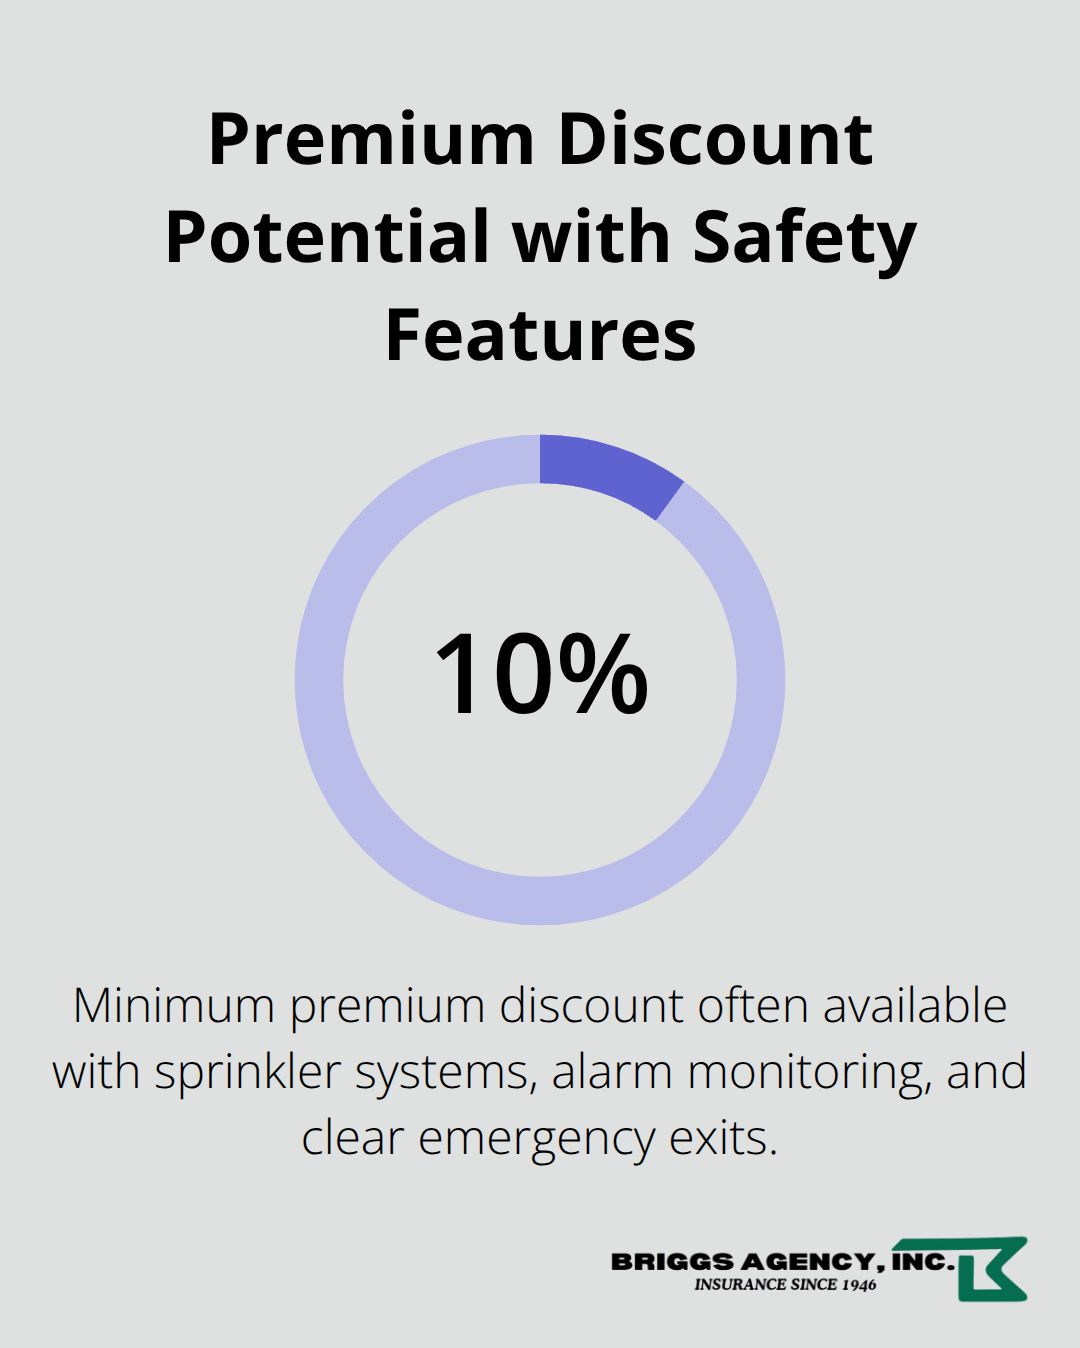
Location-specific risks matter enormously. A business in a high-crime area faces different theft exposures than one in a secure commercial park. Older buildings with outdated electrical systems carry higher fire risk than newer construction. Businesses with safety features like sprinkler systems, alarm monitoring, and clearly marked emergency exits often qualify for premium discounts of 10% or more, according to Hartford’s pricing structure. This means your risk management efforts directly reduce your insurance costs.

Percentage discount businesses may receive for safety features like sprinklers and alarms.

The National Flood Insurance Program exists as a separate requirement because standard policies exclude flood damage; if your business sits in a flood-prone area, this gap becomes expensive fast.

Understanding Your True Exposure

Property insurance isn’t an optional expense or a regulatory checkbox-it’s the difference between a manageable setback and a business-ending catastrophe. The right coverage protects your operation from financial ruin, but only if you’ve identified what you actually own and what risks threaten those assets. This assessment determines which coverages you need and at what limits, which is exactly what we’ll explore in the next section.

How to Match Your Coverage to What You Actually Own

Create a Complete Asset Inventory

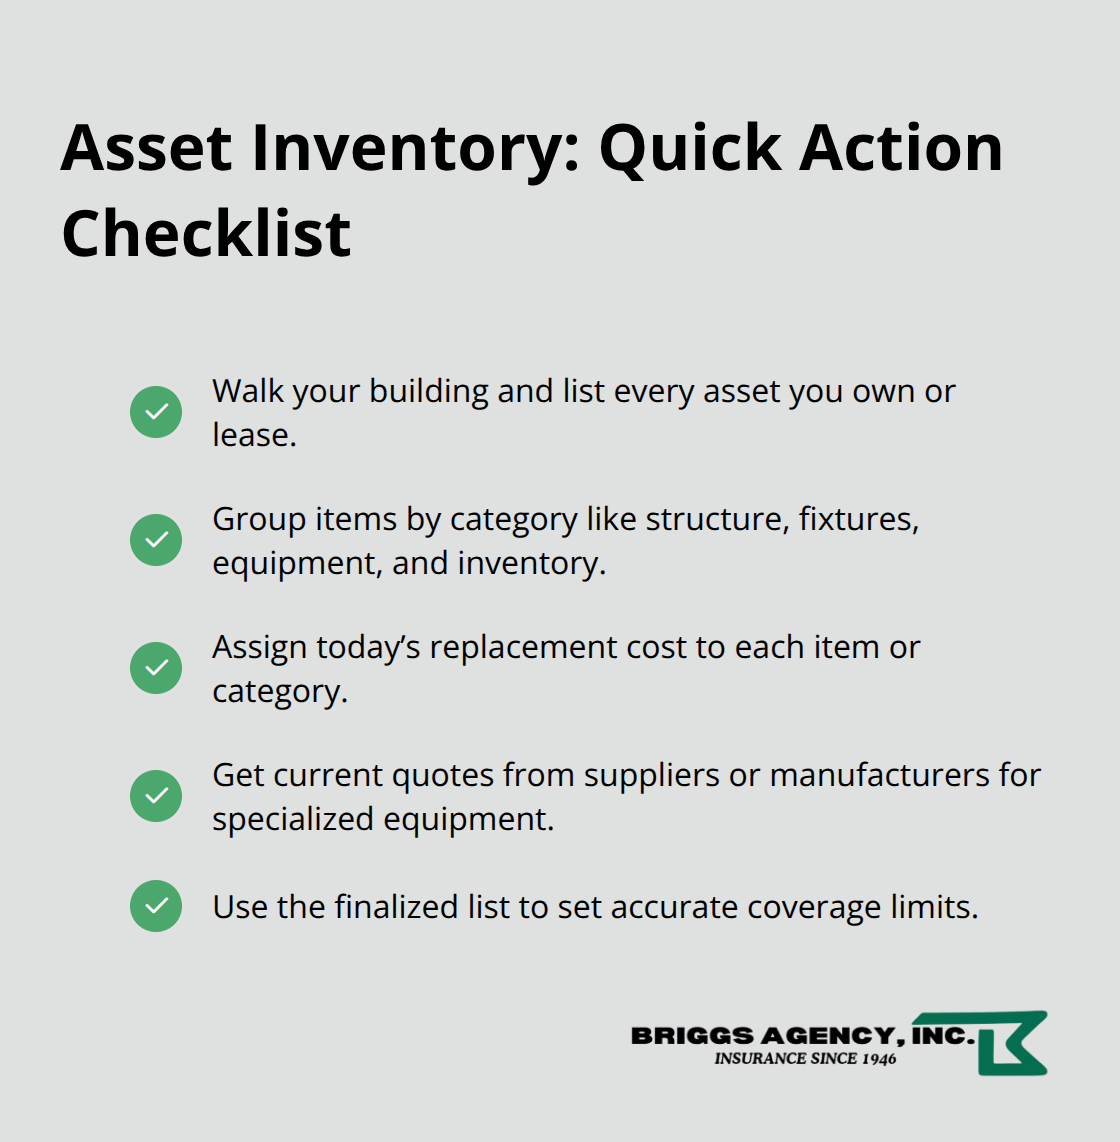
Start with an inventory of every asset your business owns or leases. Walk through your building and list everything: the structure itself, HVAC systems, electrical panels, built-in fixtures, computers, machinery, furniture, signage, outdoor equipment, and inventory. Assign replacement costs to each category-not what you paid five years ago, but what it costs today to replace that item new. Business owners typically underestimate replacement costs, which means they end up underinsured.

Checklist of steps to build a complete business asset inventory with replacement costs. - Business property insurance

If you own a restaurant, contact equipment suppliers for replacement kitchen gear quotes. If you operate a retail store, calculate what it would cost to restock your entire inventory from scratch. For specialized equipment, manufacturers provide current pricing directly. This exercise takes time, but it forms the foundation for every coverage decision that follows. Once you know what you own and what it costs to replace, you can match your coverage limits to reality instead of guessing.

Choose the Right Valuation Method

The valuation method you select determines how much you actually receive after a loss. Replacement cost value pays to replace damaged items with new equivalents-a five-year-old computer gets replaced with a new computer of similar capability, not depreciated down to $200. Actual cash value subtracts depreciation, so that same computer might only yield $300 after accounting for age and wear.

Most business owners should choose replacement cost because it covers what you genuinely need to spend to get back to work. Actual cash value costs less in premiums but leaves you short when you need to replace equipment. Your deductible choice directly affects your monthly premium: a $500 deductible costs more than a $2,500 deductible, but that higher deductible means you pay $2,500 out of pocket before your policy kicks in.

Balance Your Deductible and Cash Flow

Analyze your business’s cash flow to determine the right deductible. Can you comfortably cover a $2,500 loss without disrupting operations, or would a $500 deductible better match your financial reality? Different combinations of deductibles and coverage limits affect both your premium and your out-of-pocket exposure when a loss occurs.

An experienced local agent walks through these decisions with you, showing exactly how each option impacts your costs. They identify coverage gaps that endorsements should fill, like spoilage coverage for refrigerated inventory or equipment breakdown for machinery your operation depends on.

Final Thoughts

Business property insurance protects what you’ve built, but only when your coverage matches what you actually own. The steps we’ve outlined-inventorying your assets, understanding valuation methods, and selecting appropriate deductibles-form the foundation of real protection. Without this groundwork, you risk being underinsured when you need coverage most, or paying for protection you don’t actually need.

Your next move is straightforward: gather your asset list and current policy documents, then schedule a conversation with an agent who understands your specific operation. Review what you’re currently covered for and identify any gaps. Ask whether your deductibles align with your cash flow, whether your coverage limits match today’s replacement costs, and whether endorsements like spoilage or equipment breakdown would protect your business better.

We at Briggs Agency, Inc. have been helping local business owners in Crown Point and beyond protect their operations since 1946. Our independent agency represents multiple top-rated carriers, which means we compare options and tailor business property insurance to your actual needs rather than pushing a single product. Contact us today to review your current coverage and discover how the right protection can safeguard your company’s assets with confidence.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Office Property Insurance: A Practical Guide for Small Businesses

Your office property insurance protects one of your biggest business assets-your physical space and everything in it. Yet many small business owners overlook coverage gaps until disaster strikes.

At Briggs Agency, Inc., we’ve helped countless local businesses understand what they actually need to protect themselves. This guide walks you through the essentials so you can make informed decisions about your coverage.

What Your Office Property Insurance Actually Protects

Your office property policy covers three distinct layers of protection, and understanding each one matters because gaps here lead to real financial pain. The first layer is your building structure itself-the walls, roof, flooring, electrical systems, plumbing, and HVAC equipment. If a fire damages your office or a storm tears through the roof, this coverage pays for repairs or replacement. According to Insureon data, building age and condition heavily influence what you’ll pay; offices in masonry, concrete, or steel structures cost significantly less to insure than those built with wood or vinyl.

Contents and Equipment Inside Your Office

The second layer protects your contents and equipment inside: computers, furniture, inventory, filing cabinets, printers, and other business assets. This coverage also extends to items just outside your office, like exterior signage and landscaping. Most small businesses carry around $1 million per occurrence and $2 million aggregate in a Business Owner’s Policy that bundles property and general liability together, according to Insureon’s analysis of customer data. You’ll choose between replacement value coverage, which pays what it costs to replace damaged items at today’s prices, or actual cash value coverage, which accounts for depreciation. Replacement value costs more but protects you better; actual cash value is cheaper but leaves you with less recovery after a loss.

Business Interruption Coverage Keeps Cash Flowing When Doors Close

Business interruption coverage replaces lost income when a covered event forces you to shut down. The coverage allows businesses to pay fixed expenses, including costs incurred while operating at an offsite location, while the property is closed for repairs. Many small business owners skip this, which is a mistake-weather-related shutdowns affect significant portions of businesses in certain sectors, and fire claims cause rapid, substantial damage that can halt operations for weeks or months.

Additional Endorsements for Your Specific Risks

You can add endorsements for specific risks your location faces: earthquake coverage in seismic zones, flood insurance in areas prone to water damage, and equipment breakdown coverage for critical systems. Standard property policies exclude earthquakes, floods, and volcanoes unless you purchase separate endorsements, so verify what your regional risks are and whether your policy addresses them. The Hiscox Underinsurance in Small Business Report found that 75 percent of U.S. small businesses carry insufficient coverage, leaving themselves exposed when claims actually happen.

Getting Accurate Quotes and Valuations

When obtaining a quote, have exact values ready for your building, contents, and inventory to get accurate pricing; inflated valuations waste money while undervalued assets leave you short after a loss. These details form the foundation for determining whether your coverage truly matches your exposure-a step that separates adequate protection from costly gaps when you actually file a claim.

Why Your Business Needs Office Property Insurance

Fire, theft, and weather damage destroy businesses faster than most owners expect. According to Insureon data, four most common commercial insurance claims for small offices are burglary and theft, fire, weather damage, and on-premises customer injuries. A single fire shuts you down for weeks or months; weather-related damage forces temporary closures that drain cash reserves; theft of computers or inventory creates immediate operational gaps. Without property coverage, you absorb these costs entirely from cash flow or savings-most small businesses cannot sustain this hit. The financial reality is stark: replacing your office equipment, inventory, or building structure out of pocket often means choosing between recovery and closure.

Property Insurance Transfers Risk to Your Carrier

Property insurance transfers this risk to a carrier, letting you rebuild instead of filing for bankruptcy. Your lease or lender almost certainly requires it anyway. Most commercial landlords mandate that tenants carry property coverage on their improvements and contents, and commercial lenders require it as a condition of any business loan. Skipping coverage violates your lease or loan agreement and exposes you to legal liability if something happens.

Business Interruption Coverage Protects Your Cash Flow

Beyond contractual obligations, property insurance protects cash flow during the recovery period. Business interruption coverage, often bundled into a Business Owner’s Policy, replaces lost income while your office remains closed for repairs. Insureon found that 87 percent of small business customers choose a BOP with typical limits around one million per occurrence and two million aggregate, combining property and general liability into one streamlined policy.

Percentage snapshot of underinsurance and BOP adoption among U.S. small businesses.

This matters because operational downtime costs money whether the building is damaged or not: you still owe rent, payroll, and utilities while earning zero revenue. A covered loss without business interruption coverage means you absorb all fixed expenses with no income, creating a financial crisis that property damage alone did not cause.

The Real Cost of Operating Without Coverage

You would not operate without electricity or running water, and property coverage functions the same way: it is infrastructure that allows your business to survive disruption. The decision to carry office property insurance is not about fear or worst-case thinking-it is about basic financial management. When you face a loss, the coverage you selected determines whether you recover quickly or struggle for months. Understanding what you actually need to protect (your building, contents, and income stream) sets the stage for choosing the right policy limits and endorsements.

How to Size Up What You Actually Need to Protect

Start with a physical inventory of your office space and assets-not a rough estimate. Measure your square footage, photograph your equipment, and list everything from computers to furniture to inventory. This matters because undervaluation leaves you short after a loss, while overvaluation wastes premium dollars monthly.

Compact checklist of steps to right-size office property insurance.

Your building value should reflect replacement cost at current market rates in your area, not what you paid years ago. Contents and equipment need individual attention: a desktop computer might cost $1,200 to replace today, but you only get actual cash value (depreciated) unless you specifically choose replacement value coverage. Most small offices underestimate their contents value by 20 to 40 percent, discovering the gap only when filing a claim.

Get Accurate Quotes Based on Real Numbers

Once you have solid numbers, get three quotes from different carriers, because premiums range from under $350 annually to over $15,000 depending on location, construction, and risk profile. A masonry or steel-frame building in a low-crime area with sprinklers and fire alarms costs far less than a wood-frame office in a high-risk zone. The variation reflects real differences in loss exposure, not arbitrary pricing.

Location and Construction Drive Your Actual Cost

Your building’s location and construction type matter more than most owners realize. Geographic variation is dramatic: small business property insurance costs roughly $38 per month in Washington state but $208 per month in New York-a five-fold difference driven by regional disaster risk, crime rates, and local building codes. Your building materials directly affect premiums: masonry, concrete, and steel structures are significantly cheaper to insure than wood or vinyl construction because they resist fire and weather damage better. The age and condition of major systems (roof, electrical, plumbing, HVAC) influence pricing substantially; a recently updated roof or modern electrical panel lowers your rate, while deferred maintenance triggers higher costs or outright exclusions. Distance to the nearest fire station and fire hydrant also factor in: properties within one mile of fire protection pay less than rural locations.

Hub-and-spoke showing main cost drivers for office property insurance.

If your office has sprinklers, fire alarms, or security systems, these reduce premiums through loss-control discounts that carriers actively reward. Document these features before shopping for quotes-they directly lower what you pay.

Choose Your Deductible Based on Cash Reserves

Your agent helps you choose between higher deductibles (which lower monthly premiums but raise out-of-pocket costs per claim) and lower deductibles based on your cash reserves and risk tolerance. The average deductible among small business customers is $1,000, but the right choice depends on your specific situation. If you maintain three months of operating expenses in reserves, a $2,500 deductible might make sense and save you money monthly. If cash flow is tight, a lower deductible protects you better despite higher premiums.

Identify Endorsements That Match Your Actual Risks

An experienced agent identifies endorsements you actually need-earthquake coverage in seismic zones, flood insurance near waterways, inland marine coverage if equipment travels off-site-rather than selling you protections for risks that do not apply to your business. They verify that your policy meets any lease requirements or lender obligations, preventing violations that could void coverage or trigger lease termination. This guidance upfront prevents costly mistakes and ensures your coverage truly matches your exposure.

Final Thoughts

Office property insurance protects your business from financial devastation when fire, theft, weather, or other covered events strike. The three layers of protection-your building structure, contents and equipment, and business interruption coverage-work together to keep your operation running through disruption. Without this coverage, you absorb replacement costs entirely from cash flow, which most small businesses cannot sustain.

The practical steps are straightforward: inventory your space and assets accurately, obtain quotes from multiple carriers based on real numbers, and select deductibles and endorsements that match your actual risk profile. Geographic location and building construction drive your costs more than anything else, so understanding these factors helps you anticipate what you’ll pay. Your cash reserves and risk tolerance determine whether a $1,000 deductible works for your situation or whether you need lower protection.

An experienced agent identifies which endorsements you actually need-earthquake coverage in seismic zones, flood insurance near waterways, inland marine protection for equipment that travels-rather than selling unnecessary add-ons. They verify your office property insurance meets lease requirements and lender obligations, preventing violations that could void protection when you need it most. Contact Briggs Agency, Inc. to discuss your coverage needs and receive a quote that reflects your specific situation.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
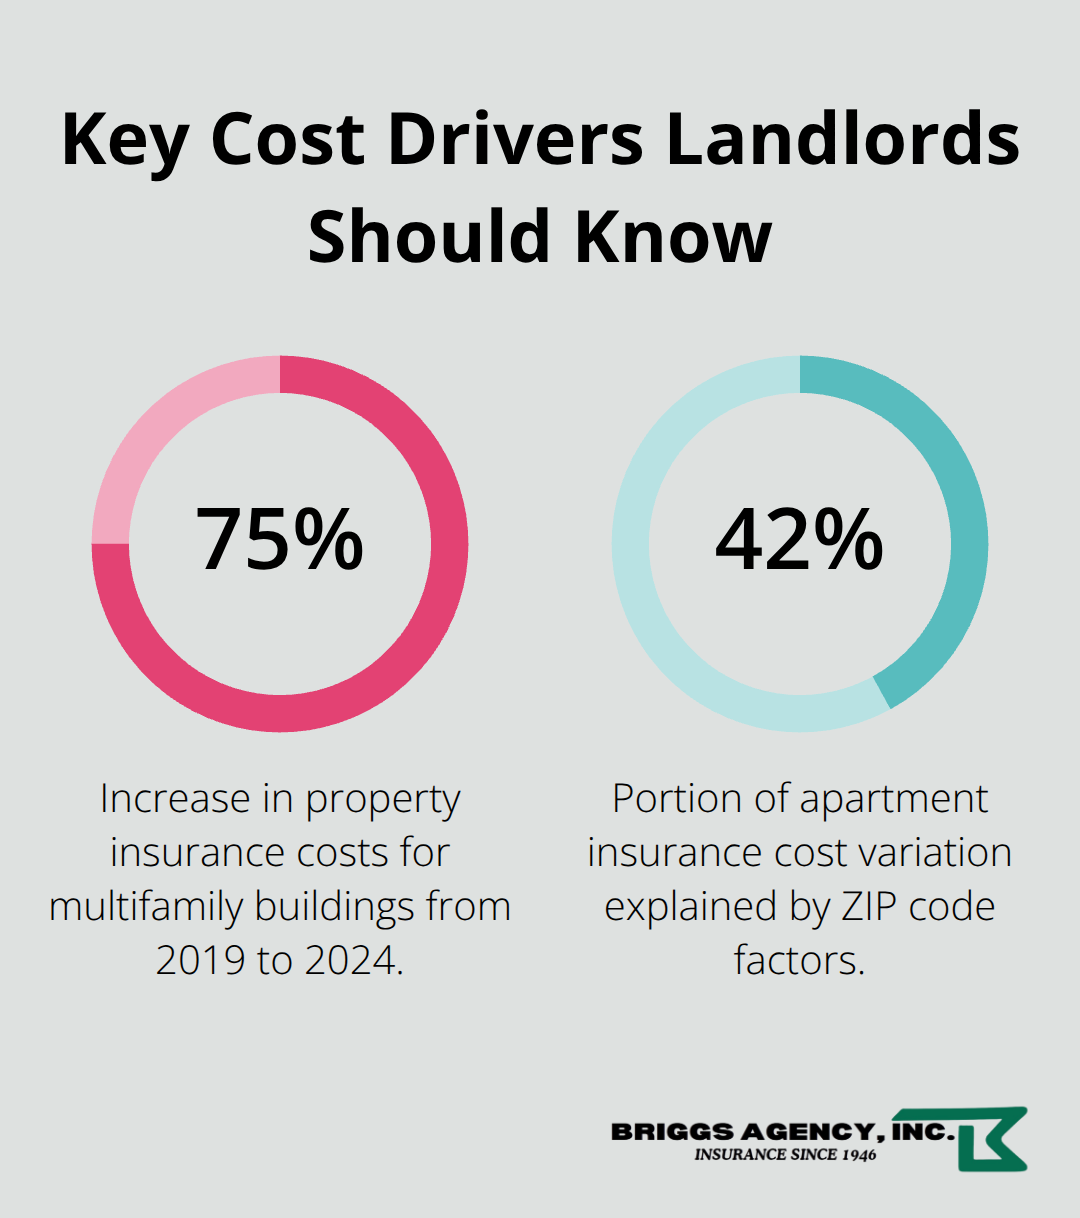
Commercial Trucking Insurance: Protecting Your Fleet on the Road

Running a trucking operation means managing countless moving parts, and commercial trucking insurance is one of the most important decisions you’ll make for your business. At Briggs Agency, Inc., we’ve helped fleet owners navigate coverage options that actually protect their assets and bottom line.

The right policy covers everything from liability claims to cargo damage, but choosing it requires understanding your specific risks. We’ll walk you through what matters most for your fleet.

What Your Trucking Insurance Actually Covers

Liability Coverage: The Foundation of Your Protection

Liability coverage protects you when your truck causes bodily injury or property damage to someone else. This is the foundation of any trucking policy and is legally required in every state. Bodily injury liability covers medical expenses, lost wages, and pain-and-suffering claims when your truck injures another person. Property damage liability covers repairs or replacement of damaged vehicles, buildings, or infrastructure.

Most policies set separate limits for each-for example, $100,000 per person and $300,000 per accident for bodily injury, with $50,000 for property damage. However, many fleet operators find these minimums insufficient given the rising cost of litigation. Multi-million-dollar awards are becoming more common in trucking liability cases. This trend means higher liability limits are increasingly practical rather than optional.

Physical Damage Coverage: Protecting Your Assets

Physical damage coverage protects your own trucks and cargo. Collision insurance pays for truck damage from accidents, while comprehensive coverage handles theft, weather, vandalism, and other non-collision events. Cargo insurance is equally important-it covers goods in transit from loss or damage, which directly affects your client relationships and contract compliance.

Physical damage insurance showed strong underwriting performance in 2024 with an estimated 88.6% combined ratio, making it one of the most competitively priced coverage lines available. This means you can secure solid rates without sacrificing protection.

Specialized Coverage: Filling Operational Gaps

Specialized coverage fills gaps that standard policies leave open. Bobtail insurance protects your truck when operating without a trailer, which is critical for deadhead runs or repositioning your fleet. Non-trucking liability covers liability exposure when leased drivers use the truck for personal purposes. Trailer interchange insurance protects you against damage to trailers owned by others while in your care.

Hub-and-spoke diagram with specialized trucking coverages that address operational gaps. - Commercial trucking insurance

These specialized options address real operational gaps. If a driver uses your truck to run a personal errand and causes an accident, standard liability won’t cover it-non-trucking liability will. The cost to add these endorsements is minimal compared to the exposure they eliminate. Understanding which gaps apply to your operation sets the stage for selecting appropriate coverage limits and deductibles that match your actual risk profile.

Why Your Fleet Needs Commercial Trucking Insurance

Federal and State Compliance Requirements

Federal and state regulations mandate that you carry insurance-there’s no option to skip it. The Federal Motor Carrier Safety Administration requires interstate carriers to file proof of financial responsibility through forms BMC-91 and BMC-34. BMC-91 covers bodily injury and property damage up to specific minimums based on your cargo type and vehicle weight. Operating without proper filings costs you your operating authority and exposes you to substantial fines. Compliance forms the foundation, but adequate coverage protects far more than your legal standing.

Protection Against Catastrophic Liability Claims

The real reason to carry adequate coverage is financial protection against claims that can destroy a business. Verdict severity in trucking liability cases has risen sharply, with multi-million-dollar awards increasingly common. If your policy limits fall short, you become personally liable for the difference-creditors pursue your business assets, equipment, and personal savings. This happens regularly to under-insured carriers who cut corners on coverage limits.

Cargo Theft and Physical Damage Exposure

Infographic showing 60% surge in cargo theft losses and 18% rise in confirmed incidents in 2025 in the U.S. - Commercial trucking insurance

Financial exposure extends beyond accidents. Cargo theft hit record levels in 2024 and remained elevated into 2025, particularly for food, metals, and electronics shipments according to Verisk CargoNet data. Without cargo coverage, a single theft wipes out your profit margin on that load. Physical damage claims from weather events, mechanical failures, or collisions sideline your truck for weeks and kill cash flow when you can’t generate revenue.

Bridging Income Loss During Repairs

Rental reimbursement and downtime coverage help bridge the gap created by vehicle downtime. These endorsements cover rental truck costs or lost income while your vehicle undergoes repair. For owner-operators and small fleets especially, one major claim without proper coverage forces you out of business. The peace of mind comes from knowing that when something goes wrong-and in trucking, it will eventually-your policy covers the exposure rather than your bank account.

Choosing Coverage That Matches Your Risk

Understanding your actual operational risks determines whether your coverage limits and deductibles align with your exposure. The next section walks you through how to assess your fleet’s specific needs and select a policy that protects your operation without leaving gaps.

How to Size Your Coverage to Your Operation

Map Your Fleet and Operational Footprint

Start by mapping your actual fleet and operational footprint, not industry generalizations. The number of trucks you operate, whether you run regional or interstate routes, and the types of cargo you haul directly determine which coverage limits make financial sense. A five-truck local operation hauling general freight faces different exposure than a twenty-truck fleet moving hazmat across state lines. Federal minimums exist, but they’re baseline thresholds, not targets.

According to Inszone’s 2025 market update, liability renewal rates climb 7 to 20 percent for many fleets, with larger increases hitting carriers with adverse loss histories or high-hazard commodities. This pricing pressure means you need coverage limits that reflect your true operation, not just what regulators require.

Match Coverage Limits to Your Cargo and Routes

If you operate in high-density metro areas or transport high-value cargo like electronics or metals, your liability exposure justifies higher limits than a carrier running rural routes. Cargo theft data from Verisk CargoNet shows estimated losses surged 60% to nearly $725 million in 2025, with confirmed cargo theft incidents increasing 18%, so if those commodities move through your fleet, cargo coverage with appropriate limits becomes non-negotiable.

Your route selection and cargo type directly influence the coverage limits that protect your operation adequately. A hazmat carrier needs higher environmental liability limits than a general freight hauler. A fleet moving temperature-sensitive goods needs refrigerated cargo coverage that a dry goods operator doesn’t.

Choose Your Deductible Based on Safety Performance

Your deductible choice directly impacts your monthly premium and out-of-pocket exposure after a claim. Deductibles typically range from $1,000 to $2,500 for most small and mid-sized fleets. Higher deductibles lower premiums but increase your cash outlay when claims happen.

If your fleet has strong safety records and clean loss runs, accepting a $2,500 deductible can meaningfully reduce annual costs. If your drivers have recent violations or your fleet carries marginal safety ratings, a $1,000 deductible protects your cash flow when claims inevitably occur. The math works differently for each operation.

Partner with an Agent Who Understands Trucking

Finding an agent who actually understands trucking risks separates adequate coverage from gaps that destroy businesses. Generic commercial agents treat trucking like standard business liability, missing specialized exposures unique to your operation. An agent focused on trucking knows that bobtail insurance, non-trucking liability, and trailer interchange coverage address real operational blind spots, not optional add-ons.

They understand how your USDOT inspection history, driver hiring practices, and route selection influence underwriting decisions and premium pricing. Start your search by asking prospective agents specific questions about their trucking experience, which carriers they represent, and how they’ve handled claims for similar fleets.

Request Detailed Comparisons Across Multiple Carriers

Agents who can articulate the difference between collision and comprehensive coverage, explain why cargo coverage matters for your specific commodities, and discuss how safety technology like dashcams and telematics influence premiums demonstrate genuine trucking expertise. Request a detailed comparison of coverage limits and deductibles across at least two carriers before committing.

Inszone’s 2025 guidance emphasizes starting renewal submissions 120 to 180 days before expiration with clean loss runs and detailed risk information to improve pricing leverage. An experienced trucking agent handles this timeline and documentation, positioning your fleet competitively across the market rather than accepting the first quote. We at Briggs Agency, Inc. represent multiple carriers, allowing our local agents to compare options that match your specific fleet profile and budget.

Final Thoughts

Your commercial trucking insurance costs reflect factors you control-fleet size, driver hiring practices, vehicle age, safety records, and route selection-plus market conditions beyond your influence. In 2025, liability renewal rates climb 7 to 20 percent across the industry, with larger increases hitting fleets that carry adverse loss histories or high-hazard goods. Physical damage renewals track flat to 10 percent higher, while cargo coverage may see flat to 12 percent increases driven by ongoing theft risk and rising claim costs.

Compact list summarizing expected 2025 trucking insurance renewal rate changes in the U.S.

Coverage limits and deductible choices shape your actual protection when claims happen. Accepting higher deductibles reduces monthly payments but increases your out-of-pocket exposure after an accident. Choosing limits that match your cargo value and operational footprint prevents the catastrophic gap between what your policy covers and what you owe following a major claim.

Schedule a policy review annually or whenever your operation changes materially. An agent who understands trucking identifies coverage gaps, spots premium increases that signal market shifts, and adjusts your limits and deductibles to match your current risk profile. Contact Briggs Agency, Inc. today for a customized quote that reflects your actual operation, not industry averages.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Small Contractor Insurance Plans: Affordable, Flexible Coverage

Running a contracting business means managing countless moving parts, and insurance shouldn’t be one of the headaches. Small contractor insurance plans give you the protection you need without draining your budget.

At Briggs Agency, Inc., we’ve helped contractors across the region find coverage that actually fits their operations. The right insurance protects your business, your team, and your assets when something goes wrong.

The Coverage Every Contractor Must Have

Why General Liability Protects Your Business

General liability coverage protects you from claims when someone gets injured or their property gets damaged because of your work. Construction sites are inherently risky environments, and one accident can cost tens of thousands in medical bills, legal fees, and court judgments. Most states require you to carry general liability to get licensed, and clients routinely ask for proof of coverage before hiring you. The coverage includes bodily injury, property damage, and personal injury claims, with the insurer handling defense costs and settlements. Without it, you remain personally liable for everything, which means your personal assets face direct risk.

Workers’ Compensation: A Legal Requirement

Workers’ compensation is equally non-negotiable if you have employees. Every state except Texas requires contractors to carry workers’ comp, and the penalties for operating without it are severe-fines, license suspension, and personal liability if an employee gets hurt. Workers’ comp covers medical expenses and lost wages, protecting both your team and your business from financial devastation. According to OSHA data, falls account for roughly one-third of construction fatalities, which underscores why this protection matters beyond compliance.

Equipment and Tools Need Their Own Coverage

When you manage crews on multiple job sites, you also need tools and equipment coverage. Most general liability policies exclude your own tools and equipment, leaving you vulnerable if something gets stolen from a job site or damaged during transport. Adding inland marine or equipment protection to your policy covers repair or replacement costs for gear under your care, which is especially important if you run high-value equipment across different locations.

Additional Coverages That Round Out Your Protection

Beyond these core coverages, commercial auto insurance is essential if you own any vehicles used for business. Personal auto policies won’t cover company vehicles, leaving you exposed to liability and property damage claims. Many contractors also benefit from commercial property coverage to protect their office space, storage facilities, and materials on-site. As your business grows, you might need umbrella coverage for additional liability protection beyond your general liability limits.

Checklist of core insurance coverages contractors commonly need - Small contractor insurance plans

Finding the Right Mix for Your Operation

The key is assessing your actual risk exposure based on the types of jobs you take, where you work, and how many employees you have. Quotes vary significantly depending on these factors, so getting multiple quotes from different carriers gives you a realistic picture of what protection costs. Your specific job sites and risk factors determine which coverages matter most for your operation.

The Core Coverage Your Contracting Business Actually Needs

General Liability: Your Foundation

General liability forms your foundation, but it represents only one piece of your protection strategy. This coverage protects you when a client or bystander gets hurt on your job site or when your work damages someone else’s property. The policy pays for medical bills, legal defense, and court judgments-expenses that can easily exceed $50,000 on a single claim. However, this coverage has a critical gap: it does not protect your own tools, equipment, or materials.

Summary of what contractor general liability includes and excludes - Small contractor insurance plans

If someone steals your power tools from a job site or your equipment gets damaged during transport, general liability will not cover the loss.

Equipment Protection Fills the Gap

Inland marine coverage or equipment protection fills this gap effectively. This coverage covers tools and equipment that a contractor uses to complete a project, which matters especially if you work across multiple locations. The cost to add equipment coverage typically runs $30 to $50 monthly depending on your equipment inventory, making it one of the most affordable add-ons available. This protection proves invaluable when you manage crews on multiple job sites and move tools regularly between locations.

Workers’ Compensation: Mandatory and Essential

Workers’ compensation is mandatory in 49 states if you have employees, and it represents the second non-negotiable piece of your coverage. This coverage pays medical expenses and replaces lost wages when an employee gets injured on the job, protecting both your team and your business from financial ruin. According to OSHA data, falls account for roughly one-third of construction fatalities, which shows why this protection matters beyond legal compliance. Operating without workers’ comp carries steep penalties including fines, license suspension, and personal liability if an employee sues.

Commercial Auto and Property Coverage

Commercial auto insurance becomes essential once you own vehicles used for business purposes, since personal auto policies explicitly exclude commercial use. If you drive a company truck to job sites or use a van to transport crew, commercial auto coverage protects you from liability and property damage claims that would otherwise come out of your pocket. Many contractors overlook this coverage until they have an accident, at which point their personal policy denies the claim. Property coverage for your office, storage facilities, and on-site materials rounds out your protection, particularly if you maintain inventory or store equipment at a fixed location.

Choosing Coverage That Matches Your Operation

The coverage that matters depends entirely on your operation’s size, the types of jobs you take, and whether you have employees on payroll. Getting multiple quotes from different carriers gives you a realistic picture of what protection costs and helps you identify which coverages align with your actual risk exposure. Your specific job sites and risk factors determine which add-ons make sense for your business, which is why working with an agent who understands contractor operations helps you avoid paying for coverage you don’t need while ensuring you don’t skip protection you do.

How to Choose the Right Coverage for Your Contracting Business

Assess Your Specific Job Sites and Risk Factors

Start by mapping out your actual job site exposure exactly. Are you doing residential remodeling, commercial construction, or a mix of both? Do you work primarily in one county or across multiple regions? How many employees are on your payroll, and do you use company vehicles daily? The answers to these questions directly determine which coverages you actually need and which ones you can skip.

Hub-and-spoke showing key contractor risk factors that influence insurance needs

A solo electrician working on residential jobs in one area faces entirely different risks than a general contractor managing multiple crews across three counties. Insurance companies price based on exposure, so vague coverage choices cost you money. Spend time documenting your typical projects, the number of people on your team, equipment inventory value, and vehicle usage. This information becomes your baseline for requesting accurate quotes.

When you call carriers or work with an agent, having these specifics ready means you get quotes that reflect your real operation, not a generic contractor profile. Your job site locations, project types, and crew size all influence what protection you actually need.

Compare Quotes from Multiple Carriers

Rates vary dramatically between carriers for identical coverage. One company might charge $1,200 annually for general liability while another charges a different amount for the same limits and protection. The difference often reflects how each carrier evaluates your specific risk profile and claims history.

Request quotes from at least three different carriers using the exact same coverage limits and deductibles so you can make true comparisons. When you receive quotes, look beyond the premium price and examine what each policy actually covers, what exclusions exist, and what add-ons cost. Some carriers bundle equipment coverage into their base rates while others charge separately.

Workers’ compensation rates are determined based on several variables, including your industry, classifications, total payroll, and claims history. Comparing quotes shows you which carrier offers the best rate for your specific employee roles. This comparison approach takes more time upfront but saves you money over the life of your policies and prevents coverage gaps that could cost thousands.

Work with a Local Agent Who Understands Contractor Needs

A local agent who understands how contractors operate in your region matters more than most people realize. An agent knows which carriers are easiest to work with when you need to add a certificate of insurance quickly, which companies handle claims efficiently, and which ones have experience with the specific types of work you do. They also understand local licensing requirements and can verify that your coverage aligns with what your state requires.

An agent familiar with contractor operations knows that you might need temporary coverage for a short-term job or that you might need to adjust your employee count seasonally. They can set up your policy to handle these changes without forcing you through lengthy underwriting each time. A good agent also catches gaps in coverage that contractors commonly overlook (like the fact that your general liability doesn’t cover your own equipment or that commercial auto coverage doesn’t apply to personal vehicles even when you use them for work occasionally).

At Briggs Agency, Inc., we represent multiple top-rated carriers, which means we can pull quotes from several companies simultaneously and show you where you get the best value for your protection. Our experienced local agents understand the contractor operations in our community and help you avoid paying for coverage you don’t need while protecting against gaps that could cost thousands.

Final Thoughts

Small contractor insurance plans work best when they match your actual operation, not some generic contractor profile. The coverage you need depends on your job sites, your team size, and the types of projects you take on. General liability forms your foundation, workers’ compensation protects your employees and your business, and equipment coverage fills gaps that most contractors overlook until something goes wrong.

Getting multiple quotes from different carriers reveals where you find real value, since rates vary significantly between companies for identical coverage. The cheapest option isn’t always the best protection, especially when a single claim can cost tens of thousands in medical bills, legal fees, and court judgments. Comparing quotes takes time upfront but saves money over the life of your policies.

We at Briggs Agency, Inc. help contractors across Indiana find affordable coverage that actually protects their business and assets. Our experienced local agents understand contractor operations and help you avoid paying for coverage you don’t need while protecting against gaps that could cost thousands. Contact Briggs Agency, Inc. today to discuss your contractor insurance needs and get quotes that reflect your real operation.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
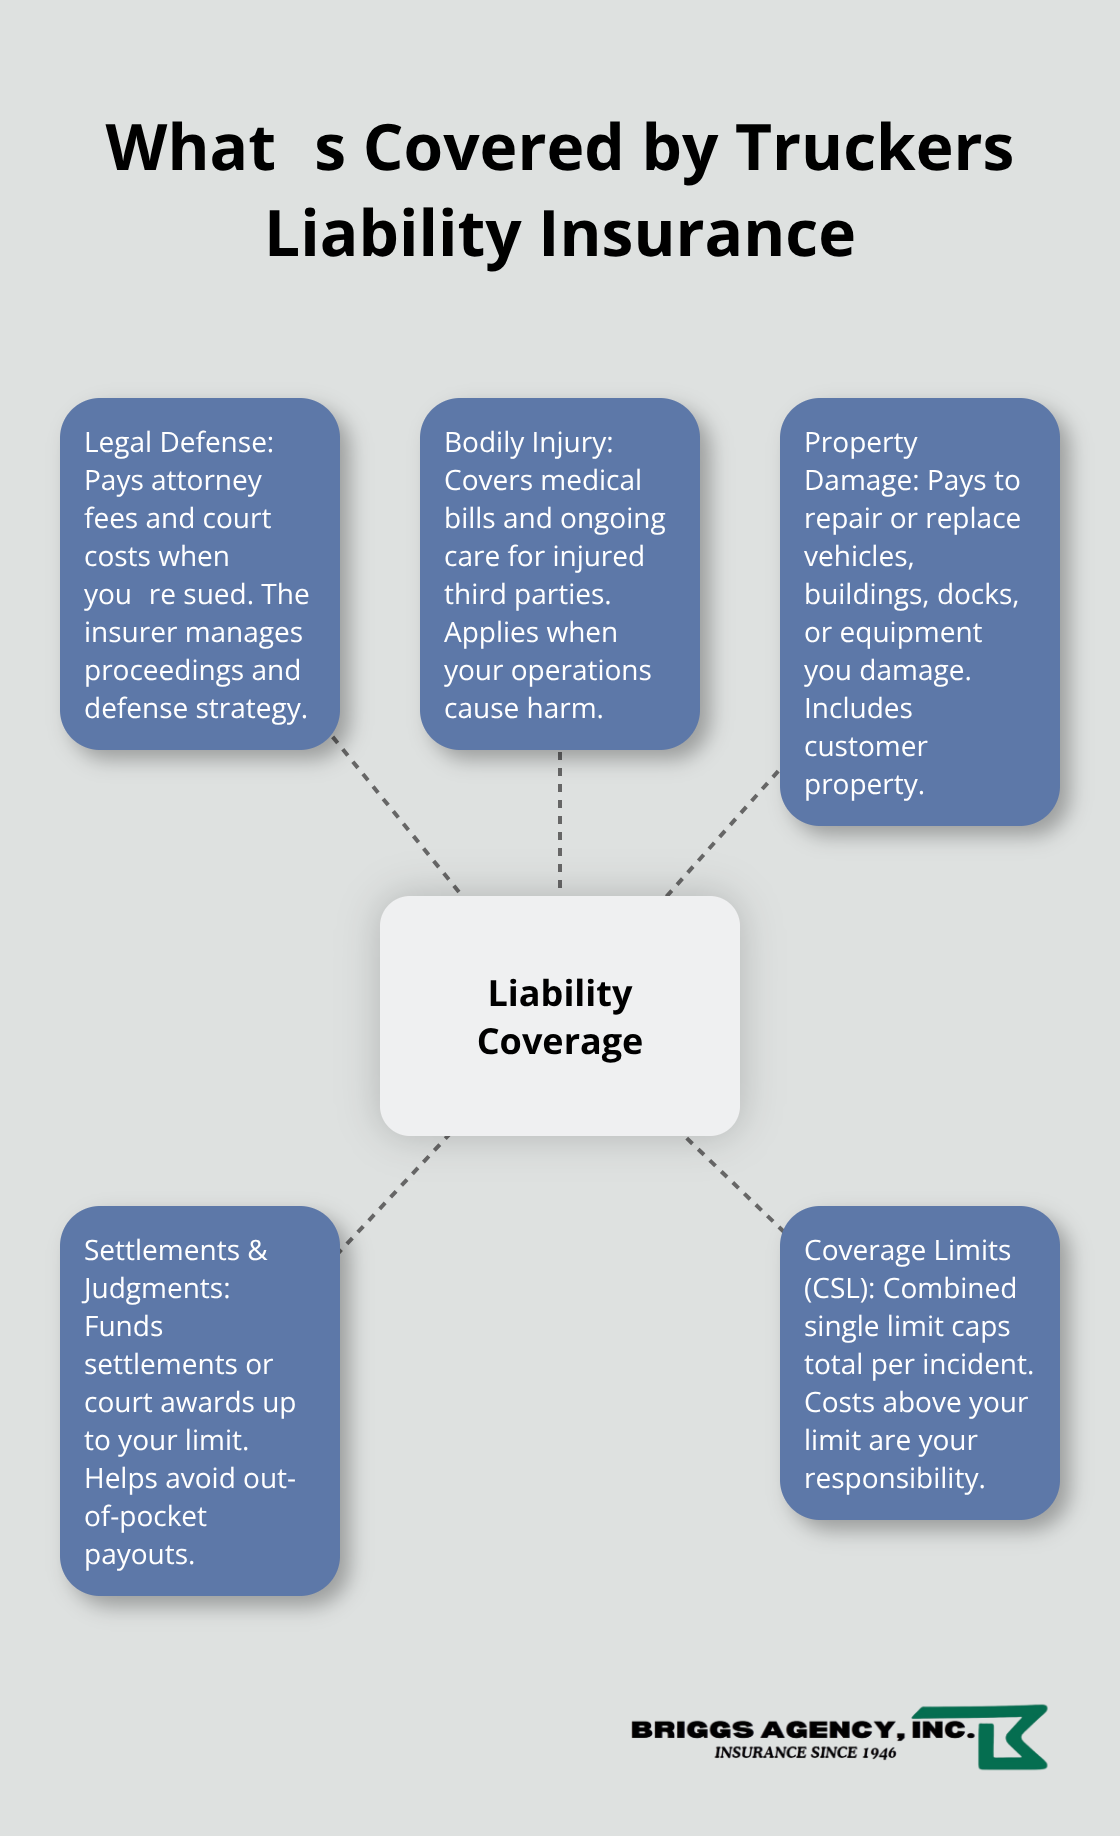
Crown Point Contractor Insurance: Local Builders Deserve Strong Coverage

Running a contracting business in Crown Point means managing more than just schedules and crews-you’re also responsible for protecting your operation from real financial risk. At Briggs Agency, Inc., we work with local builders who understand that standard policies often leave dangerous gaps in coverage.

The right Crown Point contractor insurance isn’t one-size-fits-all. Your specific trade, equipment, and job sites demand a policy built around your actual needs, not generic templates.

The Three Coverages That Actually Protect Your Bottom Line

General Liability Forms Your Foundation

General liability sits at the foundation of any contractor operation, and Indiana law doesn’t require it-but your clients and municipalities do. The Hartford reports that general liability averages around $113 per month for contractors, though this varies significantly based on your trade and claims history. A single property damage claim on a job site can easily exceed $50,000 once investigation and defense costs pile up, which is why you should carry at least $1 million per occurrence for residential work in Crown Point. Commercial projects typically demand $2 million or higher, and if you handle demolition, excavation, or work on historic properties with asbestos or lead paint exposure, your limits should reflect that elevated risk.

Visual summary of general liability, workers’ compensation, and tools & equipment coverage for Crown Point contractors

Two property damage claims within three years can spike your next quote by 20 to 35 percent, making loss prevention and accurate reporting essential to keep premiums manageable.

Workers’ Compensation Is Mandatory, Not Optional

Indiana requires workers’ compensation the moment you hire your first employee, with penalties reaching $10,000 per violation if you skip it. A five-person carpentry crew typically pays between $35,000 and $55,000 annually depending on classification and safety record, which sounds steep until you realize that a single serious injury claim costs multiples of that amount. The Indiana Department of Labor enforces this strictly, and misclassifying crew members to lower premiums triggers audits that result in back payments plus higher rates going forward.

Percentage savings from strong EMR for construction contractors - Crown Point contractor insurance

Your experience modification rate, or EMR, shows how many workers’ comp claims a construction company has compared to others doing similar work; a clean five-year safety record can push your EMR below 1.0, cutting costs by 5 to 15 percent. Contractors who document their safety programs and maintain incident-free years qualify for meaningful discounts that offset the cost of proper coverage.

Tools and Equipment Demand Dedicated Protection

Standard property policies exclude tools left at job sites, which creates a critical gap for Crown Point contractors. Tools and equipment theft costs Indiana contractors between $2,500 and $8,000 per incident, and theft rates in Indianapolis and Gary run about 18 percent higher than the national average, according to the National Equipment Register. Inland marine coverage or dedicated tools and equipment policies typically cost 3 to 5 percent of your equipment value annually and cover theft, vandalism, and accidental damage. You should maintain a detailed inventory with serial numbers and photos of every major tool and piece of equipment; this cuts claim processing time significantly after a loss and proves ownership when theft occurs. If you transport equipment regularly, make sure your commercial auto policy includes hired and non-owned auto coverage, since standard auto policies often exclude contractor vehicles and trailers.

Coverage Gaps Extend Beyond the Basics

Most contractors focus on these three pillars and miss the exposures that actually drain cash when claims happen. Your liability limits may sound adequate until a third-party claim from a neighbor or property owner lands on your desk, and suddenly you face defense costs of $10,000 to $25,000 before fault is even determined. Bodily injury claims on a construction site can exceed $100,000 and may reach into the millions, especially with larger crews or higher-risk work. Historic property renovation adds another layer of complexity; asbestos, lead paint, and mold exposure require specialized pollution liability coverage that standard policies simply don’t touch. The gap between what you think you’re covered for and what actually protects your business is where most contractors stumble-and where the real financial damage happens.

Where Contractors Underestimate Their Real Liability Exposure

The Gap Between What You Think You’re Covered For and What Actually Protects You

Most Crown Point contractors carry general liability limits that look reasonable on paper but crumble when an actual claim hits. You might think $1 million in coverage feels safe for residential work, but many contractors underestimate the actual dollar exposure when homeowner and client lawsuits average $150,000 to $400,000 per claim. Investigation costs, legal defense, and the time your crew sits idle while claims process add up fast. The real problem surfaces when multiple claims stack up; two property damage incidents in three years can push your next premium up 20 to 35 percent, which means your “affordable” policy becomes expensive quickly. If you’re doing commercial projects or any work involving demolition, excavation, or historic properties with asbestos and lead paint, your $1 million limit isn’t just tight-it’s inadequate. Commercial clients routinely require $2 million per occurrence and $2 million aggregate, and many won’t let you on site without proof. If you’re currently operating at the minimum and a single bodily injury claim exceeds your limit, you personally cover the gap, which can devastate your business and personal assets.

Why Umbrella Policies Protect More Than You Realize

Umbrella policies sit unused in most contractor portfolios, which is a costly mistake given how fast construction claims spiral. A $1 million or $2 million umbrella policy costs roughly $300 to $600 annually and sits above your general liability, workers’ compensation, and commercial auto policies to catch claims that exceed those underlying limits. Third-party claims from neighbors, property owners, or other contractors require separate exposure analysis; defense costs alone can hit $10,000 to $25,000 before anyone determines fault.

Key reasons umbrella insurance protects contractors beyond base policies - Crown Point contractor insurance

Bodily injury claims on a construction site routinely exceed $100,000, and your commercial auto coverage tends to be weak. Indiana’s minimums of 25/50/25 are dangerously low, and most contractors carrying only those limits face serious exposure if an employee causes a serious accident while driving for work. Try for at least $100,000 per person and $300,000 per accident, and add hired and non-owned auto coverage if your crew operates any vehicles for business.

The Hidden Exposures in Your Vehicle and Equipment Coverage

Vehicles and trailers parked at job sites often sit uninsured for theft and vandalism because standard commercial auto policies exclude stationary equipment and tools left overnight. Inland marine coverage fills this gap and protects mobile equipment, trailers, and tools in transit or stored on site from theft, vandalism, and accidental damage. When you’re shopping quotes, press each carrier to confirm exactly what’s excluded from your auto and property coverage; most contractors discover gaps only after a loss, which is far too late. Understanding these exposures now positions you to build coverage that matches your actual job sites and equipment, rather than discovering shortfalls when a claim arrives.

Why Local Insurance Expertise Changes Your Bottom Line

Crown Point contractors operate in a specific regulatory environment that generic online quotes completely miss. Indiana has no statewide general contractor licensing board, which means local municipalities set their own requirements, and Crown Point’s rules differ from Fort Wayne’s or Evansville’s. Crown Point projects may require specific coverage limits, surety bonds, or additional insured endorsements that a national carrier’s template policy doesn’t accommodate. When you work with a local agent who understands Lake County building codes and Crown Point’s particular claim patterns, you avoid the costly mistakes of over-insuring unnecessary exposures or under-insuring the real risks you face.

Local Agents Know What National Carriers Miss

An agent familiar with your area knows which carriers consistently pay claims quickly, which ones audit aggressively on payroll classifications, and which ones offer meaningful discounts for documented safety programs. Shopping multiple carriers matters enormously; identical coverage can vary by 30 to 50 percent in price across different insurers. A contractor paying $500 per month with one carrier might find the same protection for $250 with another, simply because that carrier has fewer claims in Crown Point or offers a discount for your specific trade classification.

Trade-Specific Coverage Protects Your Real Exposures

Your trade demands customized coverage that mass-market policies ignore. A carpentry crew faces different exposures than an excavation operation or a plumbing contractor doing historic property renovations. If you handle demolition or work on older Crown Point homes with potential asbestos or lead paint, standard general liability doesn’t cover pollution liability, and your premium should reflect that specialized risk. A local agent compares quotes from carriers that actually compete for contractor business in Crown Point rather than those charging premium rates for out-of-area risk.

Coverage That Grows With Your Business

When your operation expands-you hire more crew, purchase expensive equipment, or win larger commercial projects-a local agent adjusts your policy proactively rather than leaving gaps you discover after a claim. The difference between proper planning and the right insurance and a generic quote often amounts to hundreds of dollars annually, plus better claims service and fewer coverage disputes when something goes wrong. An independent agency representing multiple top-rated carriers walks contractors through the specifics of their actual job sites, crew size, equipment values, and project types to build a policy that protects what matters without padding unnecessary limits.

Final Thoughts

The foundation of a protected contracting business starts with understanding what you face on every job site. General liability, workers’ compensation, and tools and equipment coverage form the core, but the gaps between what you think you’re covered for and what actually protects your business create real financial damage. A single claim can exceed your limits, a theft can wipe out equipment you didn’t insure separately, or a regulatory requirement you missed can shut down a project before it starts.

Your next step is straightforward: pull your current policies and compare them against the exposures we’ve outlined. Do your liability limits match your project types? Are your vehicles and trailers actually covered for theft and vandalism? Does your workers’ compensation classification match your crew’s actual duties? If you’re uncertain about any of these, that uncertainty itself signals a red flag worth addressing now rather than after a claim.

We at Briggs Agency, Inc. represent multiple top-rated carriers, which means we can compare options and tailor Crown Point contractor insurance to your actual operation rather than forcing you into a template. A free quote takes minutes, and the difference between what you’re paying now and what proper coverage actually costs often surprises contractors in the best way possible. Contact us at 219-769-4840 or visit Briggs Agency to start building the protection your contracting business deserves.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.