Insurance for Freelancers: Protecting Your Business and Income

💼 Insurance for Freelancers: Protecting Your Business and Income

Freelancing offers freedom — you choose your clients, projects, and schedule. 🌟 But with that freedom comes responsibility. Unlike traditional employees, freelancers don’t have an employer providing benefits or safety nets like health, liability, or income protection insurance.

That’s why understanding and investing in the right types of insurance is critical to protect your business, income, and reputation. Let’s break down what every freelancer should consider. 👇


🧾 1. Why Insurance Matters for Freelancers

When you’re self-employed, you are the business. If something goes wrong — an accident, client dispute, or illness — it can impact your ability to earn and your financial stability.

Insurance helps freelancers:
✅ Protect personal and business assets
✅ Cover legal fees or claims from clients
✅ Replace lost income during illness or injury
✅ Build credibility with clients who prefer insured contractors

It’s not just a safety net — it’s part of being a professional.


⚖️ 2. Professional Liability (Errors & Omissions) Insurance

Professional Liability Insurance (also called Errors & Omissions or E&O Insurance) is one of the most important coverages for freelancers who provide services or advice.

Why it matters:
If a client claims your work caused them financial loss — due to an error, delay, or oversight — they could sue. Even if you’re not at fault, legal defense costs can be massive.

Covers:

  • Professional mistakes or negligence

  • Missed deadlines or contractual breaches

  • Legal defense costs and settlements

Examples:

  • A designer forgets to include required branding elements in a campaign

  • A consultant gives advice that leads to unexpected losses

💡 Tip: Many corporate clients require proof of this insurance before signing contracts.


💻 3. General Liability Insurance

While professional liability protects against mistakes in your work, general liability covers physical incidents or third-party claims.

Covers:

  • Property damage you cause during work

  • Bodily injury to others (e.g., someone trips in your workspace)

  • Personal injury claims (like slander or libel)

Even if you work from home, this policy can protect you if a client visits your office or you work on-site.


💼 4. Business Property & Equipment Insurance

Your tools are your livelihood — laptop, camera, drawing tablet, or sound equipment. If they’re damaged, lost, or stolen, you can’t work.

Business property insurance (sometimes called equipment coverage) helps cover repair or replacement costs.

Options:

  • Add a business rider to your home insurance

  • Or buy standalone business property insurance

💬 Example: If your laptop gets stolen at a coffee shop or damaged during travel, this coverage can help you bounce back fast.


💰 5. Income Protection / Disability Insurance

If illness or injury prevents you from working, income protection (or disability insurance) replaces part of your income.

This is especially important for freelancers — there’s no sick leave or employer benefits.

Why it’s essential:

  • Helps pay bills and expenses while you recover

  • Can provide short-term or long-term coverage

  • Keeps your business afloat during health setbacks


🧑‍💻 6. Cyber Liability Insurance

Freelancers often handle sensitive client data or rely on digital platforms. A data breach, phishing scam, or cyberattack can lead to serious losses.

Covers:

  • Costs to restore data or systems

  • Legal fees for data privacy violations

  • Notifying clients of breaches

  • Cyber extortion or ransomware

💡 Especially important for tech freelancers, web developers, and consultants working with confidential information.


🌍 7. Health Insurance & Life Insurance

In many countries, freelancers must secure their own health coverage. Without it, a medical emergency could be financially devastating.

Consider:

  • Private or public health insurance plans

  • Supplemental dental and vision coverage

  • Life insurance if you have dependents or long-term financial obligations


📋 8. Optional Add-Ons

Depending on your work type and risk level, consider:

  • Business interruption insurance – replaces income during major disruptions (like fire or disaster)

  • Travel insurance – for freelancers who work or meet clients abroad

  • Legal expense insurance – covers the cost of hiring an attorney for disputes or contracts


✨ Final Thoughts

Freelancing offers independence — but it also means you’re your own safety net. Having the right insurance protects your business, income, and peace of mind.

Start by assessing your risks, comparing policies, and choosing coverage that fits your profession and budget.

💬 In short: Protect your hustle today, so your freedom lasts tomorrow. 💪

You can experience the benefits of being a part of a full-serviced Independent Insurance Agency today! Simply contact Briggs Agency, Inc if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com.We look forward to hearing from you!

Blog post written by: Zachary Pelke
The Importance of Professional Liability Insurance for Consultants

The Importance of Professional Liability Insurance for Consultants

So, you’ve built a career as a consultant. You’ve got the know-how, the laptop, the coffee habit, and a growing client list. You help businesses solve problems, streamline operations, or scale to new heights. But here’s something you may not have on your radar — professional liability insurance.

It may not sound as exciting as landing your next big client or redesigning a workflow, but it might just be the most crucial business decision you’ll make. Let’s unpack why.


What Is Professional Liability Insurance Anyway?

Professional liability insurance (also known as errors and omissions insurance or E&O insurance) is a specialized type of coverage designed to protect professionals who provide advice or services.

In short:
It’s your financial safety net if a client claims that your work caused them a loss — even if you didn’t actually do anything wrong.

Think of it as a shield between you and a costly lawsuit that could derail your consulting business. Because let’s face it — in today’s litigious world, even the most meticulous consultant can be accused of negligence, errors, or misrepresentation.


Why Consultants Need Professional Liability Insurance

Consultants of all types — management, marketing, IT, HR, design, finance — face risks every single day. You’re hired to provide expertise, but that expertise carries expectations. And sometimes, things don’t go according to plan.

Here’s why you need this protection:

1. Mistakes Happen (Even to the Best of Us)

You might give advice that doesn’t deliver the intended results. Maybe a client misinterprets your recommendations, or a small oversight causes a project delay. If a client claims your work caused them financial loss, they could sue.
Professional liability insurance helps cover legal defense costs, settlements, and judgments, so one slip-up doesn’t sink your business.

2. Client Contracts Often Require It

Many corporate clients or government agencies won’t even work with consultants who don’t carry professional liability insurance. They see it as a mark of professionalism — proof that you’re serious about your work and financially prepared if things go sideways.

So, in many cases, having this coverage isn’t just protection — it’s a competitive advantage.

3. Lawsuits Are Expensive — Even When You’re Right

Let’s say a client accuses you of negligence, but you’re completely in the clear. You still need to hire a lawyer, respond to the claim, and possibly go to court. Those costs add up fast.
Professional liability insurance covers legal defense costs, even if the claim has no merit.

4. Your Reputation Is Everything

A lawsuit can tarnish your reputation — but handling it swiftly and professionally can preserve trust. Having insurance allows you to manage claims efficiently and keep your consulting practice running smoothly.

5. Peace of Mind Is Priceless

Let’s be honest — consulting is already stressful enough. The last thing you want to worry about is a “what if” scenario that could financially cripple your business. Knowing you’re covered means you can focus on what you do best: helping clients succeed.


What Does Professional Liability Insurance Cover?

Coverage can vary depending on your policy, but here’s what it typically includes:

  • Negligence: Protection if you’re accused of not performing your duties as expected or making an error that causes a loss.

  • Misrepresentation: Coverage if a client claims you gave false or misleading advice.

  • Violation of Good Faith and Fair Dealing: If a client believes you acted unfairly or didn’t uphold contractual obligations.

  • Defense Costs: Legal fees, court costs, and settlement expenses.

  • Claims and Damages: Payment for settlements or judgments against you (up to your policy limits).

However, it doesn’t usually cover:

  • Intentional wrongdoing or criminal acts

  • Bodily injury or property damage (that’s what general liability insurance is for)

  • Employee disputes (that’s covered by employment practices liability insurance)


A Quick Example: Why It Matters

Imagine you’re an IT consultant. You recommend a new software platform for a client, but after implementation, the system crashes and causes days of downtime. The client blames your recommendation for their losses — even though the failure was due to their outdated servers.

They sue for $100,000 in damages.
Without insurance, you’d pay for legal fees and potential settlements out of pocket.
With professional liability insurance, your policy steps in to cover those costs.

See the difference?


Choosing the Right Coverage

When shopping for professional liability insurance, consider:

  • Your industry and risk level: Some consulting fields (like finance or IT) face higher risks than others.

  • Coverage limits: Typical policies range from $250,000 to several million dollars in coverage.

  • Deductibles: Know what you’ll pay out-of-pocket before your insurance kicks in.

  • Retroactive coverage: Make sure your policy covers past work (some claims can arise years later).

Working with an experienced insurance broker who understands your industry can help tailor a policy that fits your needs.


Final Thoughts

Being a consultant means being an expert, a problem-solver, and sometimes — a risk-taker. But one risk you shouldn’t take is going uninsured.

Professional liability insurance isn’t just another line item in your budget — it’s a smart investment in your business’s stability, reputation, and future. It allows you to consult with confidence, knowing that if something goes wrong, you’re protected.

So, before your next client meeting or project kickoff, take a moment to ensure you’ve got the right coverage in place. Your future self (and your bank account) will thank you.

You can experience the benefits of being a part of a full-serviced Independent Insurance Agency today! Simply contact Briggs Agency, Inc if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgemcy.com. We look forward to hearing from you!

Blog post written by: Zachary Pelke
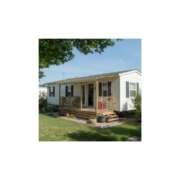
Insurance for Mobile Homes: What You Need to Know?

🏠 Insurance for Mobile Homes: What You Need to Know

Owning a mobile home (or manufactured home, as the pros call them) offers a lot of freedom and affordability. Whether you’ve got your dream home set up in a peaceful community or on your own land surrounded by trees, protecting it with the right insurance is essential.

But here’s the thing: mobile home insurance isn’t quite the same as standard homeowners’ insurance. There are a few quirks, coverage options, and important considerations to know before you sign on the dotted line.

Let’s break it all down in plain English — and make sure your home-on-wheels (even if it never moves) is covered from top to bottom.


🧱 What Exactly Is Mobile Home Insurance?

Mobile home insurance is a specialized type of homeowners insurance designed for manufactured or modular homes. Since mobile homes are built differently from traditional houses — and sometimes located in parks or communities with unique risks — they need a tailored insurance policy.

Most insurers offer it as a “mobile home policy” (HO-7), which is similar to a standard homeowners (HO-3) policy but with key differences in coverage and construction considerations.


💡 What’s Covered? The Core of Your Policy

Here’s what most mobile home insurance policies typically include — and what you’ll want to look for:

1. Dwelling Coverage

This covers the structure of your mobile home itself — the walls, roof, and any attached structures (like decks or porches).
It protects you from covered perils such as fire, hail, windstorms, or vandalism.

👉 Pro tip: Make sure the coverage amount reflects the replacement cost of your home, not just its current market value. Mobile homes depreciate, so a replacement-cost policy ensures you can rebuild, not just get a check for less than what you need.


2. Personal Property Coverage

This is all about your stuff. Furniture, electronics, clothing — even that fancy coffee maker you can’t live without.
If your belongings are damaged or stolen, this part of your policy helps replace them.

💬 Tip: Take photos or keep a digital inventory of your belongings. It makes filing a claim much easier if the worst happens.


3. Liability Protection

Let’s say a guest slips on your steps or your dog knocks someone over — liability coverage protects you financially if someone is injured on your property or if you accidentally cause damage to someone else’s property.

It can also help pay for legal fees if you’re sued.


4. Additional Living Expenses (ALE)

If your mobile home becomes uninhabitable after a covered loss (like a fire or major storm), ALE coverage helps pay for temporary housing, meals, and other living costs while repairs are being made.

That way, you’re not stuck couch-surfing indefinitely.


⚡ Optional (and Highly Recommended) Add-Ons

Mobile homeowners face some unique risks. Depending on your location and lifestyle, you may want to add a few extra layers of protection:

  • Flood insurance: Most standard policies don’t cover flooding — and mobile homes are often more vulnerable to it. If you live in a flood-prone area, this is a must-have.

  • Earthquake insurance: Also, not typically included, but important if you live near fault lines.

  • Trip collision coverage: If you plan to move your mobile home, this covers damage that might occur during transport.

  • Sewer backup coverage: Gross? Yes. Necessary? Also, yes. This protects you from damage caused by backed-up drains or sump pumps.

  • Extended replacement cost: Covers rebuilding your home even if the cost exceeds your dwelling limit (great for inflation protection).


🏘️ Special Considerations for Mobile Homeowners

🔩 Age and Condition Matter

Older mobile homes — especially those built before 1976 (the year HUD set national construction standards) — may be harder or more expensive to insure. Some insurers might require an inspection before issuing coverage.

🌪️ Location, Location, Location

Where your mobile home sits play a huge role in your rates and eligibility. Homes in coastal, hurricane, or tornado-prone areas will have higher premiums — or may require special wind/hail deductibles.

🔒 Community vs. Private Land

If your home is located in a mobile home park or community, check whether the park’s master policy covers certain structures or liability risks. You don’t want to double up on coverage (or miss a gap).

⚙️ Anchoring and Skirting

Insurers love stability (literally). Mobile homes that are properly anchored and skirted are less prone to storm damage — and may qualify for better rates.


💰 How Much Does Mobile Home Insurance Cost?

On average, you can expect to pay $300–$1,000 per year, depending on factors like:

  • Your home’s value and age

  • Location and local weather risks

  • Deductible and coverage limits

  • Security systems or safety features

You can often score discounts for:

  • Installing smoke detectors and storm shutters

  • Bundling with auto insurance

  • Having a good credit score

  • Going claim-free for several years


🔍 How to Choose the Right Policy

When shopping around, compare at least 3 quotes from reputable insurers.
Ask about:

  • Replacement cost vs. actual cash value (replacement cost = better protection)

  • Coverage limits (especially for personal property)

  • Exclusions (flood, earthquake, pest damage, etc.)

  • Deductible options (higher deductibles = lower premiums, but more out of pocket if you file a claim)

And don’t be afraid to ask for clarification. Insurance terms can feel like a foreign language — but understanding your policy now saves a ton of stress later.


🏡 Final Thoughts

Your mobile home is more than just a structure — it’s your home, your comfort zone, your safe place.
The right insurance policy helps protect that investment, giving you peace of mind no matter where life (or the weather) takes you.

So, whether you’re settling down or rolling to a new adventure, take the time to find coverage that truly fits your lifestyle.


Bottom line:
✅ Know what’s covered.
✅ Understand your risks.
✅ Get the right protection.


You can experience the benefits of being a part of a full-serviced Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forwards to hearing from you!


Blog post written by: Zachary Pelke
How to Use an Insurance Agent as Your Advocate?

How to Use an Insurance Agent as Your Advocate (and Why You Should!)

When it comes to insurance, most people think of paperwork, premiums, and policies that sound like they’re written in another language. But what if I told you there’s someone who can do the translating, negotiating, and even fighting on your behalf?

Enter: Your Insurance Agent—Your Personal Advocate.

Whether you’re buying car insurance, homeowners’ insurance, health, or life coverage, having the right insurance agent on your side can save you money, time, and a whole lot of stress. This post will break down exactly how to use your insurance agent as your advocate, not just your sales rep.


What Does an Insurance Agent Actually Do?

An insurance agent is your personal connection to the complex world of insurance. Think of them as your insurance translator, matchmaker, and negotiator rolled into one.

Their key roles:

Role What They Do For You
🧭 Advisor Help you understand what coverage you really need (and what you don’t).
📝 Policy Finder Match you with policies from different carriers (independent agents) or products from one company (captive agents).
🤝 Negotiator Work with insurers to find better rates, discounts, and terms for your specific situation.
🛡️ Advocate Assist with claims, appeals, or disputes and fight for what you’re owed.
📞 Liaison Handle communication with the insurer, so you don’t get lost in phone trees or legalese.

Why “Advocate” is the Most Important Role

It’s easy to think of an agent as a middleman, but a good insurance agent is more like your bodyguard in the insurance world.

Here’s how they advocate for you:

  • During Claims: If your house floods, your car is totaled, or a medical bill spirals out of control, your agent can step in to guide you through the claims process, help you gather documentation, and push the insurer to act quickly and fairly.

  • At Renewal Time: Agents review your coverage, check if rates increased, and even negotiate better premiums or suggest switching companies if there’s a better option.

  • After Denials: If your claim is unfairly denied, they can file appeals or help you escalate the issue.


Real-Life Example: Meet Lisa & Her Agent

Lisa’s Story
Lisa’s basement flooded after a storm. She was stressed, unsure what was covered, and overwhelmed by the insurer’s confusing claims process.

Enter her agent, Mike.

Mike:

  • Reviewed Lisa’s policy and confirmed water damage was covered.

  • Helped her document the damage properly.

  • Called the insurer directly to get the claim expedited.

  • Followed up weekly until Lisa got her full payout.

End result? Lisa got her home repaired faster—and with less out-of-pocket cost than she expected.

Lesson: Without Mike, Lisa might have accepted a lower payout or gotten stuck in red tape.


How to Use Your Agent Like a Pro

Here’s how you can get the most out of your insurance agent as an advocate, not just a policy pusher.

✅ Step 1: Choose the Right Agent

What to Look For Why It Matters
🧠 Experience in your type of insurance They’ll know the tricks of the trade.
🤝 Independent vs Captive Independent agents can shop multiple insurers.
📞 Responsive communication You want someone who calls you back!
🌟 Reviews and referrals Trust matters—especially when you’re in a crisis.

✅ Step 2: Build a Relationship

  • Be honest about your needs and budget.

  • Schedule regular check-ins (especially at renewal time).

  • Don’t ghost them after buying the policy—they can only help if they know what’s going on.

✅ Step 3: Involve Them When Things Go Sideways

  • Call them first when you have a claim or issue.

  • Let them explain what’s covered—and what’s not.

  • Ask for their help in filing and following up on the claim.

  • Get their advice on whether to escalate a dispute.


💡 Pro Tip: Don’t Wait Until You’re in Crisis

The worst time to realize you needed an agent is after a denied claim. A good agent can help prevent problems before they start by:

  • Making sure you have the right coverage.

  • Warning you about exclusions or risky clauses.

  • Advising you on what to do before filing a claim.


Captive vs Independent Agents: What’s the Difference?

Feature Captive Agent Independent Agent
Sells For One company (like State Farm, Allstate) Multiple companies
Product Range Limited to their company Broader range of options
Advocacy Can still advocate—but limited if the company’s policy is strict More flexibility to switch carriers if needed

Both types can advocate for you—but independent agents often have more freedom to move you to a better option if your situation changes.


📊 Quick Look: When to Call Your Agent

Situation Call Your Agent?
You’re buying a new car ✅ Yes – Update policy, explore new discounts
You’re switching jobs ✅ Yes – Health or life insurance may be affected
You had a minor fender bender ✅ Yes – Ask if you should file or pay out-of-pocket
Your premium increased ✅ Yes – See if there’s a better option
Your house caught fire ✅ YES – Immediately! They’ll walk you through everything

🚀 Final Thoughts: Your Insurance Agent = Your Insurance Superhero

You don’t need to face the insurance world alone. When used right, your agent can:

  • Protect you from bad coverage.

  • Help you get paid fairly and fast.

  • Save you money with smart advice.

  • Fight for you when things go wrong.


You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. we look forward to hearing from you.


Blog post written by: Zachary Pelke
The Importance of Reviewing Your Insurance Policy Annually

The Importance of Reviewing Your Insurance Policy Annually 📋

Insurance is one of those things most of us set and forget. Once the policy is signed, the premiums are paid, and the paperwork is filed away, it’s easy to assume everything is handled. But life changes—and so should your insurance.

Conducting an annual review of your insurance policies isn’t just a good habit—it’s essential for making sure you’re protected, not overpaying, and always getting the best value.

Let’s explore why reviewing your insurance each year can lead to better coverage, real savings, and greater peace of mind. ✅


1. Your Life Changes—So Should Your Policy 🔄

A lot can happen in a year:

  • Got married? 💍

  • Moved into a new home? 🏠

  • Bought a car? 🚙

  • Had a baby? 👶

  • Started working from home? 💻

Each of these milestones can impact your insurance needs.

For example:

  • Homeowners insurance should reflect upgrades, renovations, or added valuables.

  • Auto insurance may need updating if your driving habits have changed.

  • Life insurance should be reevaluated after any big family or financial change.

📅 An annual review ensures your coverage grows with your life—not behind it.


2. You Might Be Missing Out on Better Options 

The insurance market is always changing—new products, better rates, improved coverage. What worked last year may not be the best fit today.

During a review, you or your agent can:

  • Compare your current policy to new offers

  • Explore bundling (home + auto = 💸 savings!)

  • Adjust deductibles or limits for better coverage

📈 Staying informed = staying ahead.


3. Premiums Change—Don’t Get Caught Off Guard 

Your premium can go up or down due to:

  • 🚦 Driving history

  • 🧾 Claim activity

  • 💳 Credit score

  • 📈 Inflation or market changes

By reviewing your policy:

  • You might spot unnecessary fees or outdated info

  • You could unlock new discounts for safe driving, home security, loyalty, etc.

  • You can clean up old coverages you don’t need anymore

🎯 Bottom line: Review = potential savings and clarity.


4. Laws and Regulations Change Too ⚖️

Insurance rules aren’t set in stone. Every year, state and federal changes could affect:

  • Minimum coverage levels

  • Tax deductibility (especially for health or life insurance)

  • Policy exclusions or limitations

An annual review keeps you:

  • ✅ Legally compliant

  • 🧠 Well-informed

  • 📊 Prepared for any financial or legal shifts


5. You’ll Understand Your Coverage Better 

Let’s be honest: most of us don’t know exactly what our insurance covers (or doesn’t).

Ask yourself:

  • What’s my deductible?

  • What are my coverage limits?

  • What’s excluded?

  • How do I file a claim if needed?

🎓 A review is a perfect chance to learn—and ask questions while you’re not in a crisis.


6. It Takes Little Time—But Has Big Benefits ⏳➡️💰

An insurance review often takes less than an hour. You can do it:

  • 📞 Over the phone with your agent

  • 💻 Online through your provider’s dashboard

  • ☕ Even casually over coffee with a trusted advisor

For a small-time investment, you get:

  • 🔐 Updated protection

  • 💸 Potential savings

  • 😌 Peace of mind


✅ Final Thoughts: A Little Effort = Big Protection

Your life isn’t static, and your insurance shouldn’t be either. By reviewing your policy once a year, you make sure you’re:

  • Covered for what matters most

  • Not overpaying for things you don’t need

  • Prepared for the unexpected

So go ahead—📅 set that annual reminder. Make it part of your fall checklist or New Year routine. Your future self will thank you.

You can experience the benefits of being a part of a full serviced independent insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: Zachary Pelke
How to Protect Your Business from Liability Risks

🛡️ How to Protect Your Business from Liability Risks: Insurance Tips That Could Save You!

Running a business is risky—but that’s part of the thrill, right? While you’re dreaming big, building your brand, and securing the bag 💼💰, it’s easy to overlook one sneaky threat: liability.

Whether you’re a freelancer, a small business owner, or running a growing startup, liability risks can cost you everything if you’re not prepared. But don’t worry—insurance is your business’s secret superhero cape. 🦸‍♀️🦸

This post breaks down how to protect your business from liability risks with insurance—complete with practical tips, charts, and a sprinkle of fun.


⚠️ What is Liability, Anyway?

Liability is basically what your business could be held legally responsible for—think injuries, damages, or losses that affect clients, employees, or the public.

Common Types of Business Liability:

Type Description Real-Life Example
General Liability Covers bodily injuries, property damage A customer slips on your floor
Professional Liability (E&O) Covers mistakes or negligence You give wrong legal advice
Product Liability Covers harm from your product A toy breaks and injures a child
Cyber Liability Covers data breaches Hackers steal client info
Employment Practices Liability (EPLI) Covers HR-related claims Employee sues for discrimination

🧠 Pro Tip #1: Understand What You’re Exposed To

Before you buy any insurance, assess your risk. Ask:

  • Do I serve clients face-to-face?

  • Do I offer professional advice or services?

  • Do I handle sensitive data?

  • Do I sell physical products?

  • Do I have employees?

💡 Example: A yoga studio and an e-commerce pet store have very different liability risks—and need different insurance setups.


🧾 Pro Tip #2: Get the Right Coverage (Not Just the Cheapest)

Essential Insurance Policies for Most Businesses:

Insurance Type Best For Why You Need It
General Liability All Businesses Covers accidents, injuries
Professional Liability (E&O) Consultants, agencies, freelancers Covers “oops” moments
Business Owner’s Policy (BOP) Small businesses Bundles liability + property insurance
Workers’ Compensation Businesses with employees Covers on-the-job injuries
Cyber Liability Online businesses, SaaS Covers data breaches, hacks

✅ Hot Tip: A Business Owner’s Policy (BOP) is a great budget-friendly combo that includes general liability + property coverage.


📊 CHART: What Insurance Do I Need?

Risk Type | High Risk | Medium Risk | Low Risk
---------------------|-----------------|----------------|---------------
Client Interaction | Retail, salons | Consultants | Online shops
Data Handling | SaaS, IT firms | E-commerce | Brick & mortar
Professional Advice | Lawyers, CPAs | Designers | Product sellers
Product Sales | Toy makers | Crafters | Digital products
Employees | Restaurants | Agencies | Solopreneurs

✅ = Must-have insurance!


🧰 Pro Tip #3: Work With an Insurance Broker

Don’t just Google “cheap business insurance” and click the first ad. 🙃
A licensed insurance broker will:

  • Compare multiple policies

  • Tailor coverage to your industry

  • Help you avoid hidden exclusions

⚠️ Remember: The cheapest policy might not cover you when you actually need it.


🔍 Pro Tip #4: Read the Fine Print (Yes, Seriously)

Insurance policies are filled with jargon, but missing a detail can cost you BIG. Look out for:

  • Exclusions: What’s NOT covered

  • Limits: The max amount they’ll pay

  • Deductibles: What you pay out-of-pocket before coverage kicks in

  • Retroactive Dates: For claims-made policies like E&O

📘 If reading policies feels like decoding ancient scrolls, ask your broker to explain in plain English.


📅 Pro Tip #5: Review Your Coverage Every Year

Your business grows, pivots, and evolves. So should your insurance.

Example: If you start offering a new service (like online coaching or digital products), your current policy might not cover it.

Set an annual “insurance review day” on your calendar. Treat it like a business checkup.


🤑 Bonus: What If You Get Sued Without Insurance?

Without insurance, even one lawsuit could mean:

  • Attorney fees 💸

  • Court settlements 💸💸

  • Reputation damage 🧨

  • Bankruptcy ☠️

It’s not fear-mongering—it’s facts.


🎯 Summary: Liability Protection Checklist

✅ Assess your risks
✅ Choose the right types of insurance
✅ Work with a broker (not just a search engine)
✅ Read and understand the policy
✅ Review and update yearly

You can experience the benefits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if your are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by Zachary Pelke.

Insurance FAQs: Answers to Commonly Asked Questions

🛡️ Insurance FAQs: Quick Answers to Common Questions

Let’s face it—insurance can be confusing. Whether it’s car, home, health, or life insurance, the fine print can make your head spin. That’s why we’ve compiled a list of the most frequently asked insurance questions—along with clear, simple answers. ✅

Ready to demystify insurance? Let’s go! 🚀


1️⃣ What is insurance, really?

Insurance is a contract (a policy) where you pay a company (called the insurer) a fee (called a premium), and in return, they agree to help cover certain losses or damages.

📦 Think of it as a safety net for the “what ifs” in life.


2️⃣ Why do I need insurance?

Because life happens. 💥 Insurance protects you financially in case of:

  • 🚗 Car accidents

  • 🏡 Property damage

  • 🤒 Medical emergencies

  • 💀 Unexpected death

  • 🛫 Travel issues

Without insurance, you could end up paying everything out of pocket. Ouch.


3️⃣ What types of insurance should I have?

Here are the big ones:

  • 🚗 Auto Insurance – Required by law in most places.

  • 🏠 Home or Renters Insurance – Protects your home or belongings.

  • 💊 Health Insurance – Helps pay for medical care.

  • 💼 Life Insurance – Supports your loved ones if you pass away.

  • 🧳 Travel Insurance – Covers trip cancellations, lost bags, etc.

The right mix depends on your life situation.


4️⃣ What’s a deductible?

A deductible is the amount you pay out of pocket before your insurance kicks in. 💸

Example: If your car repair is $2,000 and your deductible is $500, you pay $500 and the insurance covers $1,500.


5️⃣ What affects my insurance premium?

Your premium is what you pay (monthly or yearly). It depends on:

  • 🔢 Age

  • 📍 Location

  • 🚗 Driving record

  • 🏥 Health status

  • 💼 Job or lifestyle risks

Basically, the riskier you are to insure, the more you’ll pay.


6️⃣ What’s the difference between term and whole life insurance?

  • 🕒 Term Life: Covers you for a set time (10, 20, 30 years). Cheaper.

  • ♾️ Whole Life: Covers you forever and builds cash value. Pricier, but comes with benefits.


7️⃣ Can I switch insurance companies?

Absolutely! 🔄 If you find better coverage or a lower rate, you can switch—just make sure there’s no gap in coverage.

Tip: Don’t cancel your old policy until the new one is active. ☝️


8️⃣ What’s not covered by insurance?

Every policy has exclusions. Common ones include:

  • 🚫 Intentional damage

  • 🚫 Wear and tear

  • 🚫 Certain natural disasters (like floods or earthquakes—check your policy!)

Always read the fine print. 🧐


9️⃣ How do I file a claim?

Most insurers let you file:

  • 📱 Online or through an app

  • ☎️ By phone

  • 📝 With a form

You’ll need details like what happened, when, and supporting documents (photos, receipts, etc.).


🔟 When should I update my policy?

Update your insurance when your life changes:

  • 💍 Getting married

  • 👶 Having a baby

  • 🏠 Buying a home

  • 🚘 Getting a new car

  • 💼 Changing jobs

Your needs evolve—so should your coverage.


🎉 Final Thoughts

Insurance isn’t just paperwork—it’s peace of mind. Whether you’re just starting out or reviewing your current policies, knowing the basics helps you stay protected and save money.

Got more questions? Drop them in the comments below or reach out to a licensed agent.


Stay safe, stay smart, stay insured. 🛡️

You can experience the benefits of being a part of a full-serviced Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: Zachary Pelke
Insurance Coverage for Seasonal Homes or Vacation Properties

🏡 Insurance Coverage for Seasonal Homes or Vacation Properties

Protecting Your Second Home the Right Way

Whether your vacation home is a cozy cabin in the mountains, a beachfront retreat, or a lakeside cottage, it deserves the same protection as your primary residence—if not more. Second homes or vacation rentals come with unique risks and insurance needs, and overlooking proper coverage can lead to costly surprises.

In this blog post, we’ll break down everything you need to know about insurance coverage for seasonal homes and vacation properties, including what makes them different, key coverage types, and how to safeguard your investment year-round.


📌 Why Second Homes Need Special Insurance

Unlike your primary residence, second homes:

  • May be vacant for long periods, increasing the risk of theft or damage.

  • Are often located in areas prone to natural disasters (coastal storms, wildfires, etc.).

  • Might be used as short-term rentals, adding liability and property wear risks.

As a result, standard homeowners’ insurance typically won’t provide adequate protection. You’ll likely need a specialized policy tailored to your property’s use and location.


🔍 Types of Coverage for Vacation Homes

Here’s a breakdown of the essential coverage types you should consider:

🏠 1. Dwelling Coverage

Covers the structure of the home in case of damage due to fire, wind, hail, or other covered perils.
💡 Tip: Make sure your policy reflects the full rebuild cost, not just market value.


🪟 2. Contents Coverage

Protects furniture, appliances, and personal belongings inside the home.
📦 Especially important if the home is furnished or used by guests/renters.


🔐 3. Liability Insurance

Provides protection if someone is injured on the property and you’re found liable.
🧯 Extra important if you rent the home out or host guests.


🚰 4. Vacancy and Vandalism Protection

Second homes are often vacant—so consider coverage that includes:

  • Vandalism

  • Theft

  • Frozen/burst pipes
    💡 Some insurers exclude certain perils if the home is left empty for 30+ days.


🌊 5. Flood and Earthquake Insurance

Standard policies do not cover these natural disasters.
✅ Check the risk level in your property’s area and add:

  • Flood insurance (FEMA or private)

  • Earthquake insurance if applicable


💼 6. Rental Property Insurance (Landlord Insurance)

If you rent your vacation home on Airbnb, Vrbo, or privately:

  • You may need landlord insurance or a commercial policy.

  • Covers loss of rental income, property damage, and tenant-related liabilities.

📝 Some insurers offer short-term rental endorsements for occasional rentals.


🧾 Optional Add-Ons to Consider

  • Umbrella Insurance: Extra liability coverage beyond your standard policy

  • Service Line Coverage: Protects underground pipes/wires

  • Home Systems Protection: Covers HVAC, water heaters, etc.

  • Ordinance or Law Coverage: Helps cover costs to bring property up to code after damage


💬 Common Questions

❓ Can I use my primary homeowner’s policy for my vacation home?

No. You’ll need a separate policy or an endorsement. Insurers see second homes as higher risk due to limited occupancy.


❓ Does Airbnb or Vrbo insurance replace my own?

Not fully. They offer limited host protections. You still need your own comprehensive rental property insurance.


❓ How much does second home insurance cost?

Costs vary widely based on:

  • Location and weather risk

  • Home value and age

  • Rental activity
    💰 On average, 10%–20% higher than primary home insurance.


✅ Tips to Lower Insurance Costs

  1. Bundle policies with your auto or primary home

  2. Install security systems, smoke detectors, smart thermostats

  3. Maintain the property regularly

  4. Limit high-risk features (e.g., trampolines, open fire pits)


🏁 Final Thoughts

Your second home is a valuable investment and source of joy—but it comes with its own set of risks. The right insurance policy can offer peace of mind whether you’re enjoying a weekend getaway or renting it out to guests.

🔍 Action Step: Review your current coverage, talk to your insurance agent, and ensure your vacation property is properly protected before the next season hits.

You can experience the benefits of being a part of a full-serviced Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forwards to hearing from you!

Blog post written by: Zachary Pelke
Understanding Business Owner’s Policy (BOP): What is Included?

📦 Understanding Business Owner’s Policy (BOP): What’s Included?

Running a small business comes with a lot of hustles—and a little bit of risk. Whether you’re selling cupcakes, managing a consulting firm, or running an online store, you want to protect what you’ve worked so hard to build. That’s where a Business Owner’s Policy, or BOP, comes in.

Think of a BOP as a bundle of protection designed just for small and medium-sized business owners. It combines several essential types of insurance into one neat package—saving you time, money, and a whole lot of headaches.

Let’s break it down. 🎯


🧰 What Is a Business Owner’s Policy (BOP)?

A Business Owner’s Policy is a bundle of different types of insurance commonly needed by small businesses. Instead of buying each policy separately, a BOP groups them together—usually at a discounted rate.

It’s like getting a meal combo at your favorite restaurant. You could order each item separately but bundling it saves money and effort.


🧩 What’s Included in a BOP?

Most standard BOPs come with three core components:

1. Property Insurance 🏢

This protects your building and business property—like equipment, inventory, furniture, and signage—against damage or loss from:

  • Fire

  • Theft

  • Vandalism

  • Storms (excluding floods or earthquakes)

✅ Example: If a fire damages your office, this coverage helps pay for repairs and replacing lost property.

🔍 Note: You don’t need to own the building to benefit. If you rent, the contents and upgrades you make are covered too.


2. General Liability Insurance ⚖️

This covers legal costs if your business is sued for things like:

  • Bodily injury (e.g., a customer slips and falls in your store)

  • Property damage (e.g., you accidentally damage a client’s laptop)

  • Advertising injury (e.g., you’re accused of copyright infringement)

✅ Example: A customer trips on a loose rug in your boutique and breaks their wrist. General liability covers medical expenses and legal fees.

📢 Important: It does not cover employee injuries (you’ll need workers’ comp for that).


3. Business Interruption Insurance 🛑

Also called “Business Income Insurance,” this coverage helps you recover lost income if your business is temporarily shut down due to a covered event (like a fire or major storm).

It can help pay for:

  • Lost revenue

  • Rent/mortgage payments

  • Employee wages

  • Temporary relocation costs

✅ Example: If a fire forces your restaurant to close for two weeks, this policy helps cover your lost income and rent during that period.


➕ Optional Add-Ons (Endorsements)

Many insurers allow you to customize your BOP with additional coverages, including:

  • Cyber Liability 🧑‍💻 – Protects against data breaches and cyberattacks

  • Professional Liability (Errors & Omissions) – Covers service-based mistakes

  • Equipment Breakdown – Covers repairs or replacements due to mechanical issues

  • Employee Dishonesty – Protects against theft or fraud by staff

  • Commercial Auto 🚗 – If your business uses vehicles

  • Hired/Non-Owned Auto – For employees using personal vehicles for business

📌 Tip: Work with an insurance agent or broker to tailor your BOP to your specific business needs.


🎯 Who Needs a BOP?

If you’re a small or medium-sized business owner, there’s a good chance a BOP is right for you—especially if you:

  • Have a physical location (even if it’s a home office)

  • Own business property or inventory

  • Interact with customers or clients in person

  • Want affordable, bundled protection

Industries that often benefit from BOPs include:

  • Retail stores

  • Restaurants & cafes

  • Freelancers & consultants

  • Wholesalers

  • Beauty salons

  • Contractors

  • Small manufacturers

  • Tech startups


💰 Benefits of a BOP

Let’s talk perks! 🎁

✅ Cost-Effective

Bundling coverage is typically cheaper than buying separate policies.

✅ Simplicity

One policy, one premium, one renewal date. Easy.

✅ Customizable

Add what you need, skip what you don’t.

✅ Peace of Mind

Focus on growing your business—not worrying about “what if” disasters.


🚧 What’s NOT Covered?

A BOP is great—but it doesn’t cover everything. You may still need:

  • Workers’ Compensation

  • Commercial Auto Insurance

  • Professional Liability (if not added)

  • Flood or Earthquake Insurance

  • Health or Life Insurance


📝 Final Thoughts

A Business Owner’s Policy is an excellent starting point for small business insurance. It wraps key protections into a single, streamlined package that’s both practical and affordable. It won’t cover every possible risk, but it offers a solid foundation for most small businesses.

Before choosing a BOP, ask yourself:

  • What are my biggest business risks?

  • Do I need additional coverage?

  • Am I getting the best value?

With the right BOP in place, you can spend less time worrying—and more time doing what you love: running your business. 🚀


📞 Need Help Choosing a BOP?

Work with a licensed insurance agent who understands small businesses. They can help you customize a plan that fits your needs, your budget, and your peace of mind.

You can experience the benefits of being a part of a full-serviced, Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-4840 or visit our website at www.BriggsAgency.com. We look forwards to hearing from you!

Blog post written by: Zachary Pelke
Benefits of Group Health Insurance Plans for Small Businesses

💼 The Benefits of Group Health Insurance Plans for Small Businesses

In today’s competitive job market, small businesses are constantly seeking ways to attract and retain top talent while managing costs. One powerful tool often overlooked is group health insurance. While offering health benefits may seem like a big step for a small company, the rewards far outweigh the costs.

In this blog, we’ll break down the key benefits of group health insurance plans for small businesses, how they work, and why offering health coverage might be one of the smartest investments you can make in your business.


✅ What Is Group Health Insurance?

Group health insurance is a single policy issued to a group—typically employees of a company—that provides medical coverage to its members. These plans often offer better rates, broader coverage, and tax benefits compared to individual health plans.


🔍 Group vs. Individual Health Insurance: Quick Comparison

Feature Group Health Insurance Individual Health Insurance
Premium Costs Shared between employer and employee Paid entirely by individual
Tax Benefits Employer receives tax deductions + credits Limited tax deductions
Coverage Options More robust; includes preventive & specialist care Varies; often more limited
Provider Network Often larger networks with better negotiated rates Can be narrower and costlier
Eligibility Must be employed by participating business Available to anyone
Administrative Help Often supported by brokers or PEOs Individual must manage everything

💡 Why Should Small Businesses Offer Group Health Insurance?

Let’s dive into the major benefits:

1. 🧲 Attract and Retain Talent

  • Competitive Advantage: Offering health insurance can set your business apart.

  • Employee Loyalty: 60% of employees say health benefits are a key factor in staying with their employer.

2. 💰 Tax Advantages

  • Business Deductions: Premiums are 100% tax-deductible for employers.

  • Small Business Tax Credit: Up to 50% of premiums covered for eligible companies via the SHOP marketplace.

3. 🧾 Lower Costs for Everyone

  • Premiums are typically 10–20% lower than individual plans.

  • Group risk-sharing helps keep premiums more stable year to year.

4. 🌐 Access to Better Coverage

  • Includes preventive care, emergency services, specialist visits, mental health, and more.

  • Employees may access HSAs or FSAs for tax-free medical savings.

5. 🛠️ Improved Productivity

  • Covered employees are more likely to seek timely care.

  • Reduces downtime from illness, leading to fewer sick days.

6. 👥 Builds a Positive Company Culture

  • Health benefits promote a culture of well-being and care.

  • Signals that leadership invests in people, not just profits.


📊 Real Stats: Why It Matters

📌 70% of small business employees said they are more likely to stay with a company that offers health benefits.
📌 Businesses that offer health insurance experience 25% less turnover on average.
📌 Employees with access to benefits report better engagement and productivity at work.
📌 According to the Kaiser Family Foundation, over 55% of small firms already offer health insurance—don’t get left behind!


📈 Quick-View: The ROI of Group Health Insurance

🧠 Productivity Boost
→ Fewer sick days
→ Faster return to work
→ Improved focus

📉 Cost Savings Over Time
→ Lower recruitment and training costs
→ Reduced absenteeism
→ Better insurance rate stability

🎯 Business Growth
→ Higher employee satisfaction
→ Better brand reputation
→ Stronger recruitment pipeline


🚀 How to Get Started

Starting a group health insurance plan is easier than you think. Here’s how:

  1. Assess Your Team’s Needs

    • Age range, dependents, desired benefits

  2. Set a Budget

    • Typical employer contribution: 50%–75% of premiums

  3. Compare Plans

    • Use brokers, PEOs, or the SHOP marketplace

  4. Enroll Employees

    • Collect necessary info and documents

  5. Communicate Clearly

    • Provide a benefits guide or FAQ to your team


📘 Example: Jane’s Coffee Co.

Jane runs a coffee shop with 9 employees. After losing a great barista to a larger company with benefits, she opted into a group health plan through a broker. By contributing 60% of premiums, she reduced turnover by 40% in a year and received a small business tax credit. Now, her shop has a waiting list of baristas wanting to work there.


🎨 Visual Summary (Perfect for Sharing!)

🧑‍🤝‍🧑 Group Health Insurance: Why It Works for Small Business
📌 Attracts Talent
📌 Boosts Retention
📌 Cuts Taxes
📌 Improves Productivity
📌 Builds Positive Culture
📌 Offers Better Coverage

“Healthy employees build healthy businesses.”


💬 Final Thoughts

Offering group health insurance is more than a benefit—it’s a strategic business decision. It helps you:

  • Compete with larger companies

  • Build a loyal, productive team

  • Reduce long-term costs

If you’re not offering coverage yet, it’s worth exploring. The financial advantages, employee satisfaction, and business reputation gains make it one of the most powerful tools in your small business toolkit.

You can experience the benfits of being a part of a full-service Independent Insurance Agency today! Simply contact Briggs Agency, Inc. if you are interested in an insurance review at 219-769-484- or visit our website at www.BriggsAgency.com. We look forward to hearing from you!

Blog post written by: Zachary Pelke