Crown Point Garage Insurance: Safeguard Your Shop and Vehicles

Running a garage in Crown Point means managing real risks every day-from customer vehicles on your lot to expensive tools and equipment inside your shop. Standard business insurance often leaves gaps that can cost you thousands if something goes wrong.

At Briggs Agency, Inc., we’ve helped local shop owners understand why Crown Point garage insurance tailored to their operations matters so much. This guide walks you through the coverage types you actually need and how to choose protection that fits your business.

Why Your Shop Faces Risks Standard Insurance Won’t Cover

Garage operations in Crown Point carry exposures that generic business policies simply don’t address. A customer’s vehicle parked in your lot overnight gets stolen, or damage occurs during a routine oil change-your standard commercial policy likely excludes both scenarios entirely. The National Association of Insurance Commissioners reported that collision claim costs rose 17.6% from 2021 to 2022, jumping from $6,113 to $7,191 per claim, meaning a single incident can wipe out months of profit. Beyond vehicles, your shop inventory faces real threats too: tools worth thousands can disappear, equipment gets damaged during repairs, and liability exposure multiplies when customers step onto your property or drive away with incomplete work.
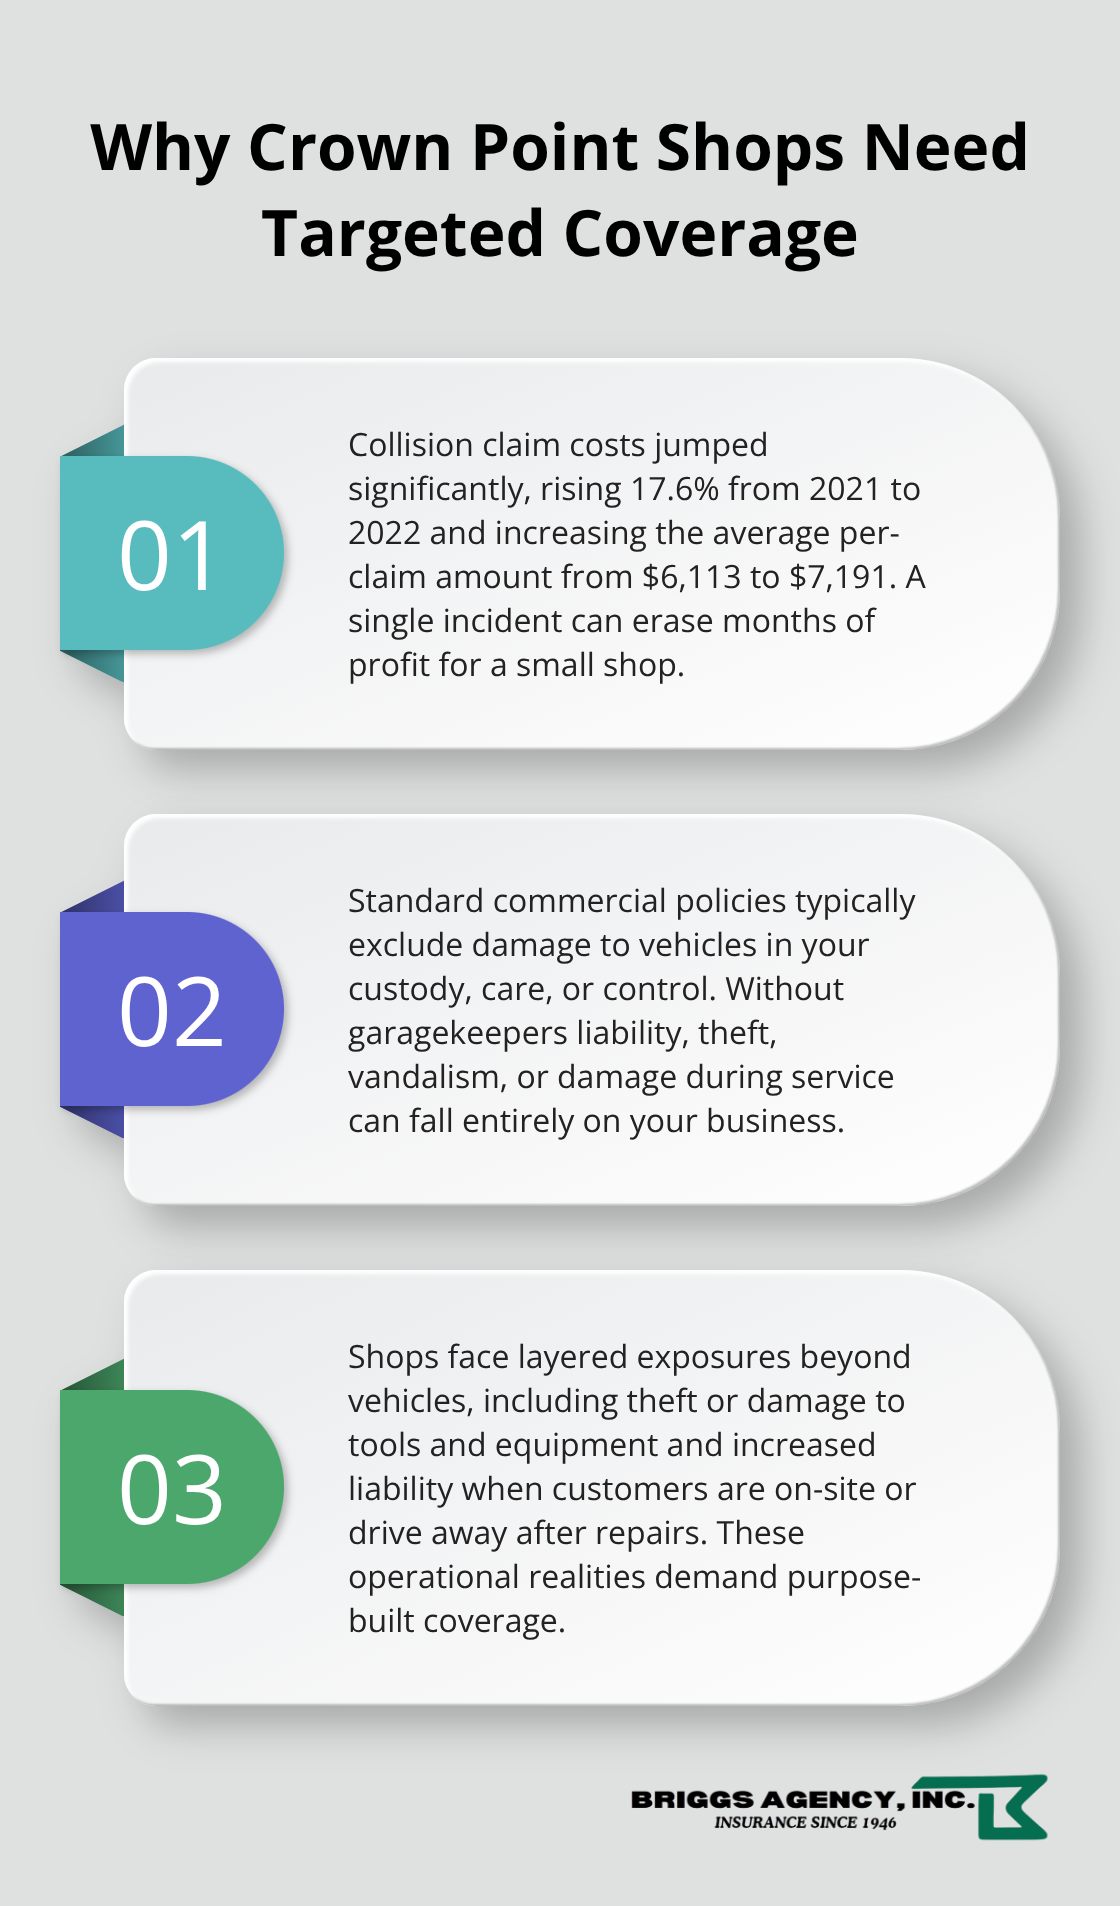
Three concise reasons garage shops in Crown Point face elevated risks and need tailored insurance. - Crown Point garage insurance

The gap between what you think you’re covered for and what you actually are

Most business owners assume their general liability policy protects them when a customer’s vehicle is damaged in their care. It doesn’t. Standard policies exclude vehicles in your custody because they’re considered property you control, not third-party damage. If a customer vehicle catches fire while parked at your shop, or gets hit by another vehicle in your lot, your general liability won’t pay a dime. Garagekeepers liability exists specifically to fill this gap-it covers damage to customer vehicles whether caused by theft, vandalism, collision, or shop error. Mechanics errors and omissions coverage protects against claims that arise from faulty repairs and cause injury or property damage after the vehicle leaves your shop. Without it, a botched brake job that causes an accident weeks later becomes your financial responsibility.

What makes Crown Point shops vulnerable

Your location and customer base shape your specific risks. Shops that handle high-value vehicles face elevated theft and vandalism exposure compared to basic maintenance operations. Shops that perform complex work like engine rebuilds or transmission service carry higher error liability than tire rotations. Seasonal patterns matter too-winter brings increased collision risk and weather-related damage, while summer storage of customer vehicles creates longer-term custody exposure. The commercial auto insurance market hardened significantly in 2026, with underwriters now prioritizing data-backed predictability over broad caution. This means carriers reward shops with solid safety records and stable operations, but penalize those with inconsistent practices or limited documentation. Understanding your exact exposures (vehicle types you handle, service complexity, storage duration, and employee turnover) lets you avoid overpaying for unnecessary coverage while preventing dangerous gaps.

How coverage options connect to your actual shop needs

The right garage insurance policy matches your specific operations, not a one-size-fits-all template. A shop that stores customer vehicles overnight needs different limits than one that completes same-day service. A facility that performs high-risk work like transmission rebuilds requires stronger mechanics errors and omissions protection than a basic tire shop. Your choice between direct primary and direct excess garagekeepers coverage affects both cost and how quickly claims get resolved-direct primary pays regardless of fault but costs more, while direct excess typically costs less but requires proof of fault. The coverage limits you select should reflect your average vehicle value, the number of vehicles on your lot at any time, and the complexity of work your team performs. Shops with high employee turnover or seasonal volume spikes face tighter underwriting scrutiny in today’s market, which means transparent documentation of your operations becomes essential to securing competitive rates.

Coverage Your Shop Actually Needs

Garagekeepers Liability: Your First Line of Defense

Garagekeepers liability stands apart as the single most important coverage gap to close. This policy covers damage to or theft of customer vehicles while they sit in your lot, park in your bay, or undergo service-situations your general liability flatly refuses to touch. The National Association of Insurance Commissioners reported that collision claim costs jumped 17.6% between 2021 and 2022, reaching $7,191 per claim on average. A single stolen vehicle or major damage incident during service can exceed annual profits for most Crown Point shops.

When you select garagekeepers coverage, you face a meaningful choice between direct primary and direct excess options. Direct primary pays claims regardless of fault, which accelerates resolution and strengthens customer trust, but carries higher premiums. Direct excess costs less upfront but requires you to prove fault before payment kicks in, which means customer disputes and slower claim processing. For shops handling high-value vehicles or those with tight cash flow, the faster claims resolution of direct primary often justifies the premium difference.

Your coverage limit should reflect the actual vehicle values you handle-a shop servicing luxury imports needs substantially higher limits than one focused on economy vehicles. Most Crown Point shops store between three and eight customer vehicles at any given time, so calculate your maximum exposure by multiplying your typical vehicle count by the average value of vehicles you service, then add 25% as a buffer.

General Liability and Property Protection

General liability and property protection form your second layer of defense. General liability covers injuries customers sustain on your property and damage to their belongings (tools they bring in, phones, glasses) that aren’t part of the vehicle itself.
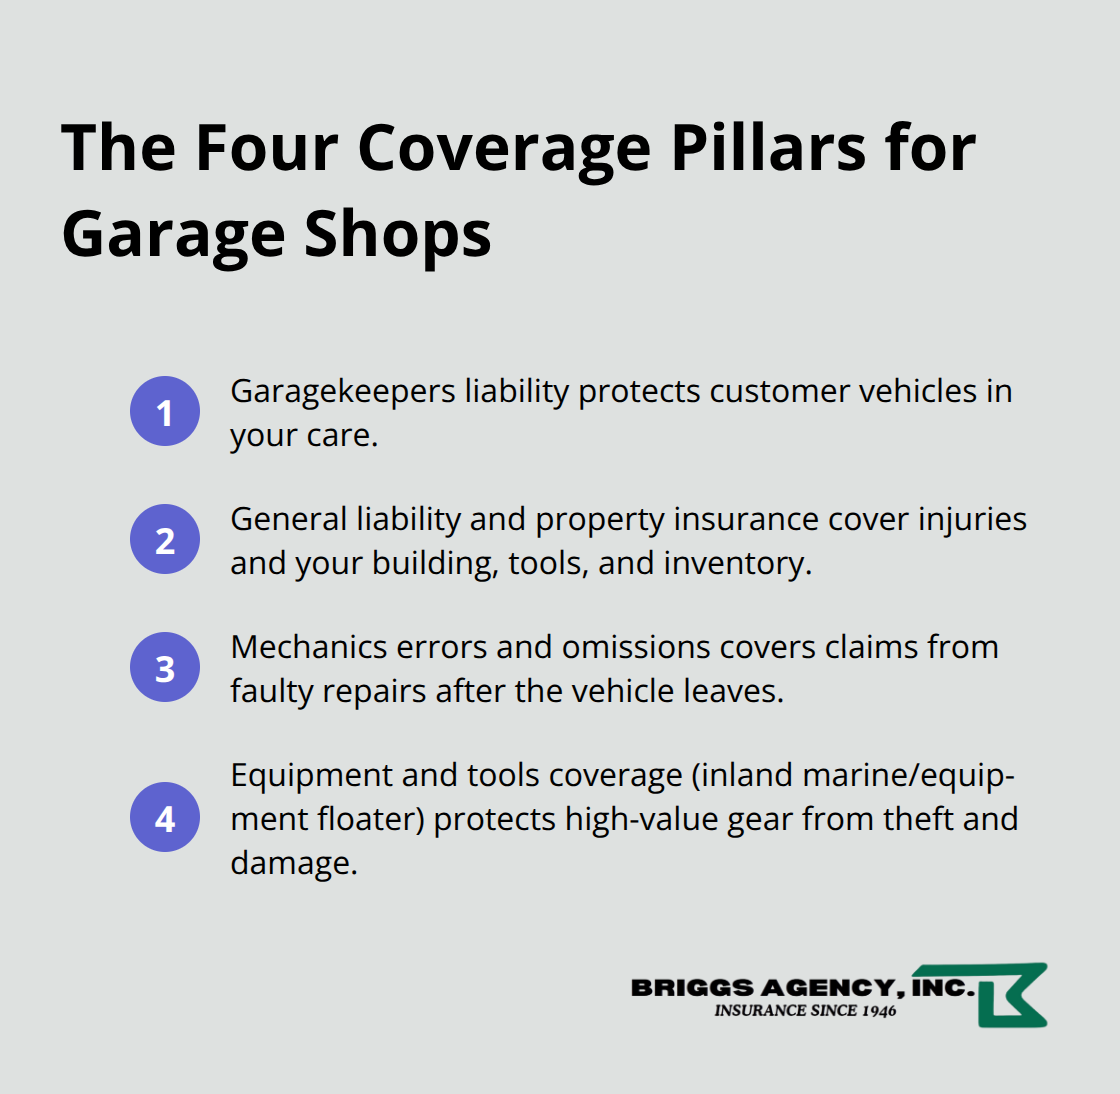
Compact list summarizing the four essential coverage pillars for garage operations. - Crown Point garage insurance

Property insurance protects your building, equipment, tools, and inventory from fire, theft, weather, and other perils.

The commercial auto market in 2026 has tightened considerably, with underwriters now demanding documented safety practices and stable operations to offer competitive rates. Shops with high employee turnover, inconsistent maintenance records, or unclear service procedures face steeper premiums or coverage denials. This reality means your insurance strategy should include documenting your actual practices-service logs, employee training records, safety protocols, and vehicle inspection checklists all strengthen your underwriting profile and often reduce your rates.

Mechanics Errors and Omissions Coverage

Mechanics errors and omissions coverage deserves serious attention if your team performs complex work. This coverage handles claims that arise from faulty repairs-a brake job that fails weeks after the customer leaves, an electrical repair that causes an engine fire, or transmission work that results in safety hazards. These claims often surface months or years after service completion, meaning you face liability long after the work leaves your shop.

Tools, Equipment, and Inventory Protection

Tools and equipment deserve protection through inland marine or equipment floater coverage, which shields your specialized diagnostic equipment, lifts, compressors, and hand tools from theft and damage. A shop’s tool inventory easily reaches $50,000 to $150,000 depending on specialization, making this coverage economically essential rather than optional. Your specific equipment needs and the values you carry determine whether standard property coverage suffices or whether you need specialized equipment protection.

Understanding these four coverage pillars-garagekeepers liability, general liability and property protection, mechanics errors and omissions, and equipment coverage-positions you to make informed decisions about your shop’s protection. The next step involves assessing which of these coverages applies most directly to your operations and determining the appropriate limits for each.

How to Choose the Right Garage Insurance for Your Crown Point Business

Assess Your Actual Exposures

Start by mapping what sits in your shop and lot on any given day. Count the vehicles you typically store, note their average value, and identify which ones represent your highest-value exposures. A shop handling five luxury imports needs vastly different garagekeepers limits than one servicing ten economy vehicles. Next, categorize your service mix: shops performing complex work like engine rebuilds or transmission service face substantially higher mechanics errors and omissions exposure than those doing routine maintenance. Document your employee situation honestly-shops with high turnover or seasonal staffing patterns will face tighter underwriting scrutiny in today’s market, so expect carriers to ask for detailed safety records and training documentation. The 2026 commercial auto market rewards predictability with better rates, which means shops with stable crews, consistent service procedures, and documented safety practices pay less than those with chaotic operations.

Calculate your maximum financial exposure by identifying the worst-case scenario: a high-value customer vehicle stolen from your lot, combined with an employee injury claim, plus damage to your building and equipment. That total tells you the minimum coverage limits you actually need. Many Crown Point shop owners underestimate their tool and equipment value-a typical shop easily carries $75,000 to $125,000 in specialized diagnostic equipment, lifts, and hand tools, so verify this number before selecting your inland marine coverage limits.

Compare Quotes Across Multiple Carriers

Comparing actual quotes from multiple carriers matters far more than shopping based on reputation alone. Request quotes that isolate each coverage type so you understand what you’re paying for garagekeepers versus general liability versus mechanics errors and omissions. Direct primary garagekeepers coverage allows you to continue servicing your customers’ cars with confidence, knowing that you and your business are protected. Don’t let an agent push you toward the cheapest option without understanding what you’re sacrificing-the lowest premium often means higher deductibles, lower limits on critical coverages, or exclusions that leave dangerous gaps. Request quotes that reflect your documented operations: share your service logs, employee training records, safety protocols, and vehicle inspection procedures with carriers, as this documentation directly influences pricing and can lower your rates considerably.
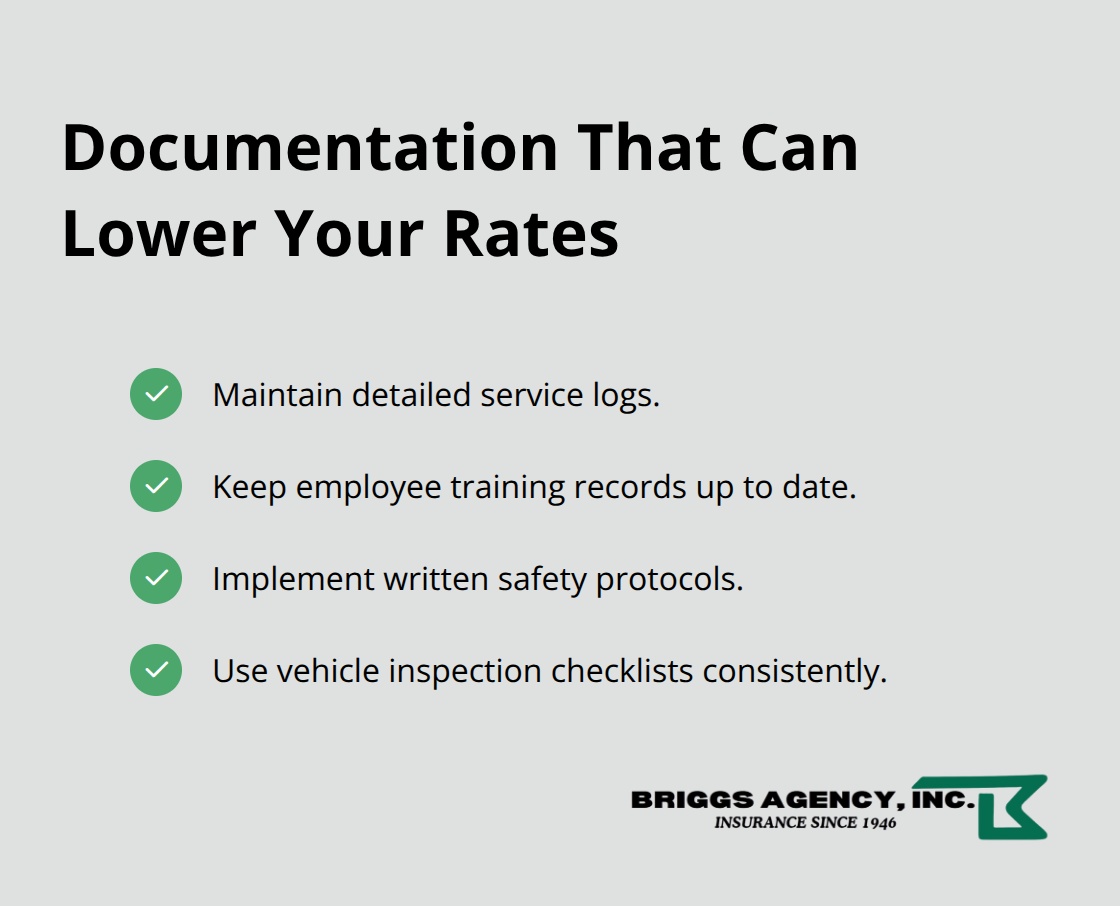
Checklist of shop documentation that strengthens underwriting and can reduce premiums.

Evaluate Carrier Practices and Claims Support

Ask each carrier explicitly about their stance on seasonal operations, employee turnover thresholds, and data-sharing requirements-some carriers reward shops willing to share telematics or equipment monitoring data with better pricing, while others ignore this information entirely. The final comparison should answer three specific questions: Which quote gives you the coverage limits matching your actual exposures? Which carrier offers the claims support your shop needs when incidents happen? Which option fits your annual budget without forcing you to skip essential protections like mechanics errors and omissions coverage?

Final Thoughts

Protecting your Crown Point garage means closing the gaps that standard business policies leave wide open. A stolen customer vehicle, a faulty repair claim that surfaces months later, or damage to your equipment inventory can derail your business if you lack the right coverage. Crown Point garage insurance tailored to your specific operations isn’t an expense-it’s the foundation that lets you serve customers confidently and build long-term success.

Your next step is straightforward: gather your shop’s details and request quotes that reflect your actual exposures. Document your vehicle count, service types, employee stability, and equipment values, then share this information with carriers so they understand your specific risk profile. The 2026 commercial auto market rewards shops with documented safety practices and predictable operations, which means your transparency directly influences the rates you’ll receive.

We at Briggs Agency, Inc. represent multiple top-rated carriers and compare options across the market to tailor policies that deliver competitive pricing alongside genuine protection. Our experienced local agents understand the specific risks garage operations face in our community, and we provide hands-on claims support when incidents occur. Contact us today to discuss your shop’s coverage needs and receive quotes that reflect your actual business.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Garage Repair Insurance: Keep Your Auto Shop Running

Running an auto shop means managing countless risks every single day. From customer injuries on your lot to expensive equipment damage, one accident can threaten your entire operation.

At Briggs Agency, Inc., we’ve helped shop owners across our community protect their businesses with garage repair insurance. This guide walks you through the coverage options that matter most and how to build a policy that actually fits your shop’s needs.

What Your Garage Repair Insurance Actually Covers

The Core Protections Your Shop Needs

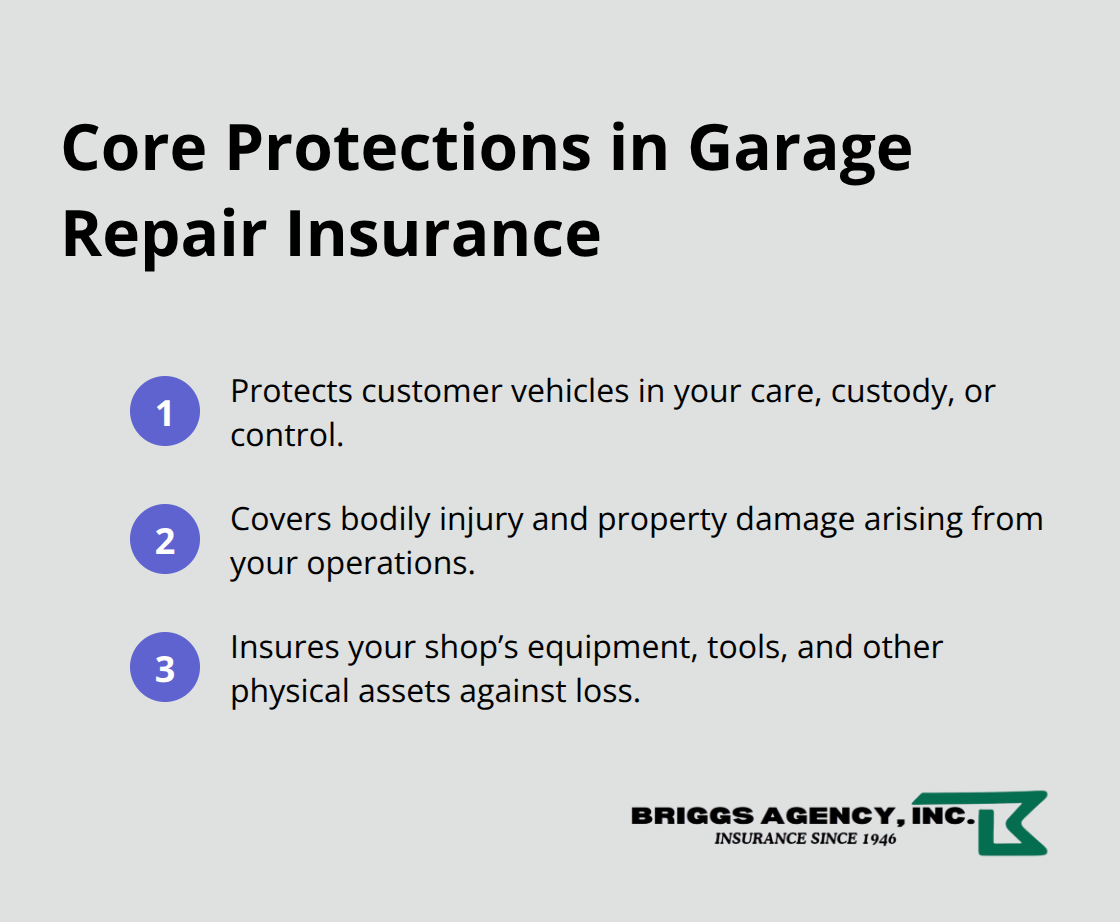
Garage repair insurance isn’t a single product-it’s a collection of coverages that work together to protect against the specific risks that come with running an auto shop. The core of this protection centers on three areas: damage to customer vehicles in your care, liability claims from injuries or property damage, and loss of your own equipment and tools. Commercial General Liability covers bodily injury and property damage claims that arise from your shop’s operations, including a customer who trips on your lot or damage caused by your work.

Three core protections every U.S. auto shop needs in a garage repair policy - Garage repair insurance

Garagekeepers liability covers customer vehicles stored on your premises from theft, fire, vandalism, or weather damage, as well as bodily injury, property damage, or accusations of slander or copyright infringement-but not from bad workmanship or warranty issues. If a windstorm damages three vehicles parked in your lot, garagekeepers coverage steps in to cover those losses.

Protecting Your Assets and Employees

Commercial Property Insurance protects the physical assets you own or lease: your building, diagnostic equipment, lifts, inventory, and furniture. Equipment Floater coverage extends that protection to tools and equipment as they move around your shop or travel to job sites, covering losses from theft, collision, or damage. Workers’ Compensation is legally required in most states and covers employee injuries or illnesses that occur on the job.

The Coverage Gaps Most Shops Miss

What many shop owners overlook are the gaps between these coverages. Garagekeepers liability explicitly excludes damage caused by faulty repair work or warranty issues-that’s where Professional Liability coverage comes in, protecting against claims when staff mistakes lead to customer vehicle damage or crash-related costs. Business Auto Insurance covers vehicles your shop owns or leases, while Hired and Non-Owned Auto coverage protects you when employees use their personal vehicles for business purposes. If you perform road testing on customer vehicles, this gap-filler is essential because standard personal auto policies exclude business use.

Hidden Exposures That Can Sink Your Business

Another commonly missed exposure is Business Interruption coverage, which replaces lost income if a fire or disaster forces your shop to close temporarily. A Midwest shop that experienced a major fire without this coverage lost approximately $50,000 in monthly revenue during the three-month rebuild period. Pollution Liability, often overlooked entirely, covers environmental cleanup costs when hazardous materials from your shop contaminate soil or groundwater-cleanup can range from $50,000 to $500,000, making this a serious financial exposure. Cyber Liability protects against data breaches and ransomware attacks; the Identity Theft Resource Center reports rising threats to small businesses, with typical small-shop coverage costing $800 to $2,500 annually for $1 million in protection.

Why Standard Business Policies Fall Short

The most critical mistake shop owners make is assuming standard business policies cover these exposures. They don’t. A standard commercial policy leaves you exposed the moment you take possession of a customer’s vehicle. Understanding which coverages address which risks sets the foundation for building a policy that actually protects your operation-and that’s where assessing your shop’s specific risks becomes the next essential step.

Why Your Shop Faces Real Financial Risk Without Proper Coverage

Liability Claims That Drain Your Operating Account

Auto shops face liability claims that can devastate finances faster than most owners realize. A customer slips on oil in your service bay and breaks their arm-that’s a premises liability claim your general business policy might not fully cover. A technician road-tests a customer’s vehicle and causes an accident-your standard commercial auto policy won’t cover it because the vehicle wasn’t yours. These scenarios happen regularly across the industry, and shops without proper garage repair insurance pay settlements directly from operating accounts.

Commercial General Liability covers bodily injury and property damage from your operations, but it has limits. If a customer sues for $500,000 after a serious injury and your policy maxes out at $1 million per occurrence, you absorb the difference. Garage liability is designed to cover claims of negligence associated with the daily operations of auto repair businesses-coverage that standard policies explicitly exclude. A single windstorm that damages five vehicles in your lot could cost $100,000 to $200,000 out of pocket without this protection.

The Repair Mistake That Becomes a Lawsuit

Professional Liability coverage addresses the gap most shop owners miss entirely: claims that arise from faulty repair work and cause customer vehicle damage or crash-related injuries. If a technician’s mistake during brake service leads to a customer accident, this coverage protects you against the resulting lawsuit and repair costs. Standard policies leave you exposed to these claims because they don’t recognize the specific liability that comes with performing repairs.

Equipment Loss Stops Your Operation Cold

Your equipment and tools represent significant capital investment, and losing them stops your entire operation immediately. Inland Marine coverage protects diagnostic equipment, lifts, and specialty tools from theft, fire, or damage as they move around your shop. A $50,000 diagnostic machine stolen from your lot becomes a business-ending loss without this protection. You can’t perform repairs without your core equipment, which means you can’t generate revenue.

The Three Exposures That Threaten Business Survival

Business Interruption coverage is where most shops make their biggest mistake. If a fire forces you to close for three months, this coverage replaces your lost revenue while you rebuild. A Midwest shop that lost its facility without this coverage lost approximately $50,000 monthly for three months-$150,000 in total income that evaporated. The shop had to take on emergency debt to survive.

Workers’ Compensation is legally required in most states and covers employee injuries on the job, but it also protects you from lawsuits when employees get hurt. Pollution Liability, often completely overlooked, covers environmental cleanup costs when hazardous materials from your shop contaminate soil or groundwater. Cleanup costs range from $50,000 to $500,000 depending on contamination severity, making this exposure serious enough to threaten business survival.

Cyber Threats to Your Customer Data

Cyber Liability has become essential as shops store customer data and payment information. The Identity Theft Resource Center reports rising cyber threats to small businesses, with typical coverage costing $800 to $2,500 annually for $1 million in protection. One ransomware attack that locks your shop’s computer systems can force closure for weeks and expose customer information to theft.

These gaps between standard policies and actual shop exposures create financial vulnerabilities that compound quickly. The next step involves assessing which of these risks apply most directly to your operation and determining the coverage limits that match your specific situation.

Building Your Coverage Around What Actually Matters

Assess Your Shop’s Actual Exposures

Start with a complete list of every service your shop performs and every vehicle type you handle. A shop that only does oil changes and tire rotations faces completely different exposures than one doing transmission rebuilds, body work, and road testing. Count the maximum number of vehicles on your premises at any given time, including customer drop-offs and vehicles waiting for service. This number directly determines your garagekeepers limit. If you typically have 20 vehicles on site and the average customer vehicle is worth $28,000, you need at least a $600,000 garagekeepers limit with some cushion built in. Many shops set limits based on what sounds reasonable rather than actual exposure-a critical mistake that costs money when claims arrive.

Calculate Garagekeepers Limits Based on Real Numbers

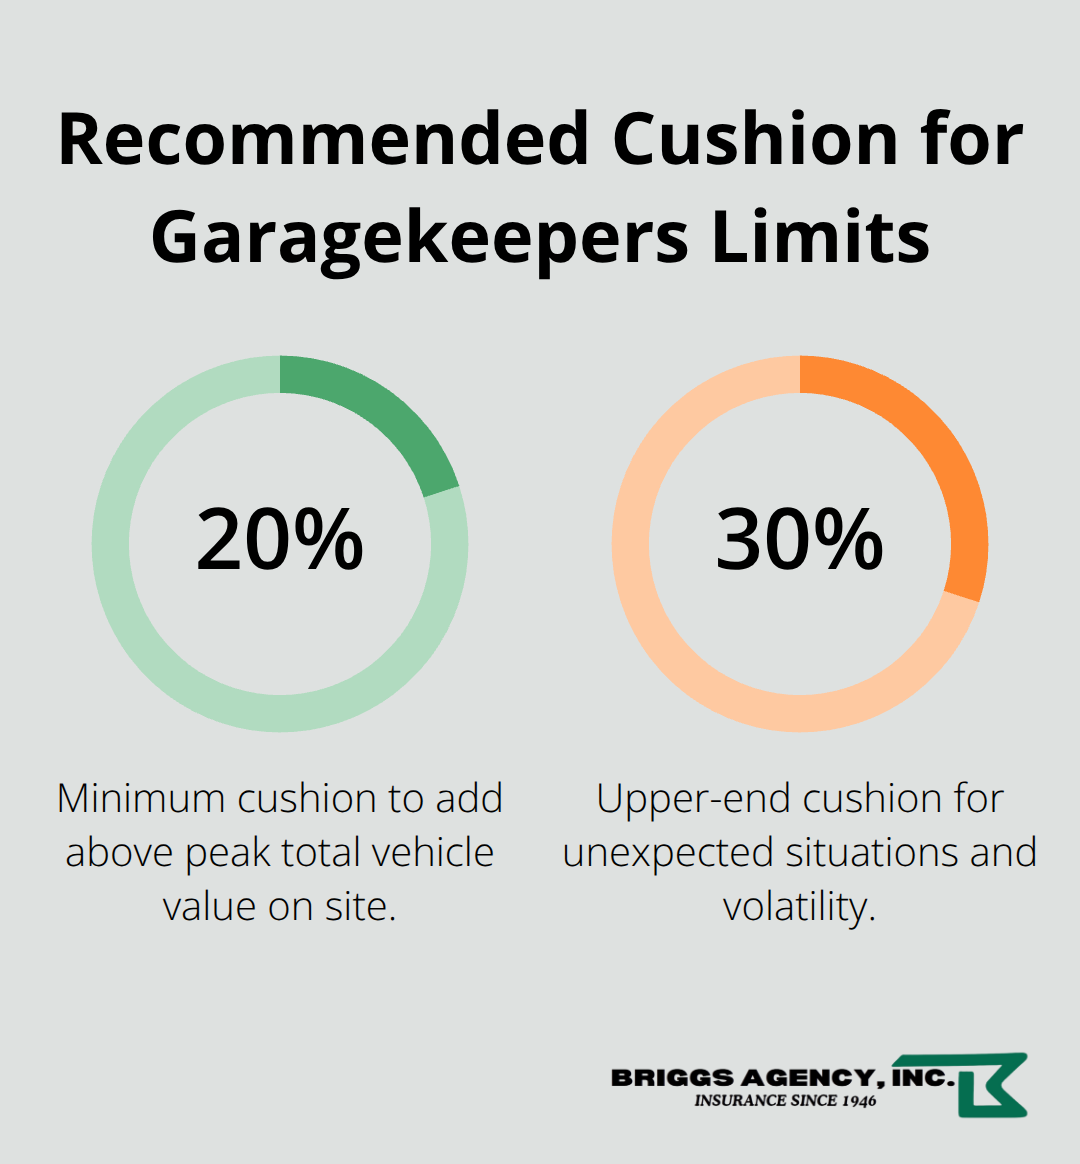
A real Midwest shop with a $250,000 garagekeepers limit faced over $300,000 in settlements after a single windstorm damaged five vehicles. The shop paid the difference from operating funds, a painful lesson in underestimating exposure. Your garagekeepers limit should reflect the total value of vehicles you hold at peak capacity, plus a 20 to 30 percent cushion for unexpected situations. This approach protects you from absorbing losses that exceed your policy limits.

Suggested percentage cushion to add to peak vehicle value for U.S. auto shops - Garage repair insurance

Identify Road Testing and Employee Vehicle Risks

Evaluate whether technicians drive customer vehicles for diagnostics or test drives. Standard commercial auto policies specifically exclude this activity, leaving you exposed to liability claims. Hired and Non-Owned Auto coverage fills this gap at roughly $300 to $800 annually and protects you when employees use personal vehicles for business purposes. This coverage becomes essential if your operation includes road testing or diagnostic driving.

Address Environmental and Data Vulnerabilities

Assess your facility for environmental risk. If you change oil, handle coolant, or work with petroleum products, Pollution Liability becomes essential. Cleanup costs range from $50,000 to $500,000 depending on soil contamination, making this a serious financial exposure most shops completely ignore. Document your annual revenue to determine Business Interruption coverage limits-the standard recommendation is 12 to 18 months of operating expenses, which protects you if a fire or disaster forces temporary closure. A three-month shutdown without this coverage can drain $150,000 or more from a typical shop’s cash reserves.

Protect Customer Information and Digital Assets

Evaluate your data handling practices. If you store customer information digitally, Cyber Liability coverage at $1 million typically costs $800 to $2,500 annually and covers breach notification, credit monitoring, and regulatory fines that small businesses increasingly face. These aren’t theoretical risks; they’re exposures that happen to real shops regularly, and proper coverage protects both your operation and your customers’ trust.

Final Thoughts

Garage repair insurance protects your shop against the specific risks that standard business policies ignore. The coverage gaps throughout this guide represent real financial exposures that can force closure or drain your operating account in a single incident. A windstorm, equipment theft, employee injury, or customer lawsuit becomes manageable with proper protection in place and devastating without it.

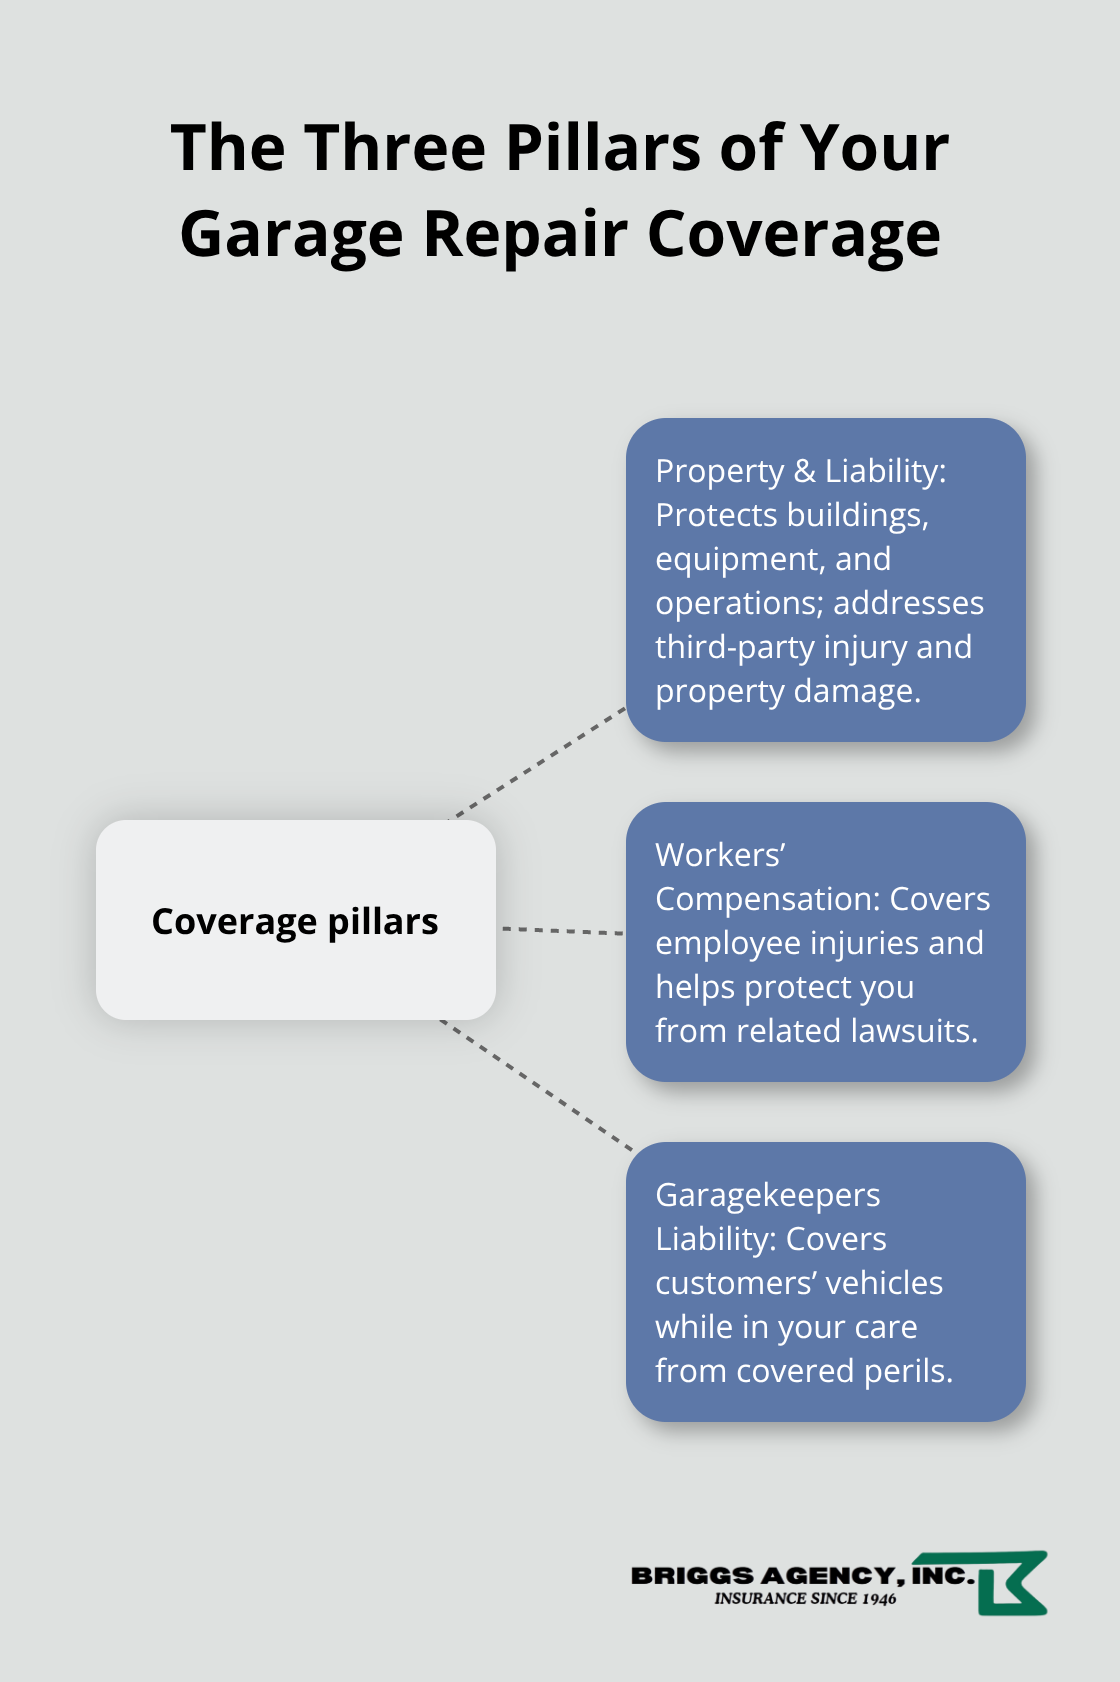
Your coverage should rest on three pillars: protecting your physical assets and operations through property and liability coverage, protecting your employees through workers’ compensation, and protecting your customers’ vehicles through garagekeepers liability. Beyond these essentials, your policy needs to address the exposures specific to your operation, whether that’s road testing, environmental risk, or cyber threats. The limits you choose should reflect your actual exposure, not industry averages or what sounds reasonable.

Hub-and-spoke showing the three pillars of coverage for U.S. auto repair shops

We at Briggs Agency, Inc. have helped shop owners across our community build policies that actually fit their operations. Contact us at https://briggsagency.com to discuss your coverage gaps and get a quote tailored to your specific risks. Your shop’s financial protection depends on taking action today.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Restaurant Workers Compensation: Keeping Your Team Covered

Running a restaurant means managing countless moving parts, and your team’s safety should always be at the top of that list. Restaurant workers compensation isn’t just a legal requirement-it’s your safety net when injuries happen.

At Briggs Agency, Inc., we’ve seen firsthand how the right coverage protects both your employees and your business. This guide walks you through what you need to know to keep your team properly covered.

What Workers Compensation Actually Covers in Your Restaurant

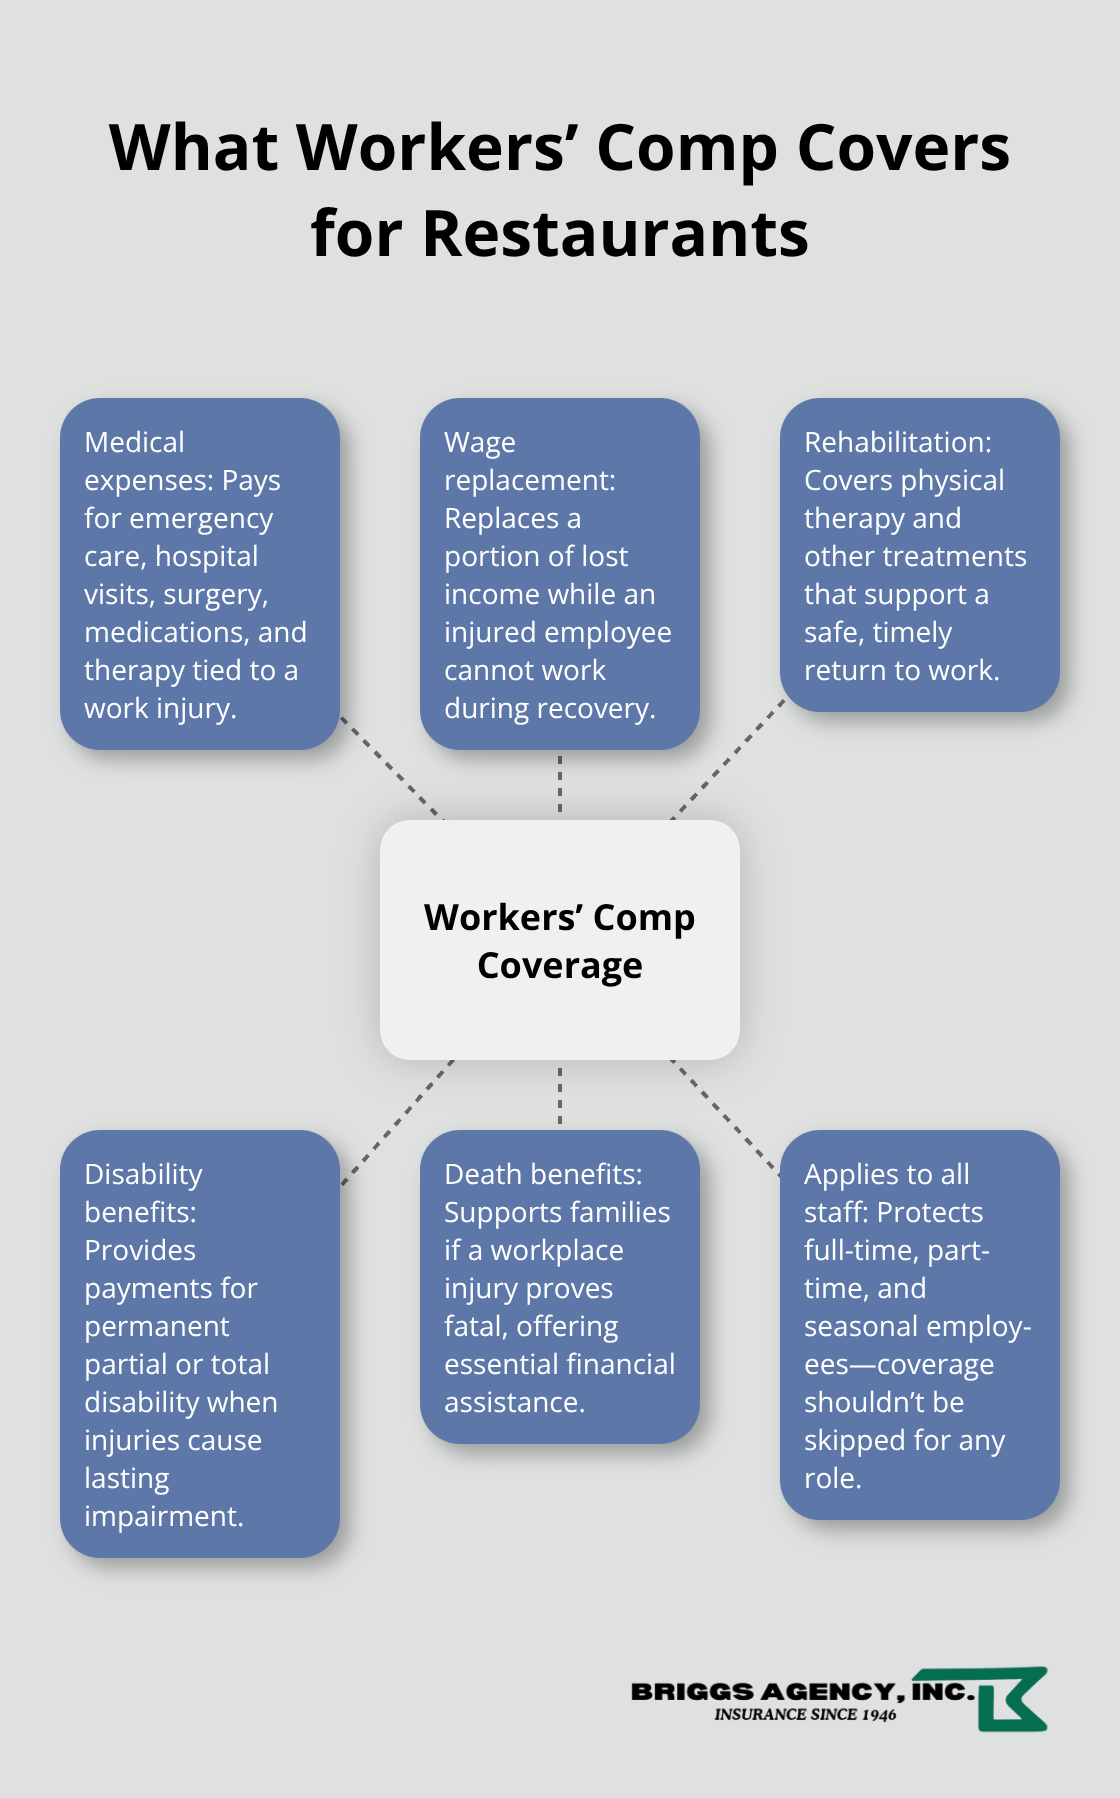
Workers compensation in food service covers medical expenses, lost wages, and rehabilitation for job-related injuries and illnesses. If a cook suffers a burn from fryer oil, workers comp pays for emergency care, follow-up treatment, and medications. If a server injures their back lifting a heavy tray and can’t work for six weeks, the policy covers a portion of their lost wages during recovery. The coverage also extends to disability benefits if an injury causes permanent partial or total disability, and death benefits for families if a workplace injury proves fatal.

Visual overview of core workers’ compensation coverages for restaurant employees - Restaurant workers compensation

This protection applies regardless of whether your employee works full-time, part-time, or seasonally-a misconception that costs many restaurant owners money when they skip coverage for staff they assume don’t need it.

The Real Cost of Kitchen Injuries

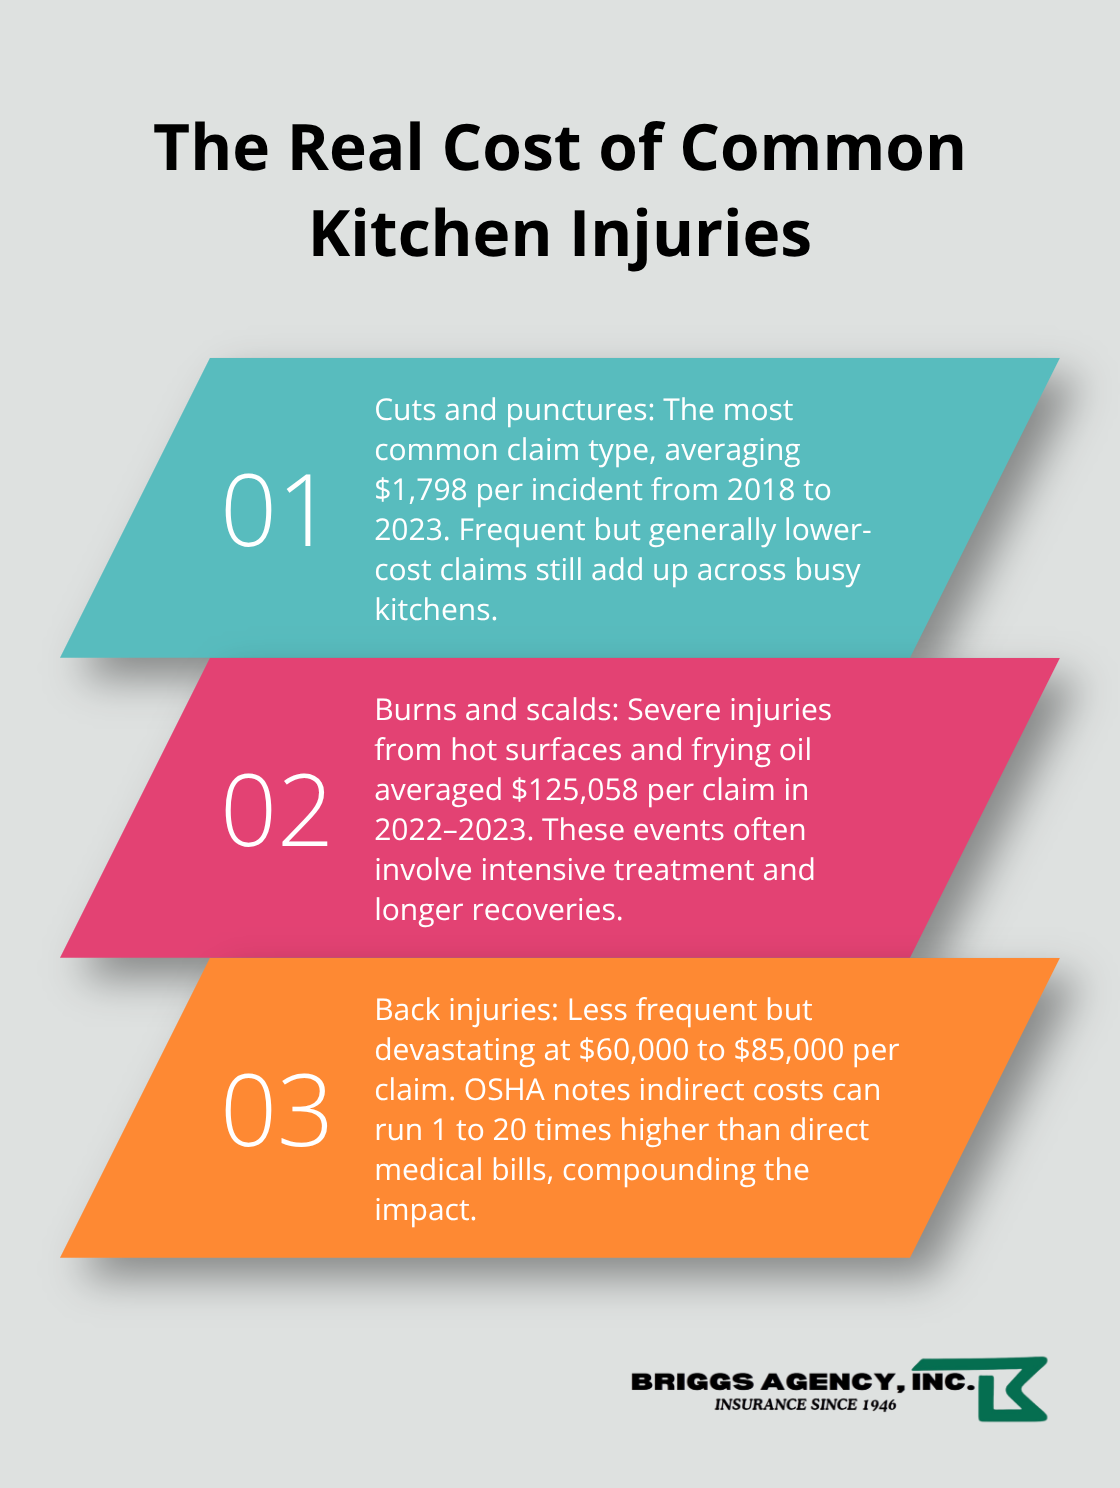
Restaurant injuries carry steep price tags, and the numbers reveal why this coverage matters. According to AmTrust’s analysis of roughly 130,000 workers compensation claims from 2018 to 2023, cuts and punctures from kitchen tools or broken glass represent the most common claim type, averaging $1,798 per incident. Burns and scalds from hot surfaces and frying oil averaged $125,058 per workers’ compensation claim in 2022 and 2023. Muscle strains and sprains from wet floors or heavy lifting run $9,966 to $10,672 per claim. Back injuries are rare but devastating-they typically cost $60,000 to $85,000 per claim due to heavy lifting and repetitive motions. Beyond direct medical costs, OSHA estimates indirect costs from workplace injuries run one to twenty times higher than direct costs, including lost productivity, temporary staff coverage, training replacements, and potential reputational damage when injuries become public.

Three key cost drivers for restaurant injury claims with average claim amounts - Restaurant workers compensation

Why This Protection Protects Your Business Too

Workers compensation isn’t just about employee welfare-it protects your restaurant from financial collapse. Without proper coverage, a serious injury exposes you to lawsuits, legal defense costs, and settlements that can devastate a small operation. The policy includes employer’s liability coverage, which defends against claims that you were negligent and covers attorney fees, court costs, and settlements. Most states require coverage if you have employees, and the penalties for operating without it include fines, license suspension, and personal liability.

Moving Forward With the Right Coverage

Understanding what workers compensation covers is only half the battle. The next step involves identifying which specific coverage types matter most for your restaurant’s unique operation and risk profile.

What Each Coverage Type Means for Your Restaurant

Medical Expense Coverage: The Foundation of Protection

General liability insurance forms the backbone of workers compensation, paying for all medical care tied to a work injury-from the ambulance ride to months of physical therapy. When a line cook suffers a severe burn from a fryer, medical coverage picks up emergency room costs, surgical procedures, ongoing wound care, and medications needed during healing. This applies whether the injury requires a single urgent care visit or extended hospitalization and rehabilitation. The coverage removes the burden of your employee choosing between medical care and financial hardship, which matters because untreated injuries often lead to complications, longer recovery times, and higher indirect costs for your business.

Wage Replacement Benefits: Keeping Your Team Stable

Wage replacement benefits function differently than medical coverage-they replace a portion of lost income while an injured employee recovers and cannot work. If a server with a shoulder injury takes eight weeks off, the policy typically covers 66 2/3 percent of their average weekly wage during that period, depending on your state’s rules. This partial wage replacement keeps your injured team member financially stable and reduces the likelihood they’ll return to work too soon and worsen their injury. The AmTrust analysis of 130,000 workers compensation claims from 2018 to 2023 shows that muscle strains and sprains average $9,966 to $10,672 per claim, and many of those injuries require weeks away from work-wage replacement ensures your employee isn’t forced into debt while healing.

Disability and Vocational Rehabilitation: Supporting Long-Term Recovery

Disability and vocational rehabilitation services address longer-term consequences when an injury causes permanent damage. If a back injury from repetitive lifting leaves an employee unable to return to their kitchen role, vocational rehabilitation helps them retrain for a different position within or outside your restaurant. Some policies also cover permanent partial disability payments if an injury results in lasting functional loss, such as reduced grip strength or chronic pain that prevents full duty work. These services matter because back injuries-the most expensive restaurant workers compensation claims at $60,000 to $85,000 per incident according to AmTrust data-often create situations where employees cannot safely perform their original duties. Without rehabilitation support, you lose experienced staff and face hiring and training costs for replacements.

Choosing the Right Coverage Limits for Your Operation

Different restaurants face different physical demands, and your coverage should reflect that reality. A high-volume kitchen with heavy lifting demands requires different protection than a fast-casual establishment with lighter physical work. The right coverage limits depend on your staff size, the types of roles you employ (line cooks carry higher risk than hosts), and your restaurant’s specific hazards. Understanding these distinctions helps you avoid both underinsurance and unnecessary overpayment, positioning your operation for financial stability when injuries occur.

How to Stop Restaurant Injuries Before They Happen

The most effective way to reduce workers compensation claims is to prevent injuries in the first place. Restaurant injuries follow predictable patterns, and AmTrust’s analysis of 130,000 claims from 2018 to 2023 shows exactly where your prevention efforts should focus. Cuts and punctures top the list as the most common claim type, followed by burns from hot surfaces and frying oil, then muscle strains from wet floors and heavy lifting. Back injuries, while less frequent, cost $60,000 to $85,000 per claim, making them the most expensive to treat. This data tells you something critical: prevention in kitchens isn’t about vague safety culture-it’s about addressing specific hazards with targeted action.

Eliminate Wet Floors and Slip Hazards

Wet floor hazards cause both cuts when employees slip into sharp objects and strains when they overextend to catch themselves. Require slip-resistant footwear for all kitchen and prep staff, not as a suggestion but as a non-negotiable uniform requirement. Clean spills immediately, not within five minutes or when someone notices-immediately. Assign a staff member during each shift to walk the kitchen every thirty minutes specifically to look for water, grease, or debris. Mark hot surfaces and high-risk equipment with clear warning labels and reflective tape so new hires and tired closing-shift staff instantly recognize danger zones. These aren’t expensive changes-they’re operational fixes that cost almost nothing but save tens of thousands in claim costs.

Organize Sharp Tools and Prevent Cuts

For cuts, implement a knife storage system where blades point downward in a designated rack rather than scattered in soapy dishwater. Train employees to pass knives handle-first and never hand them across the counter. Organize your prep station so sharp tools have designated homes and staff don’t dig through drawers searching for equipment. This simple reorganization removes one of the most common injury sources in your kitchen.

Structure Onboarding and Safety Training

High staff turnover in restaurants makes it tempting to skip formal training, but that turnover is exactly why structured onboarding and safety training saves money. New employees should receive hands-on instruction during their first shift on proper lifting technique-feet shoulder-width apart, bend at the knees not the back, keep loads close to the body. Show them how to operate equipment they’ll use daily and require them to demonstrate competency before working unsupervised. Create a simple written checklist of kitchen hazards and have each new hire sign it after walking through the space with a manager. Document these training sessions because safety documentation reduces premiums over time and protects you legally if an injury occurs and questions arise about whether proper instruction happened.

Maintain Consistent Safety Communication

Many insurance carriers offer free or low-cost safety resources including handbooks, posters, and on-site assessments-use them. Hold brief five-minute safety huddles before busy shifts where you highlight one specific hazard or near-miss from the previous week. If someone nearly slipped on a grease spot, talk about it. If a knife dropped near someone’s foot, discuss how to handle sharp tools safely. These quick touchpoints cost nothing and keep safety front-of-mind when staff might otherwise operate on autopilot during chaotic service.

Checklist of practical steps restaurants can take to prevent common workplace injuries

Inspect equipment regularly-fryers, grills, and slicers should have a monthly maintenance check where you verify safety guards are in place and functioning. Equipment failures cause injuries, and preventive maintenance stops failures before they happen.

Final Thoughts

Restaurant workers compensation protects your team and your business from financial devastation when injuries occur. You now understand what coverage actually pays for, which claim types cost the most, and exactly which prevention steps reduce injuries before they happen. The data shows that cuts and burns happen frequently but cost less per claim, while back injuries are rare but catastrophic at $60,000 to $85,000 each.

Prevention through slip-resistant footwear, immediate spill cleanup, structured safety training, and regular equipment maintenance directly reduces these costs and keeps your staff healthy. Review your current workers compensation coverage to confirm it matches your restaurant’s actual risk profile. If you employ line cooks, prep staff, and servers, your coverage needs differ from a fast-casual operation with lighter physical demands.

At Briggs Agency, Inc., we represent multiple top-rated carriers and compare options to find restaurant workers compensation that fits your operation and budget. Our local agents understand the specific risks restaurants face in Indiana and can tailor coverage to your staff size, job classifications, and hazard exposure. Contact us to review your current coverage or get a quote that reflects your restaurant’s actual needs.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Crown Point Contractor Coverage: Smart Protections for Builders

Running a construction business in Crown Point means managing real risks every single day. From job site accidents to equipment theft, the wrong coverage gap can drain your profits fast.

At Briggs Agency, Inc., we’ve helped local builders understand exactly what Crown Point contractor coverage they actually need. This guide walks you through the protections that matter most for your operation.

What Risks Actually Threaten Your Crown Point Construction Business

Job sites in Crown Point expose your business to specific, costly exposures that generic insurance won’t address. A worker steps on a nail and develops an infection requiring weeks off the job-that’s lost productivity and medical costs that workers’ compensation must cover. A subcontractor’s equipment damages a neighboring property during a residential framing project on Broadway-now you’re facing a liability claim that general liability needs to handle. Winter freeze-thaw cycles create scheduling delays and material waste on residential projects, forcing you to extend timelines and absorb labor costs. Equipment theft from job sites happens frequently enough that inland marine coverage becomes a practical necessity, not a luxury. Historic properties in Crown Point often contain asbestos or lead paint, exposing you to environmental liability claims if you’re not specifically protected. These aren’t hypothetical scenarios-they’re the daily realities that separate contractors who stay profitable from those who get wiped out by a single claim.

The Real Cost of Coverage Gaps

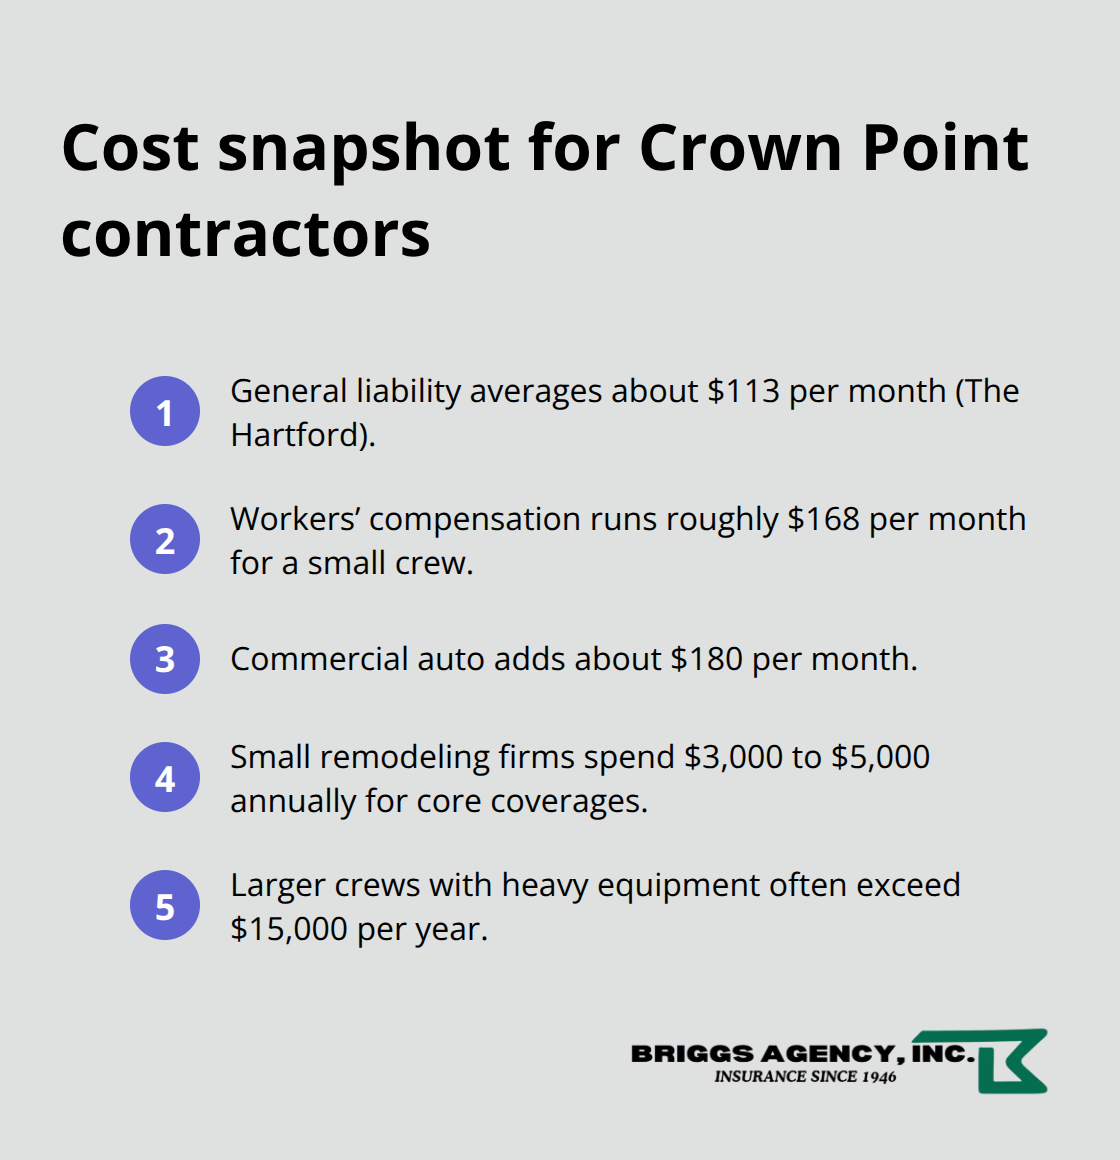
Most contractors drastically underestimate how much a single incident costs beyond the obvious medical bill or property damage. According to The Hartford, construction businesses pay about $113 per month on average for general liability insurance, which sounds cheap until you realize what happens without it. A $50,000 property damage claim from a work accident comes directly out of your pocket if you lack coverage.

At-a-glance monthly and annual insurance costs cited in the article for Crown Point contractors. - Crown Point contractor coverage

Workers’ compensation is required in Indiana for businesses with employees, and the cost-roughly $168 per month for a typical contractor operation-is far cheaper than paying medical bills and wage replacement yourself. Commercial auto coverage adds another $180 per month, but one vehicle accident without it can bankrupt a small operation. The Allen Thomas Group data shows small remodeling firms with one or two employees spend $3,000 to $5,000 annually for core coverages, while larger crews with heavy equipment exceed $15,000 yearly. That investment protects against catastrophic losses that would otherwise consume your entire year’s profit margin.

Coverage Built for Crown Point Construction Realities

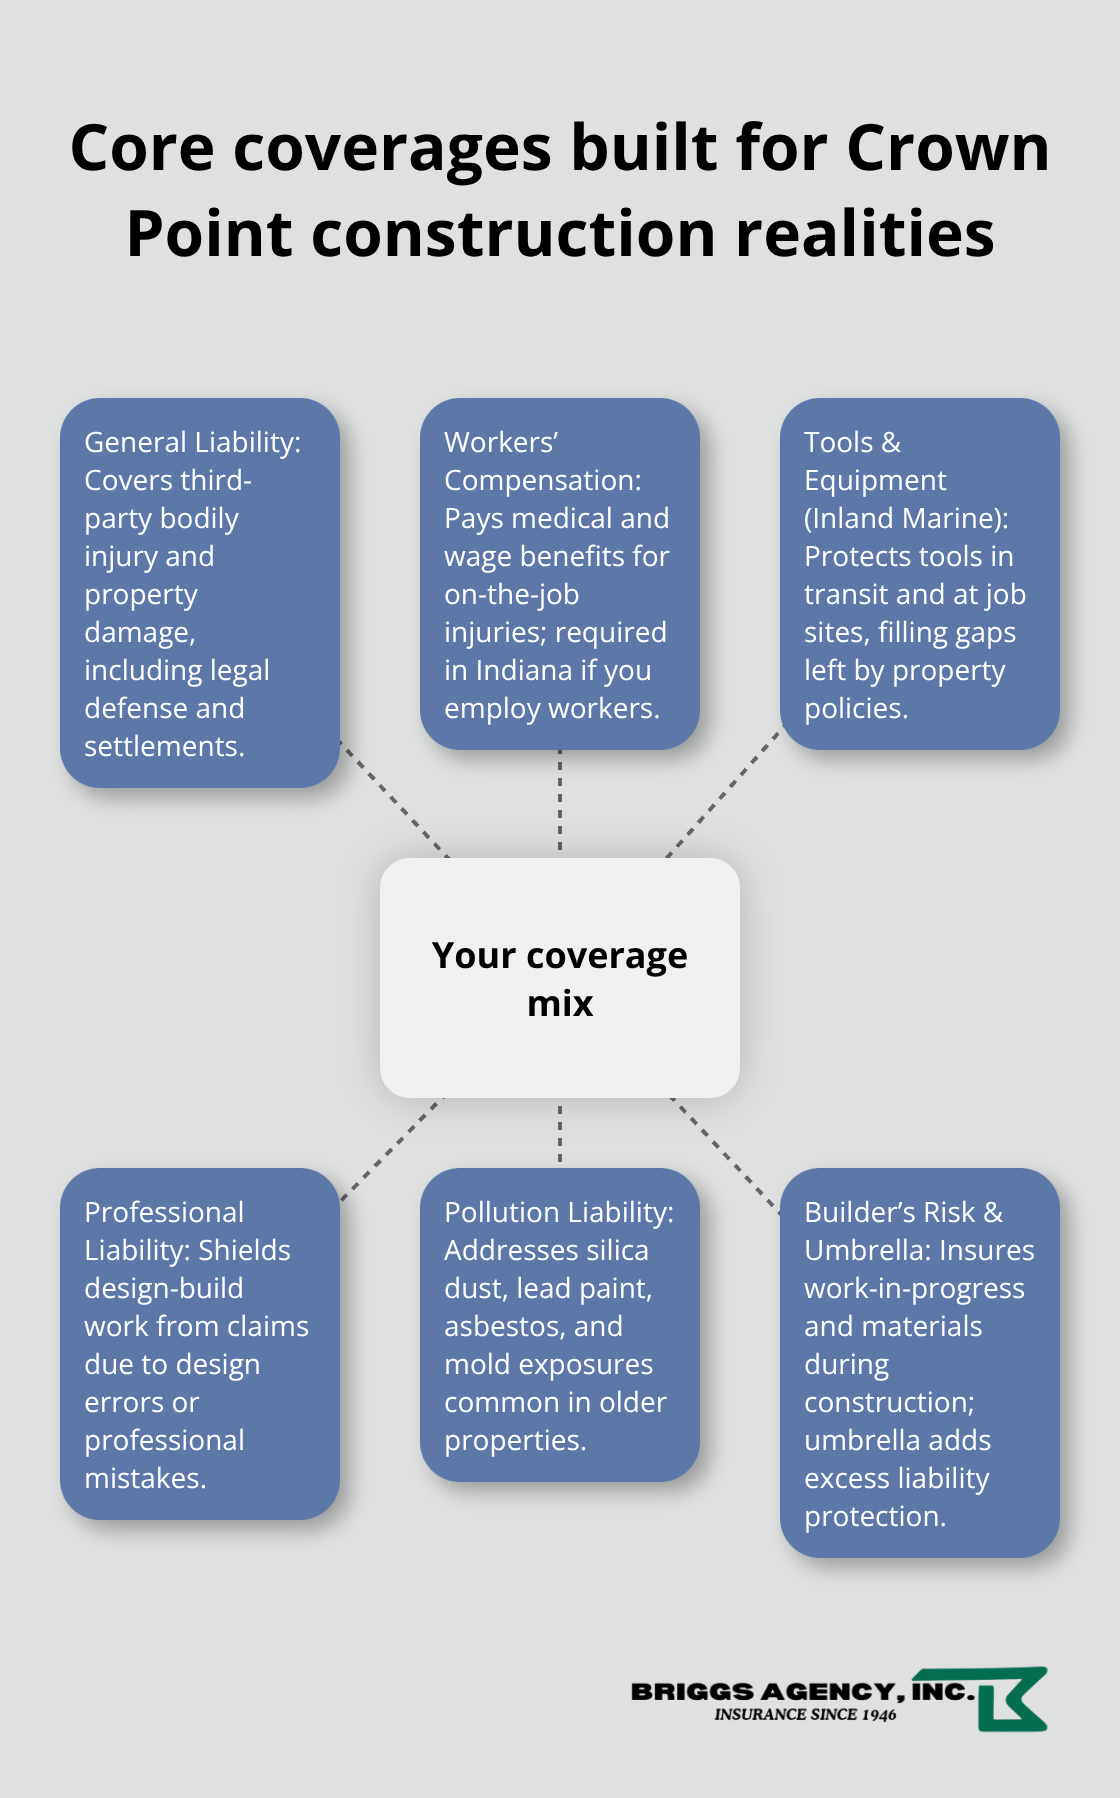
General liability covers third-party bodily injury and property damage arising from your work-someone gets hurt on your job site or your crew damages a neighbor’s fence. Tools and equipment coverage protects saws, nail guns, scissor lifts, and other tools while in transit or stored at job sites, filling gaps that standard commercial property policies leave uncovered. Workers’ compensation covers medical expenses and disability benefits for on-the-job injuries, and it’s mandatory if you have employees. Professional liability protects design-build contractors from claims due to design flaws or work mistakes. Pollution liability specifically covers exposure to silica dust, lead paint, asbestos, or mold during demolition or renovation-critical for Crown Point’s older properties. Builder’s risk insures structures, materials, and work-in-progress during construction, ending when a certificate of occupancy is issued.

Hub-and-spoke diagram showing the key insurance coverages that protect Crown Point contractors.

Umbrella liability extends excess protection above your primary policies, shielding personal assets from large verdicts.

Matching Coverage to Your Operation

The right combination depends entirely on your specific project types, crew size, and equipment value. A small residential remodeling crew needs different protections than a firm handling multi-trade commercial projects. Your project mix, the value of tools you transport to sites, and whether you employ workers or work solo all shape which coverages actually matter for your bottom line. An independent agency representing multiple carriers can compare options side-by-side and help you identify exactly which coverages protect your operation and which ones you can confidently skip. This approach saves money by eliminating unnecessary policies while ensuring you don’t face a coverage gap when you need protection most.

The Coverage Mix That Protects Crown Point Builders

General Liability: Your Foundation Protection

General liability forms the foundation for your operation because it covers third-party bodily injury and property damage claims that arise directly from your work. A subcontractor’s equipment damages a neighbor’s fence, a worker injures a homeowner during a residential project, or your crew causes water damage to adjacent property-general liability handles the legal defense and settlement costs. According to industry data, small businesses pay an average of $45 per month for general liability insurance, with annual policy costs ranging from around $250 to over $1,000 depending on your operation.

That cost scales based on your project type, crew experience, claims history, and the specific services you offer. Crown Point builders handling historic property work should factor in higher premiums because older homes carry elevated risk from asbestos, lead paint, and structural complications. General liability is non-negotiable because most clients require proof of coverage before allowing you on site, and many municipalities mandate it for contractor licensing. Without it, a single claim wipes out your savings and forces you to defend yourself without professional support.

Tools, Equipment, and Materials Protection

Tools and equipment coverage protects the saws, nail guns, scissor lifts, and specialized equipment you transport between job sites-coverage that standard commercial property policies explicitly exclude. Crown Point contractors face genuine theft risk at residential and commercial sites, plus weather damage from winter freeze-thaw cycles that damage equipment left exposed. Inland marine insurance covers your tools in transit and while stored at job sites, addressing the protection gap that property policies leave open.

Workers’ Compensation and Specialized Coverage

Workers’ compensation is mandatory in Indiana if you employ anyone, covering medical expenses and disability benefits for on-the-job injuries while shielding you from most employee lawsuits. The typical cost runs roughly $168 monthly for a small crew, making it far cheaper than absorbing medical bills and wage replacement yourself. Professional liability and pollution liability become critical for design-build contractors and firms handling renovation work on older properties where environmental exposures occur.

Finding the Right Mix Without Overpaying

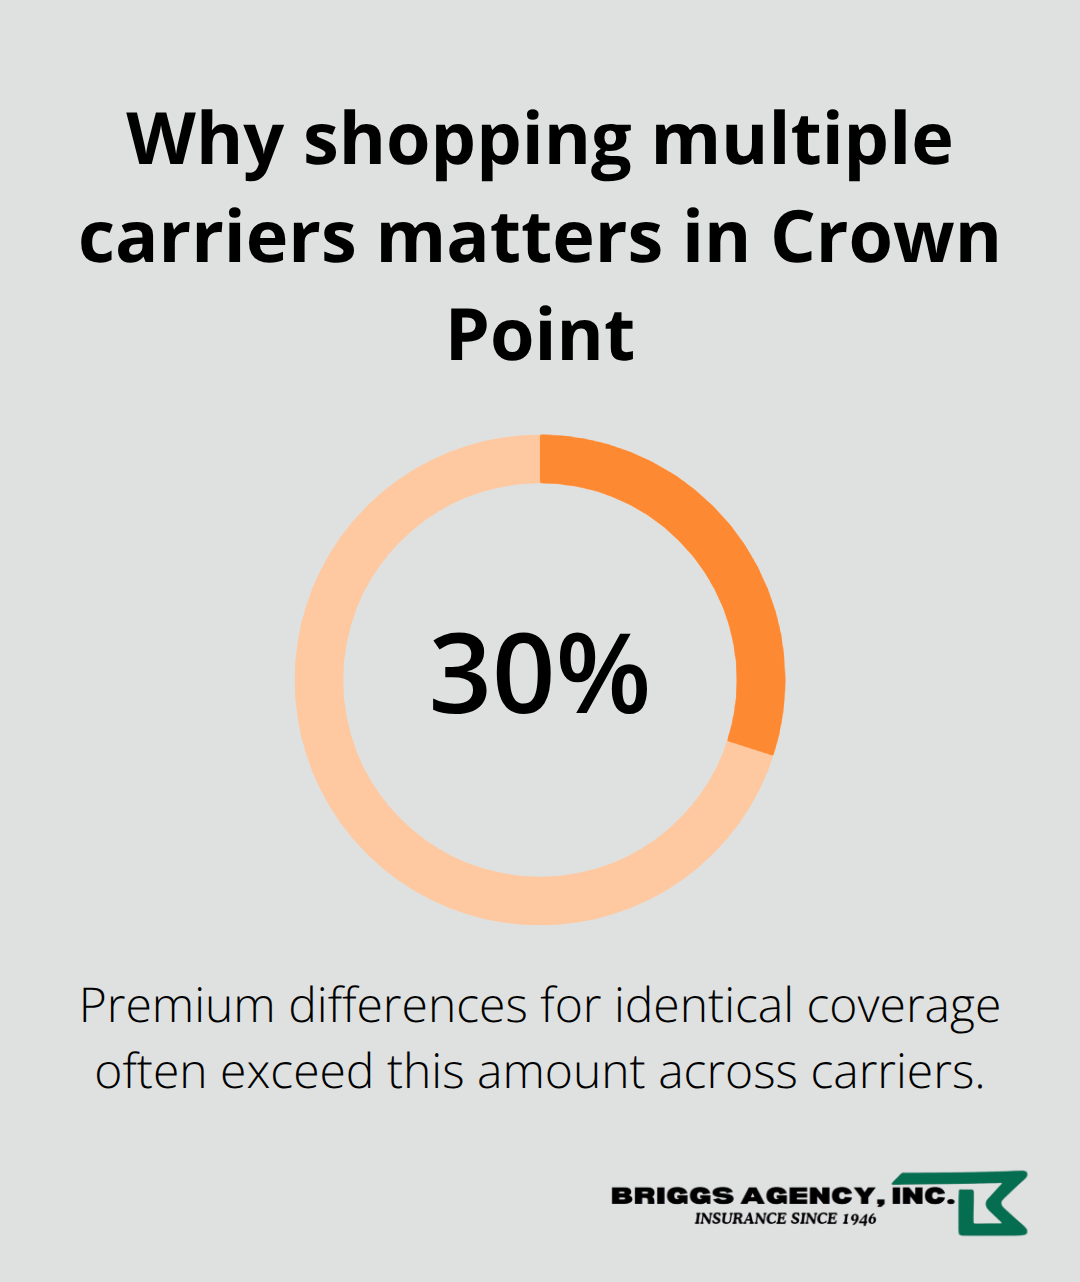
Premium differences for identical coverage often exceed 30 percent across carriers, and comparing quotes from multiple carriers reveals substantial savings opportunities. An independent agent representing top-rated carriers identifies which specialized policies actually apply to your specific operation rather than selling blanket protection you don’t need. Your project mix, crew size, equipment value, and whether you handle historic properties all shape which coverages protect your bottom line and which ones you can confidently skip.

Single-stat infographic showing that premiums can differ by 30% across carriers for identical coverage. - Crown Point contractor coverage

The right coverage combination depends entirely on your specific operation-and understanding your actual exposures helps you assess which protections matter most when you evaluate quotes from different carriers.

How to Pick the Right Coverage for Your Crew

Map Your Actual Job Site Exposures

Start by identifying your actual job site exposures instead of purchasing a standard package and hoping it fits. A residential remodeling crew working on single-family homes faces completely different risks than a firm handling multi-trade commercial projects or historic property renovations. Document your typical project types over the last year-are you mostly interior remodels, new construction framing, demolition work, or a mix? List the tools and equipment you regularly transport to sites, the number of employees on your typical crew, and whether you handle design-build work or strictly follow architect plans.

Crown Point’s older housing stock means if you work on historic properties, you’re dealing with asbestos, lead paint, and mold exposure that requires specific pollution liability coverage. Your project mix directly determines which coverages protect your operation and which ones waste money. A solo remodeler working alone needs different protection than a firm with five employees and a $50,000 equipment inventory.

Understand What Each Policy Actually Covers

Comparing quotes from multiple carriers reveals massive price differences for identical coverage-premium variations often exceed 30 percent across carriers for the same policy limits and deductibles. Request quotes from at least three carriers and specify your exact project types, crew size, equipment value, and whether you handle specialized work like renovation or demolition. When you receive quotes, ignore the total premium for a moment and examine what each policy actually covers.

A $3,000 annual premium sounds better than $4,200 until you discover the cheaper option excludes pollution liability or carries a $2,500 deductible instead of $1,000. Ask each carrier about their experience with contractors in Crown Point specifically-an agent who understands local winter delays, historic property risks, and regional claim patterns steers you toward carriers that price fairly for your specific exposures.

Work with an Agent Who Knows Crown Point Construction

An independent agency representing multiple top-rated carriers completes this comparison work for you, identifying which specialized policies actually apply to your operation and where you can confidently skip unnecessary coverage. A local agent who knows Crown Point construction provides guidance on real exposures rather than generic sales pitches, and you avoid both the catastrophic mistake of under-insuring and the financial drain of over-insuring. Your project mix, crew size, equipment value, and whether you handle historic properties all shape which coverages protect your bottom line and which ones you can confidently skip.

Final Thoughts

The right Crown Point contractor coverage protects your operation from the specific exposures you face every day, not from generic risks that may never affect your business. A residential remodeler working solo needs completely different protections than a firm with five employees handling multi-trade commercial projects and historic property renovations. Your actual project types, crew size, equipment value, and whether you work on older homes determine which coverages genuinely protect your bottom line and which ones drain money without adding real protection.

Local expertise matters because an agent who understands Crown Point construction knows the winter freeze-thaw delays that extend timelines, the asbestos and lead paint exposures in historic properties, and the equipment theft patterns at local job sites. That knowledge shapes which carriers price fairly for your specific risks and which coverages actually apply to your operation. An independent agency representing multiple top-rated carriers completes the comparison work for you, identifying exactly which protections you need and where you can confidently skip unnecessary policies.

Premium variations frequently exceed 30 percent across carriers for identical coverage, meaning a few hours comparing quotes from multiple carriers saves thousands annually while ensuring you don’t face a coverage gap when you need protection most. Contact Briggs Agency, Inc. today to compare quotes and build the Crown Point contractor coverage that fits your crew and your budget.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Restaurant Business Interruption: Planning for Revenue Gaps

Restaurant closures happen fast, and when they do, the financial damage spreads quickly. A single equipment failure, health code violation, or weather event can shut down your doors for days or weeks, leaving you scrambling to cover payroll and rent while revenue stops cold.

At Briggs Agency, Inc., we’ve seen how restaurant business interruption catches owners off guard. The good news is that proper planning and the right insurance can protect your bottom line when the unexpected strikes.

What Threatens Your Restaurant’s Operations

Weather, Utilities, and Supply Chain Risks

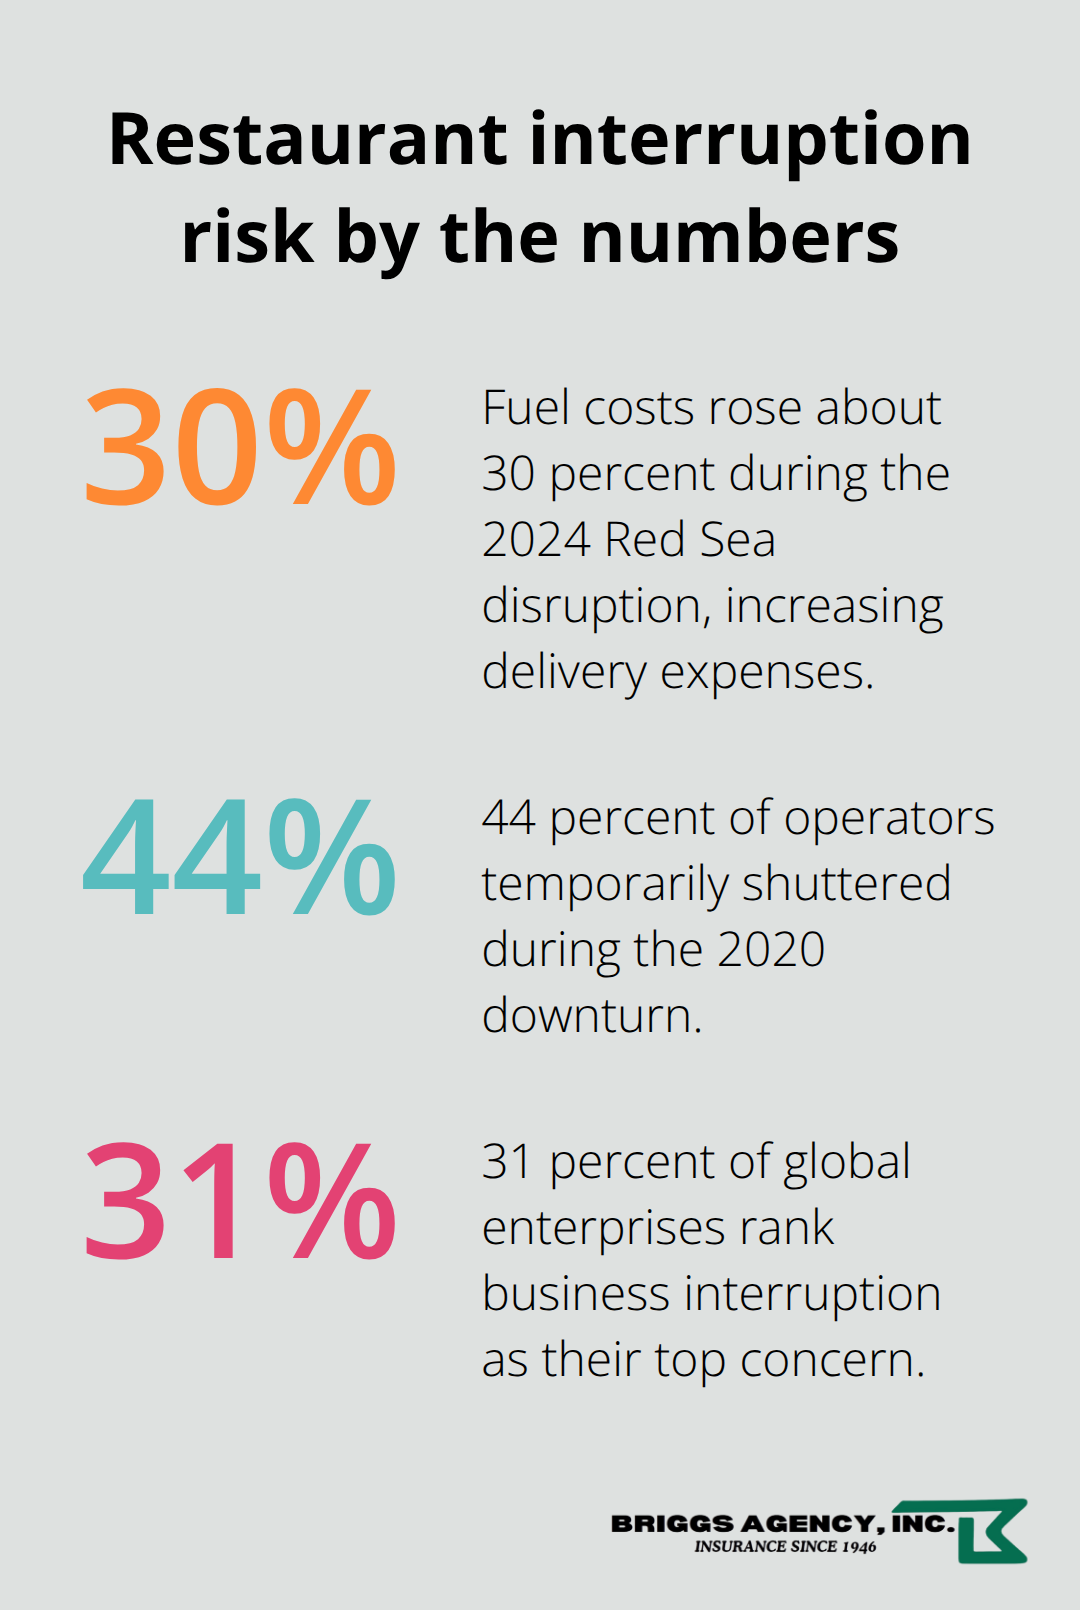
Weather events and utility failures hit restaurants harder than most businesses because operations depend on continuous power, reliable deliveries, and consistent staffing. Utility outages cause immediate revenue loss, a risk that intensifies during Atlantic hurricane season from June through November. Equipment breakdowns compound the problem-a failed walk-in cooler or kitchen range stops service for hours, spoils inventory, and forces menu cuts that drive customers away. Supply chain disruptions extend downtime unpredictably. The Red Sea shipping disruption in 2024 added roughly 4,000 miles and 2–3 weeks to shipments for restaurants relying on global suppliers, with fuel costs rising about 30 percent. A missing delivery of specialty ingredients forces menu changes that reduce revenue.

Health Code Violations and Disease Outbreaks

Health code violations and disease outbreaks create a different kind of threat. A positive COVID case among staff or a health inspection failure forces an immediate shutdown, and the World Health Organization’s 2020 pandemic declaration exposed a critical gap: many restaurant insurance policies exclude non-damage interruptions like disease outbreaks, leaving owners unprotected when forced closures happen without physical damage to the building.

Staffing Gaps and Their Revenue Impact

Staffing departures directly shrink seating capacity and sales. A missing server reduces revenue by shortening how many tables you can serve during a shift. The Canadian Federation of Independent Business reports that about 1 in 4 small businesses permanently close after a disaster, and Forbes Tech Council data shows 44 percent of operators temporarily shuttered during the 2020 downturn while fixed costs like mortgage and rent continued to accumulate.

Key percentages on outages, shutdowns, and business interruption risk - Restaurant business interruption

Kitchen hazards compound staffing challenges, as your team faces constant exposure to burns, cuts, and slip hazards in tight spaces with high-pressure operations.

Building Operational Resilience

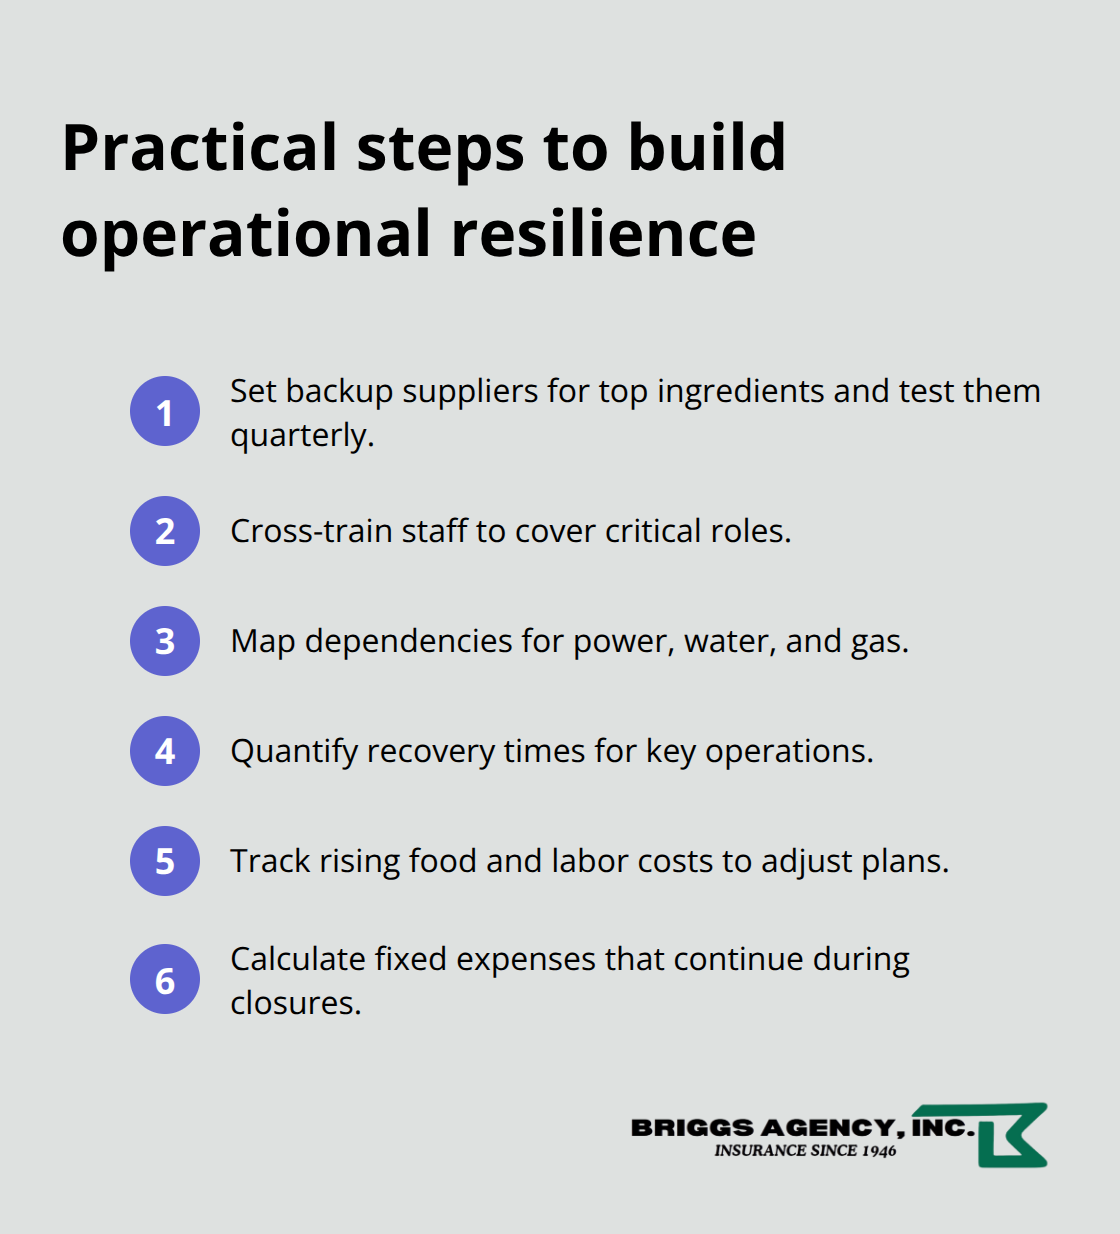
These aren’t theoretical risks-they’re operational realities that demand concrete planning. Identify at least two backup suppliers for your top 20 ingredients and test them quarterly to protect against single-point failures. Cross-train staff so multiple people handle critical roles; a single absence won’t shut down service. Map your dependencies-which operations fail if electricity drops, if water stops, if gas lines rupture-and quantify recovery times.

Actionable resilience checklist for U.S. restaurants - Restaurant business interruption

Food costs have risen roughly 25 percent and labor costs roughly 18 percent over the past two years according to Restaurants Canada, which means fixed overhead during a closure drains cash faster than ever. The threat isn’t whether an interruption happens; it’s how fast you can respond and how well you’re protected when it does. That protection starts with understanding what your operation actually costs to maintain when revenue stops.

What Really Costs You When Revenue Stops

The Immediate Financial Drain

A three-day closure from a kitchen fire doesn’t just mean three days without sales. During those 72 hours, your mortgage or lease payment still arrives, your insurance premiums don’t pause, and your utilities keep running even though the kitchen sits dark. According to the Allianz Global Survey 2024, 31 percent of global enterprises rank business interruption as their top concern, and restaurants face this risk acutely because fixed costs dwarf variable ones. Food costs and labor fluctuate with volume, but rent, property taxes, loan payments, and baseline utility costs remain fixed whether you operate or stay closed. The math turns brutal fast: a mid-sized restaurant with 150 covers per day at a 30 percent profit margin loses roughly 4,500 dollars in daily profit during a forced closure. That same restaurant still owes 3,000 to 5,000 dollars in fixed monthly expenses divided across daily operations. Three weeks of downtime means 15,000 to 35,000 dollars in lost profit plus another 10,000 to 15,000 dollars in fixed costs that consumed cash with zero revenue to offset them.

Rising Costs Amplify the Damage

Restaurants Canada reports that food costs rose roughly 25 percent and labor costs roughly 18 percent over the past two years, which means your fixed-cost burden has grown while margins have compressed. A disruption that might have been survivable five years ago now threatens the business itself. Your overhead expenses accelerate the financial crisis during any shutdown. Mortgage payments, property taxes, insurance premiums, and loan obligations don’t pause for closures-they accelerate the cash drain. Equipment leases, franchise fees, and utility minimums continue accumulating. A two-week closure that once cost 20,000 dollars in lost profit now costs 30,000 dollars or more because your baseline expenses have risen faster than your ability to raise menu prices.

The Hidden Cost: Customer Loss and Market Share Erosion

The damage extends beyond the immediate shutdown period. When you reopen, customers don’t automatically return. About 1 in 4 small businesses permanently close after a disaster according to the Canadian Federation of Independent Business, and revenue loss during closure directly correlates with that failure rate. Your regulars discover competitors during your downtime, loyalty erodes, and staff departures compound the problem because experienced servers and kitchen staff take jobs elsewhere when you close unexpectedly. Market share loss isn’t theoretical-it’s measurable. A restaurant that closes for two weeks loses not just 14 days of revenue but also the ongoing revenue from customers who shifted their habits. Recovery takes months, not days. Some never come back.

Why Insurance Bridges the Gap

Business interruption insurance compensates for lost income and helps pay for ongoing expenses, ensuring your restaurant can recover and reopen without financial strain. The policy protects your ability to weather the storm and emerge intact. Understanding what coverage you actually need requires calculating your specific exposure-the daily revenue you generate, the fixed costs you carry, and how long your operation could survive without income. That calculation determines whether your current coverage matches your actual risk or leaves you exposed to a financial crisis that planning alone cannot prevent.

How Much Business Interruption Coverage Do You Actually Need

Calculate Your Daily Revenue and Fixed Costs

Business interruption insurance for restaurants isn’t about picking a number and hoping it covers the damage. It’s about calculating what your operation actually costs to maintain when revenue stops, then building coverage around that specific number. Start with your gross revenue from the last 12 months and divide it by 365 to find your average daily revenue. Then identify your fixed costs: mortgage or lease, property taxes, insurance premiums, loan payments, utility minimums, and payroll for salaried staff who stay on the payroll during a closure. These costs don’t pause when you close.

A restaurant generating 8,000 dollars in daily revenue with 3,500 dollars in fixed monthly expenses faces a brutal equation during downtime. Each day closed costs you roughly 267 dollars in fixed expenses plus the profit margin you would have earned on that day’s revenue. Over two weeks, that adds up to roughly 8,000 dollars in fixed costs alone, not counting lost profit.

Account for Rising Overhead and Compressed Margins

According to the National Restaurant Association, food and labor costs for the average restaurant have each gone up 35% over the last 5 years, which means your baseline overhead has expanded faster than your pricing power. That compression makes underinsurance far more dangerous than it was five years ago. Coverage limits should reflect your worst-case restoration timeline, not the average disruption. If a major equipment failure or supply chain collapse could force you closed for three weeks, your coverage should protect against a full three-week loss, not a one-week assumption.

Adjust your calculation for seasonality: a summer closure costs more for a restaurant with peak season revenue than a winter closure. Growth trends matter too. If you’ve expanded capacity or added a second location, your coverage needs to reflect that expanded exposure.

Identify Policy Exclusions and Coverage Gaps

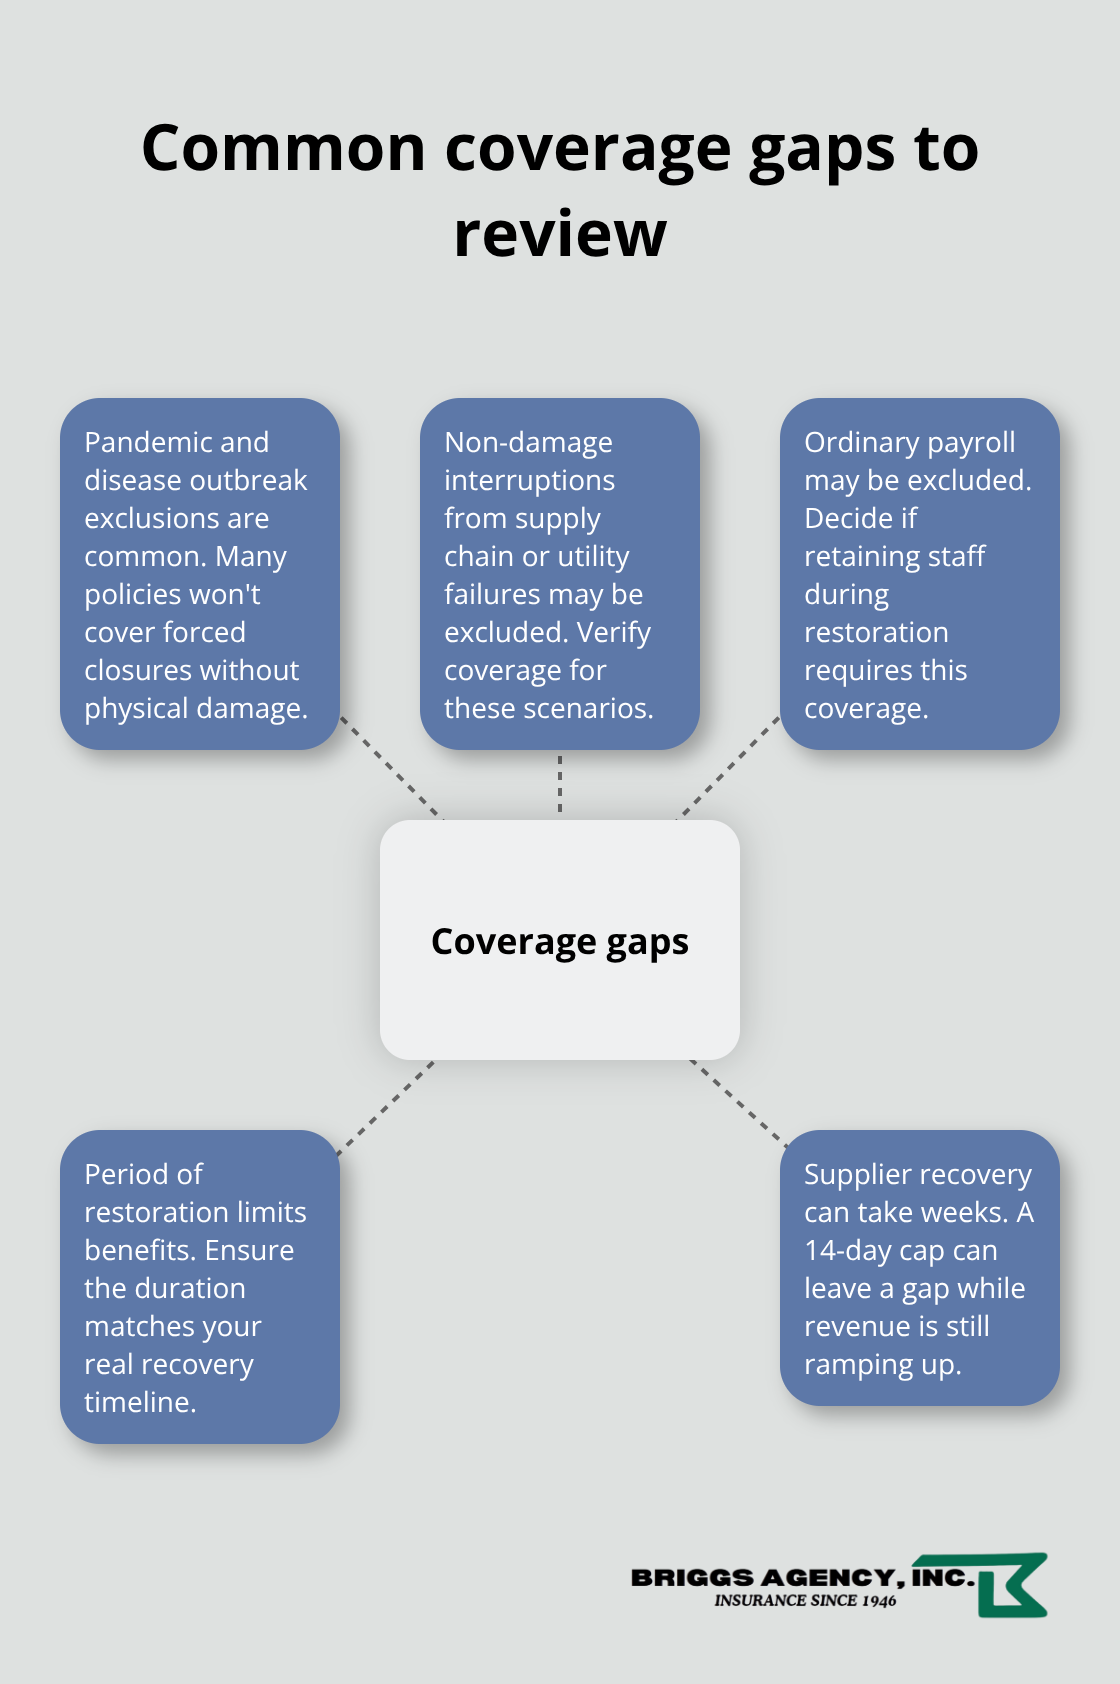
The policy language itself determines what actually gets covered, and many restaurant owners miss critical gaps. Pandemic and disease outbreak exclusions appear in standard policies, a problem highlighted by the COVID-19 pandemic when many restaurants discovered their coverage didn’t protect against forced closures without physical property damage. Verify that your policy covers non-damage interruptions if your restaurant faces supply chain risk, utility disruptions, or health code enforcement actions.

Some policies exclude ordinary payroll entirely, cutting your premium but leaving you exposed when you need to retain your team during restoration. The period of restoration clause defines how long benefits run after you reopen. If your supplier network takes four weeks to fully restore after a disruption, but your policy covers only 14 days of restoration, you face a gap when revenue is still ramping up and fixed costs continue.

Policy exclusions and limitations that can expose restaurants

Extend Coverage for Longer Recovery Periods

Consider adding an extended restoration endorsement if your supply chain or customer recovery takes longer than standard terms. Work with an insurance professional who understands restaurant operations to review your specific policy language and identify exclusions that could leave you exposed. At Briggs Agency, Inc., our experienced local agents compare options across multiple carriers and tailor policies to match your actual risk, helping you avoid the gaps that catch restaurant owners off guard.

Final Thoughts

Restaurant business interruption strikes without warning, and the financial damage spreads fast when fixed expenses continue while revenue stops. A mid-sized restaurant loses thousands in daily profit during downtime, plus thousands more in fixed costs that never pause (mortgage, insurance, utilities, loan payments). Food and labor costs have risen sharply over the past two years, which means your overhead burden weighs heavier than ever, making even short closures financially devastating.

Business interruption insurance bridges the gap between what planning prevents and what it cannot. A solid continuity plan with backup suppliers, cross-trained staff, and documented procedures reduces your exposure and speeds recovery, but planning alone does not pay your mortgage when you face forced closure. Insurance covers lost income and ongoing expenses, protecting your ability to weather the storm and reopen without financial strain.

Calculate your actual daily revenue and fixed costs, then review your current coverage to see if it matches your real exposure. Check your policy language for exclusions around disease outbreaks, utility disruptions, and extended restoration periods. We at Briggs Agency, Inc. understand restaurant operations and can help you compare coverage options across multiple carriers to find protection that actually covers your bottom line when the unexpected strikes.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Property Insurance for Businesses: A Practical Risk Reduction Plan

Your business assets represent years of investment and hard work. Property insurance for businesses protects that investment from fires, theft, weather damage, and other threats that could derail operations.

At Briggs Agency, Inc., we help business owners understand what coverage actually matters for their situation. This guide walks you through building a protection strategy tailored to your specific needs.

What Your Business Property Insurance Actually Covers

Standard commercial property insurance protects the physical assets that keep your business running. Your building structure, equipment, inventory, and tools all receive coverage under a basic policy, which means damage from fire, theft, wind, and lightning gets reimbursed at either replacement cost or actual cash value depending on your policy terms. The Hartford reports helping over 1.5 million small business owners secure this protection, and for good reason-most businesses underestimate how much they’d lose if a single fire or break-in happened tomorrow.

Understanding Building and Asset Coverage

When you own or lease your building, the structure itself receives coverage. When you rent, your landlord’s policy covers the building, but your equipment, displays, and inventory inside remain your responsibility. That distinction matters because renters often skip coverage thinking the landlord’s policy protects everything. It doesn’t. You need your own policy to cover what you own.

Equipment Breakdown Insurance

Equipment breakdown insurance deserves serious consideration if your business depends on machinery, HVAC systems, or specialized tools. A power surge or internal failure can cost thousands to repair or replace, and standard property coverage doesn’t always cover these losses. If you operate a restaurant, a broken refrigerator or oven creates immediate lost income on top of replacement costs. If you run a manufacturing operation, a failed compressor or production line shutdown hits harder. Adding equipment breakdown coverage fills this gap.

Business Interruption Coverage

Business interruption insurance allows businesses to pay fixed expenses while the property is closed for repairs. This coverage reimburses your lost income and ongoing operating expenses when a covered event forces you to close temporarily. If a fire shuts you down for three weeks, this coverage pays your payroll, rent, utilities, and other fixed costs while you’re unable to operate. Most business owners focus on replacing the damaged property but forget they still owe employees and landlords during recovery. The combination of property coverage plus business interruption coverage protects both your assets and your cash flow when disaster strikes.

Understanding what your policy covers is only half the battle. The risks your business actually faces-and how to prepare for them-shape which coverages matter most for your operation.

Common Property Risks Businesses Face

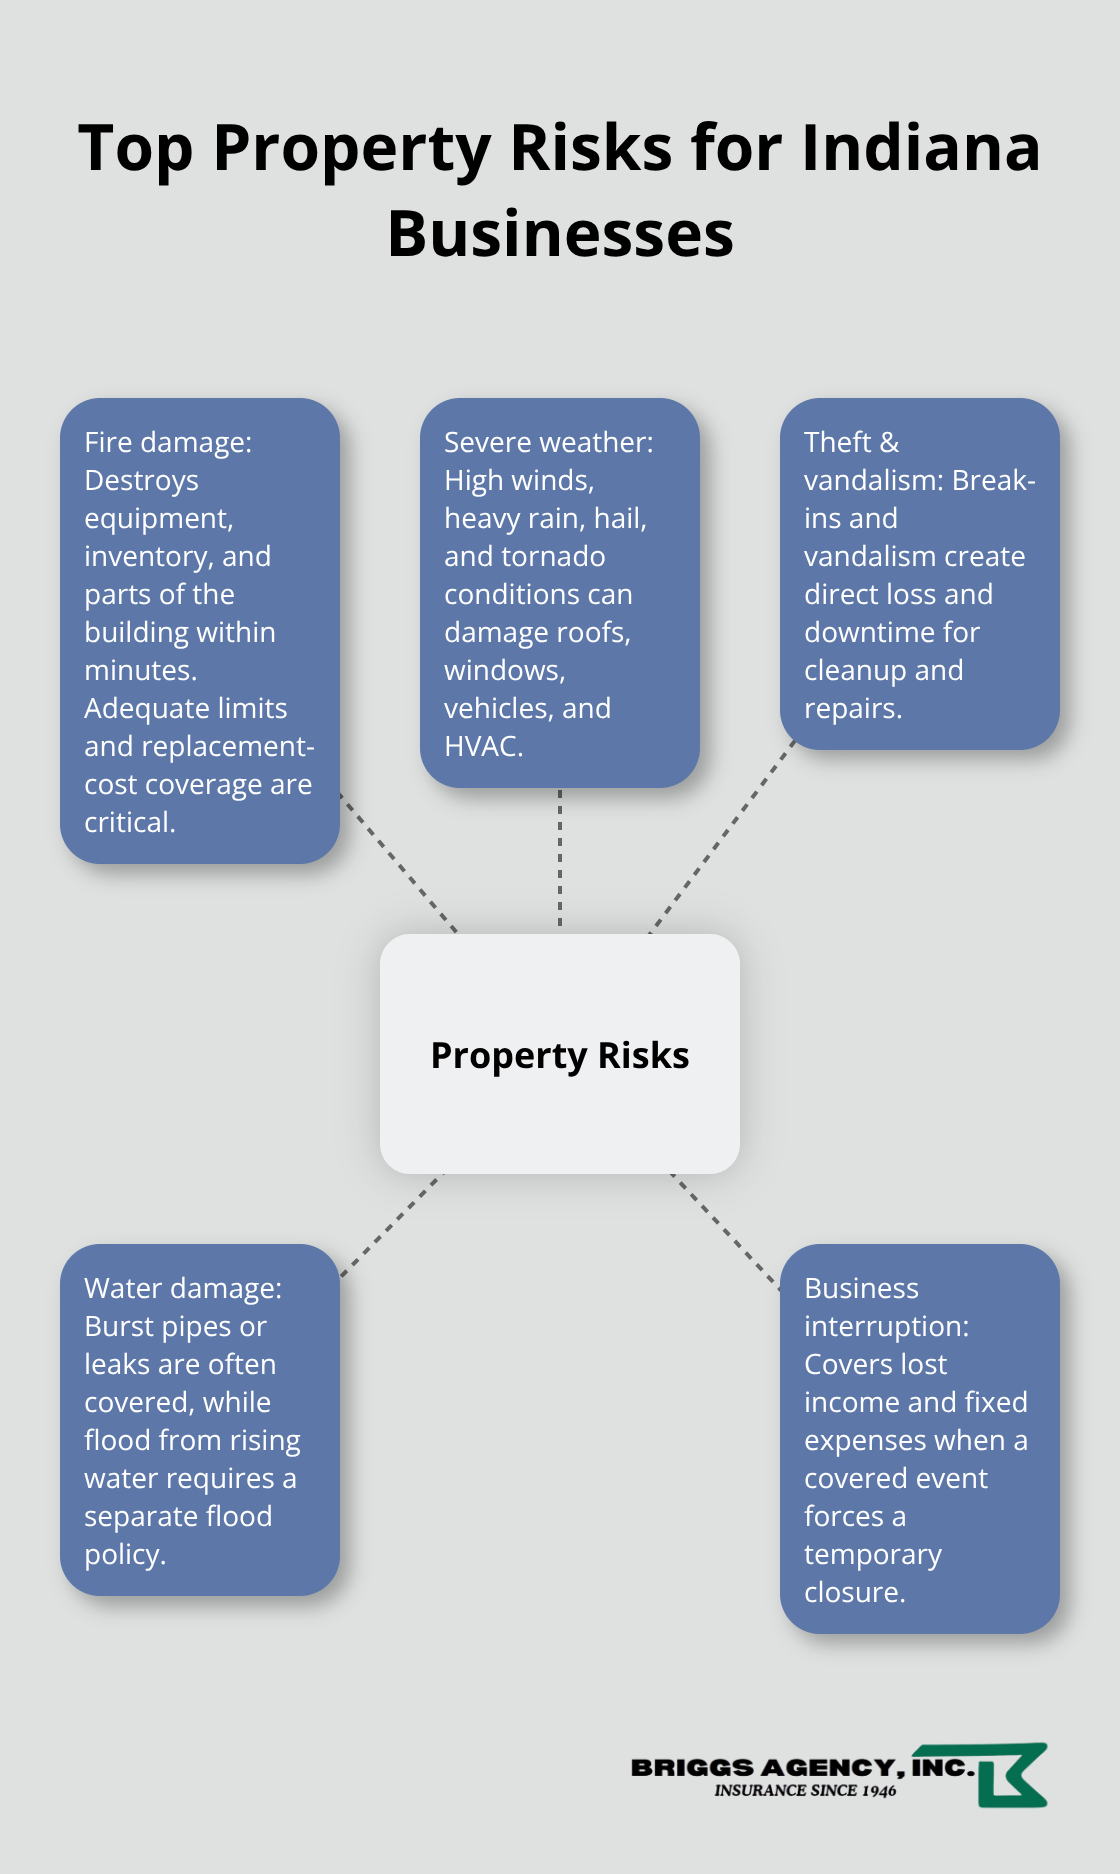
Fire and weather-related damage create the most significant threats to business property. U.S. fire departments respond to roughly 470,500 structure fires annually, with substantial property loss and business interruption. A single fire destroys equipment, inventory, and building structure in minutes-damage that replacement cost coverage reimburses, but only if you carry adequate limits. Beyond fire, severe weather compounds the problem. High winds tear off roofs and shatter windows. Heavy rain causes flooding in basements where you store inventory or equipment. Hail damages vehicles and HVAC units. These events happen regularly in Indiana, and businesses often discover their coverage falls short after the loss occurs. That’s why reviewing your property limits annually matters-your inventory and equipment values change as your business grows, but many owners lock in a policy and forget to adjust it.

Theft and Vandalism Hit Harder Than Expected

Theft and vandalism strike harder than most business owners expect, especially for retail locations and businesses in accessible areas. The FBI’s Uniform Crime Reporting Program shows property crime remains persistent across communities, with burglary and theft losses reaching billions annually. A single break-in costs money for stolen goods, damaged doors or windows, inventory loss, and business interruption while you clean up and repair. Vandalism adds another layer-spray paint, broken glass, and damaged signage create immediate costs plus potential safety hazards.

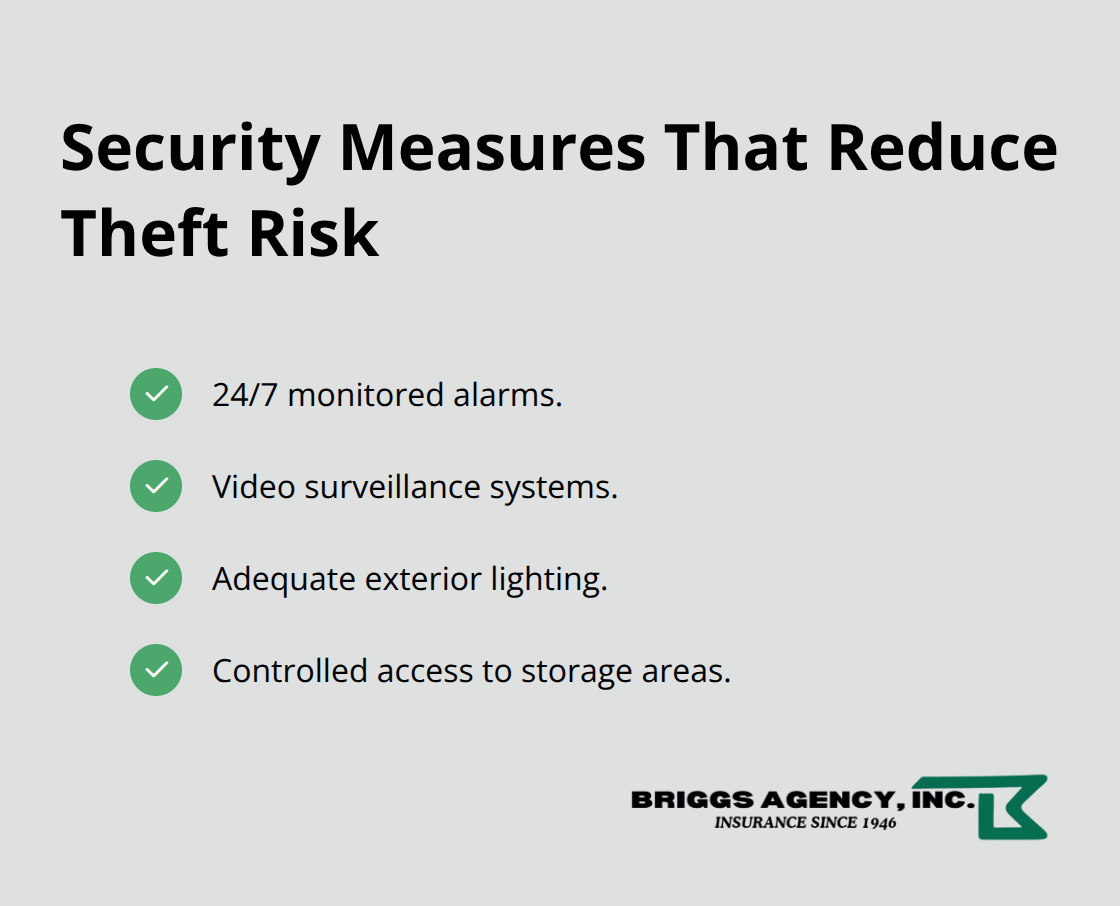
Security measures reduce this risk substantially. 24/7 monitored alarms, video surveillance systems, adequate exterior lighting, and controlled access to storage areas deter criminals and provide evidence if theft occurs. These controls also lower your insurance premiums because insurers recognize that documented security measures reduce claim frequency.

Checklist of security controls that lower theft and vandalism risk for U.S. small businesses - Property insurance for businesses

Water Damage Comes From Multiple Sources

Water damage presents a different challenge because it originates from several sources. Burst pipes during winter, foundation cracks allowing groundwater in, roof leaks, or backed-up sewers all cause water intrusion that damages flooring, drywall, equipment, and inventory. Standard property policies cover sudden, accidental water damage like a burst pipe, but they exclude damage from flooding caused by heavy rain or rising water tables.

Hub-and-spoke diagram showing the main property risks that can impact U.S. small businesses in Indiana

That’s why commercial flood insurance through the National Flood Insurance Program exists as a separate purchase-it covers the water damage that standard policies don’t. If your business operates in a flood-prone area or sits in a basement or ground-floor space, flood insurance isn’t optional; it’s essential protection that prevents catastrophic loss.

Understanding these risks shapes which coverages matter most for your operation. The next step involves assessing your specific assets and vulnerabilities to build a protection strategy that actually fits your business.

How to Build a Property Insurance Strategy That Fits Your Business

Map Your Assets and Replacement Costs

Start by walking through your building and listing every asset your business owns or depends on. Document the structure itself, all equipment needed for daily operations, inventory sitting on shelves or in storage, furniture, computers, and specialized tools specific to your industry. Assign a realistic replacement cost to each category, not the depreciated value you see on your balance sheet. A five-year-old HVAC unit costs $8,000 to replace today, not the $3,000 book value your accountant shows.

Most business owners underestimate replacement costs by 30 to 40 percent, which means they carry inadequate coverage limits and face out-of-pocket losses after a claim. Once you know your asset values, identify which losses would hurt most. A manufacturing business might lose $50,000 per day in revenue if production equipment fails, while a retail shop loses $5,000 daily in sales if a fire closes the storefront. That gap determines whether business interruption coverage is essential or secondary.

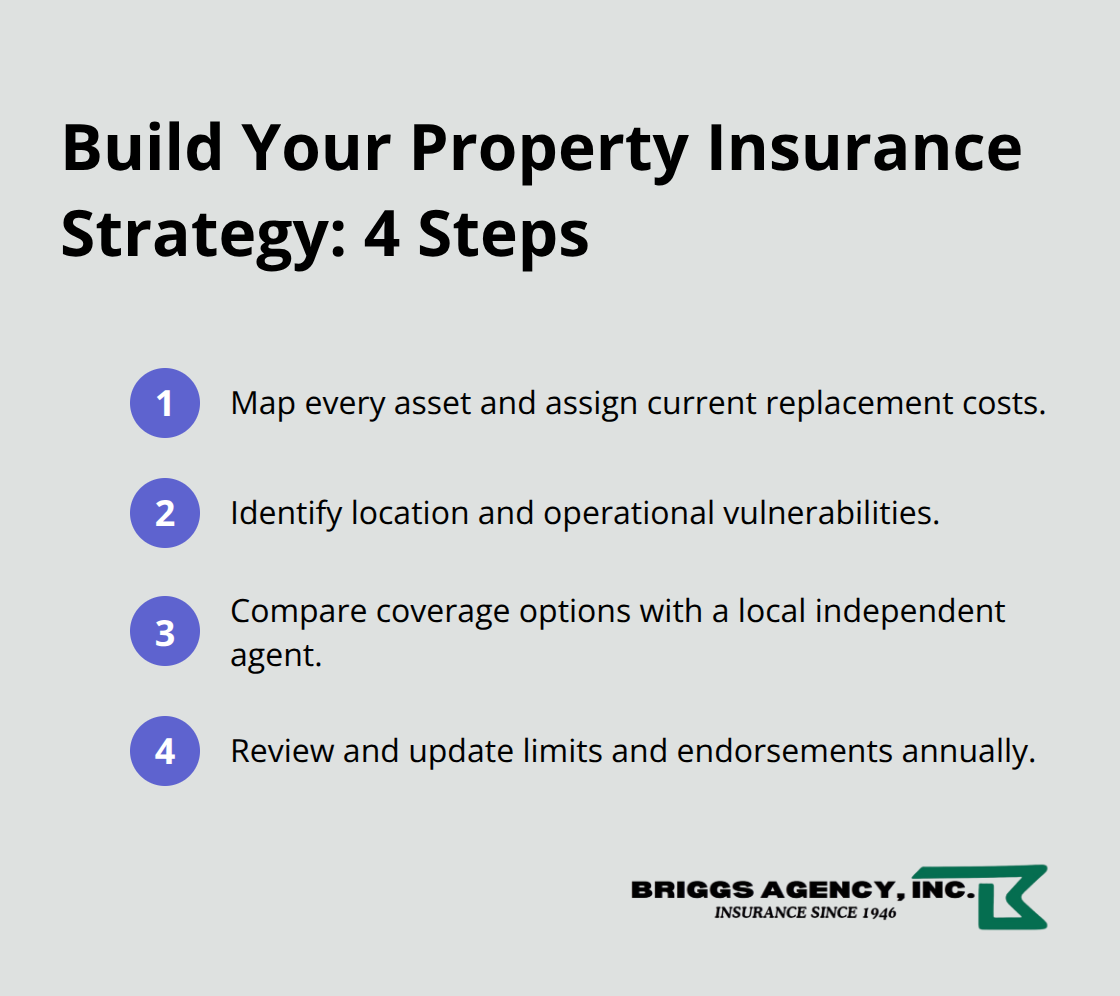
Compact ordered list of four steps U.S. business owners can follow to tailor property insurance - Property insurance for businesses

Identify Your Specific Vulnerabilities

Assess your specific vulnerabilities next. Does your location sit in a flood-prone area? Does your building contain aging electrical systems that increase fire risk? Does your neighborhood experience break-ins based on local crime data? These factors shape which additional coverages matter most and which risk controls lower your premiums.

Security measures reduce theft risk substantially. 24/7 monitored alarms, video surveillance systems, adequate exterior lighting, and controlled access to storage areas deter criminals and provide evidence if theft occurs. Insurers recognize that documented security measures reduce claim frequency, which translates to lower premiums for your business.

Work with a Local Agent to Compare Coverage Options

A local insurance agent who understands your industry provides value that online quotes cannot match. They know which carriers offer the best rates for restaurants versus manufacturing operations versus retail shops, and they understand regional risks specific to Indiana weather patterns and local property values. When comparing options, look beyond premium price alone. One carrier might offer equipment breakdown coverage for $400 annually while another charges $800, but the first carrier might have a $5,000 deductible while the second has $1,000. Calculate the true cost by considering what you’d actually pay out-of-pocket during a claim.

A Business Owner’s Policy bundles property, liability, and business income coverage into one package, which costs less than purchasing coverages separately and eliminates gaps between policies. If your business has specialized risks, endorsements add targeted protection without overpaying for unnecessary coverage.

Review and Update Your Policy Regularly

Review your policy annually when your business changes, not just when renewal notices arrive. If you purchased new equipment, expanded to a second location, or increased inventory values, your coverage limits need adjustment. Many business owners lock in a policy and forget it exists until a loss occurs, then discover their limits haven’t kept pace with growth. Set a calendar reminder each year to contact your agent and review whether your coverage still matches your actual assets and operational needs.

Final Thoughts

Property insurance for businesses protects what you’ve built, but only when coverage matches your actual assets and risks. The strategy we’ve outlined-mapping your assets, identifying vulnerabilities, comparing options with a knowledgeable agent, and reviewing annually-prevents the costly gaps that catch most business owners off guard. You now understand what standard policies cover, which additional endorsements fill specific needs, and how security measures and maintenance practices lower your premiums over time.

Professional guidance matters because insurance isn’t one-size-fits-all. A restaurant faces different risks than a manufacturing operation or retail shop, and your coverage should reflect those differences. We at Briggs Agency, Inc. serve Indiana businesses by representing multiple top-rated carriers and tailoring policies to your specific situation. Our local agents understand regional weather patterns, property values in Crown Point and surrounding areas, and which carriers offer competitive rates for your industry.

Start by scheduling a conversation with a local agent who can review your current coverage and identify gaps. Bring your asset list and recent financial statements so they understand your business operations and replacement costs. Ask about equipment breakdown coverage if you depend on machinery, business interruption protection if a shutdown would strain cash flow, and security discounts if you’ve invested in alarms or surveillance.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Fleet Trucking Insurance: Coverage That Scales With Your Operations

Running a trucking fleet means managing more than just routes and schedules. Your vehicles, drivers, and cargo face real risks every day on the road.

Fleet trucking insurance protects your business from the financial impact of accidents, damage, and liability claims. At Briggs Agency, Inc., we help fleet operators find coverage that grows with their operations, whether you’re managing five trucks or fifty.

What Your Fleet Actually Needs to Be Protected

Primary Auto Liability: Your Biggest Cost Driver

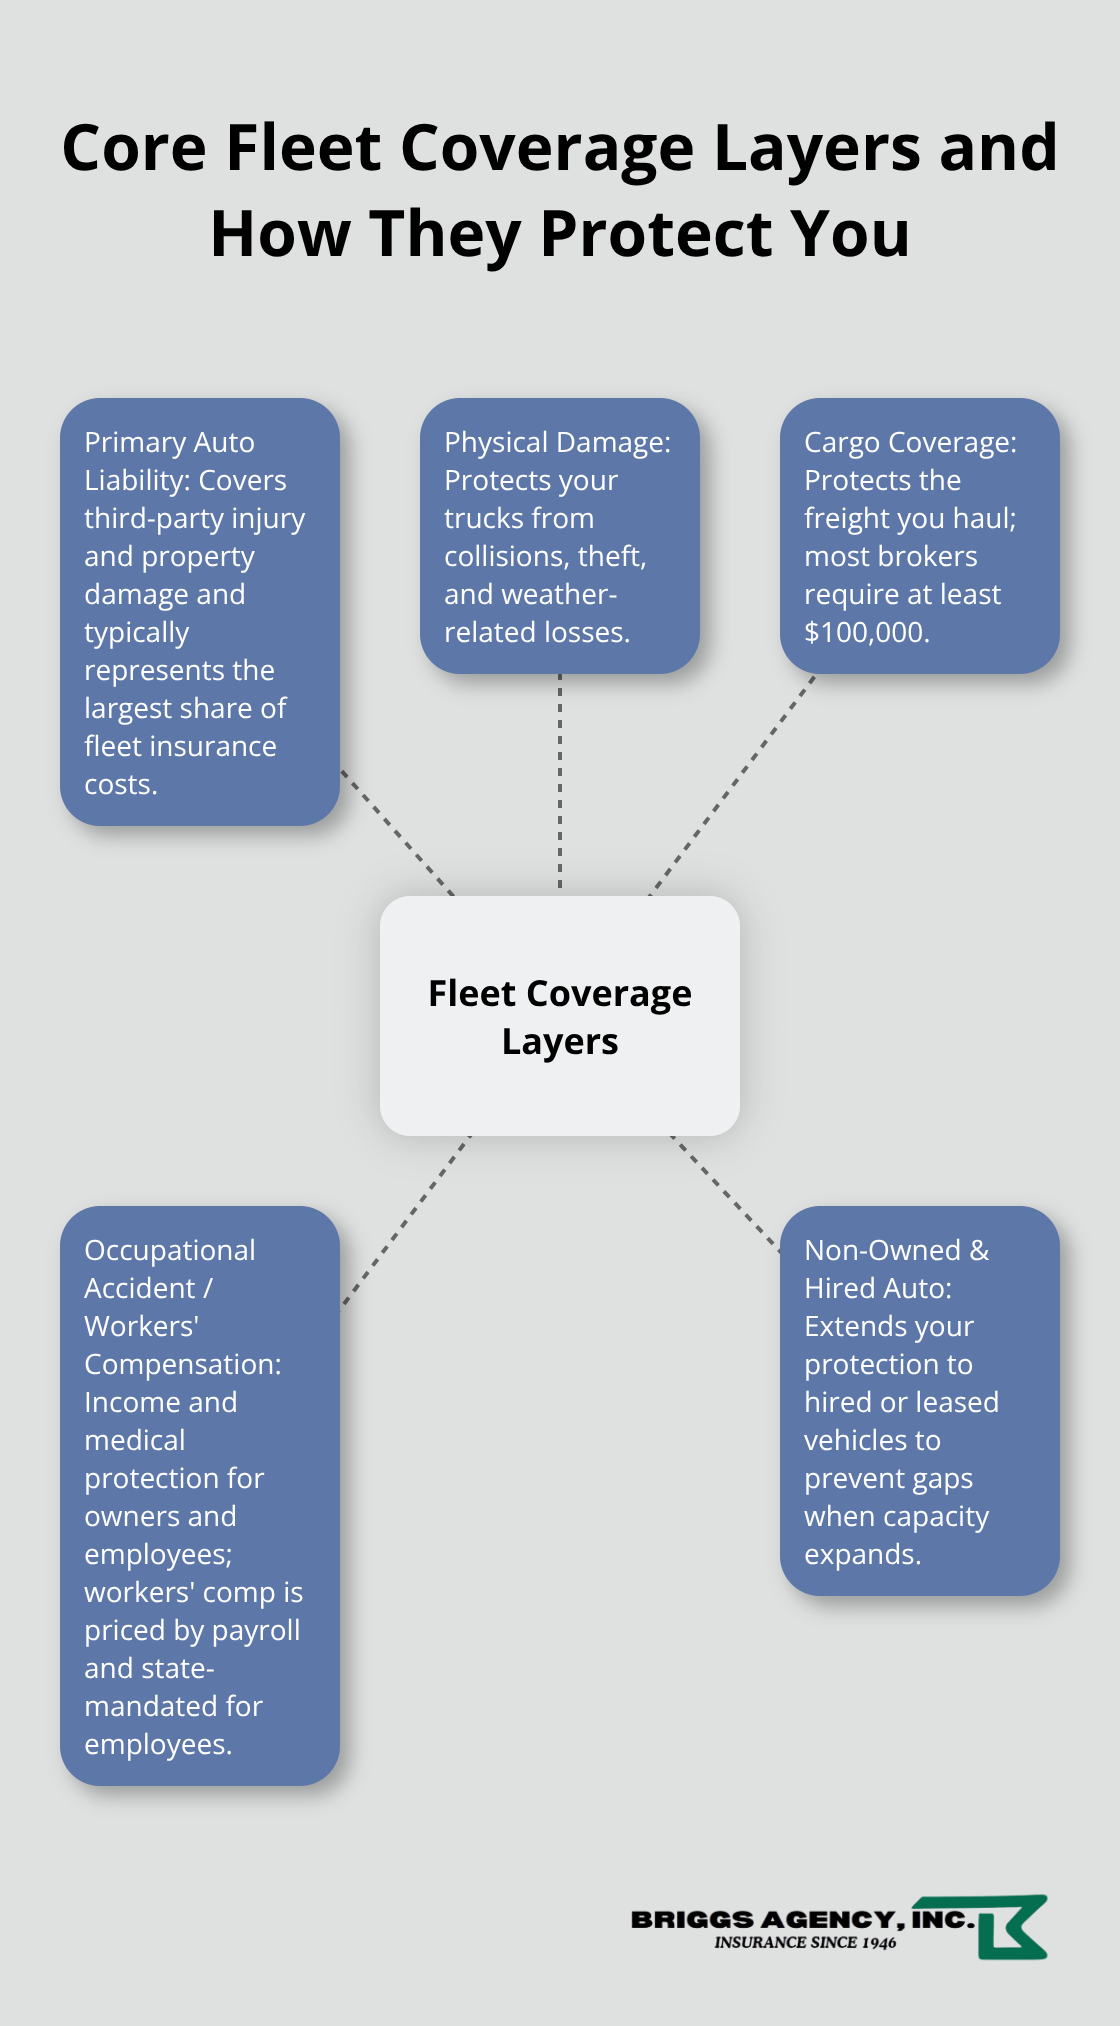
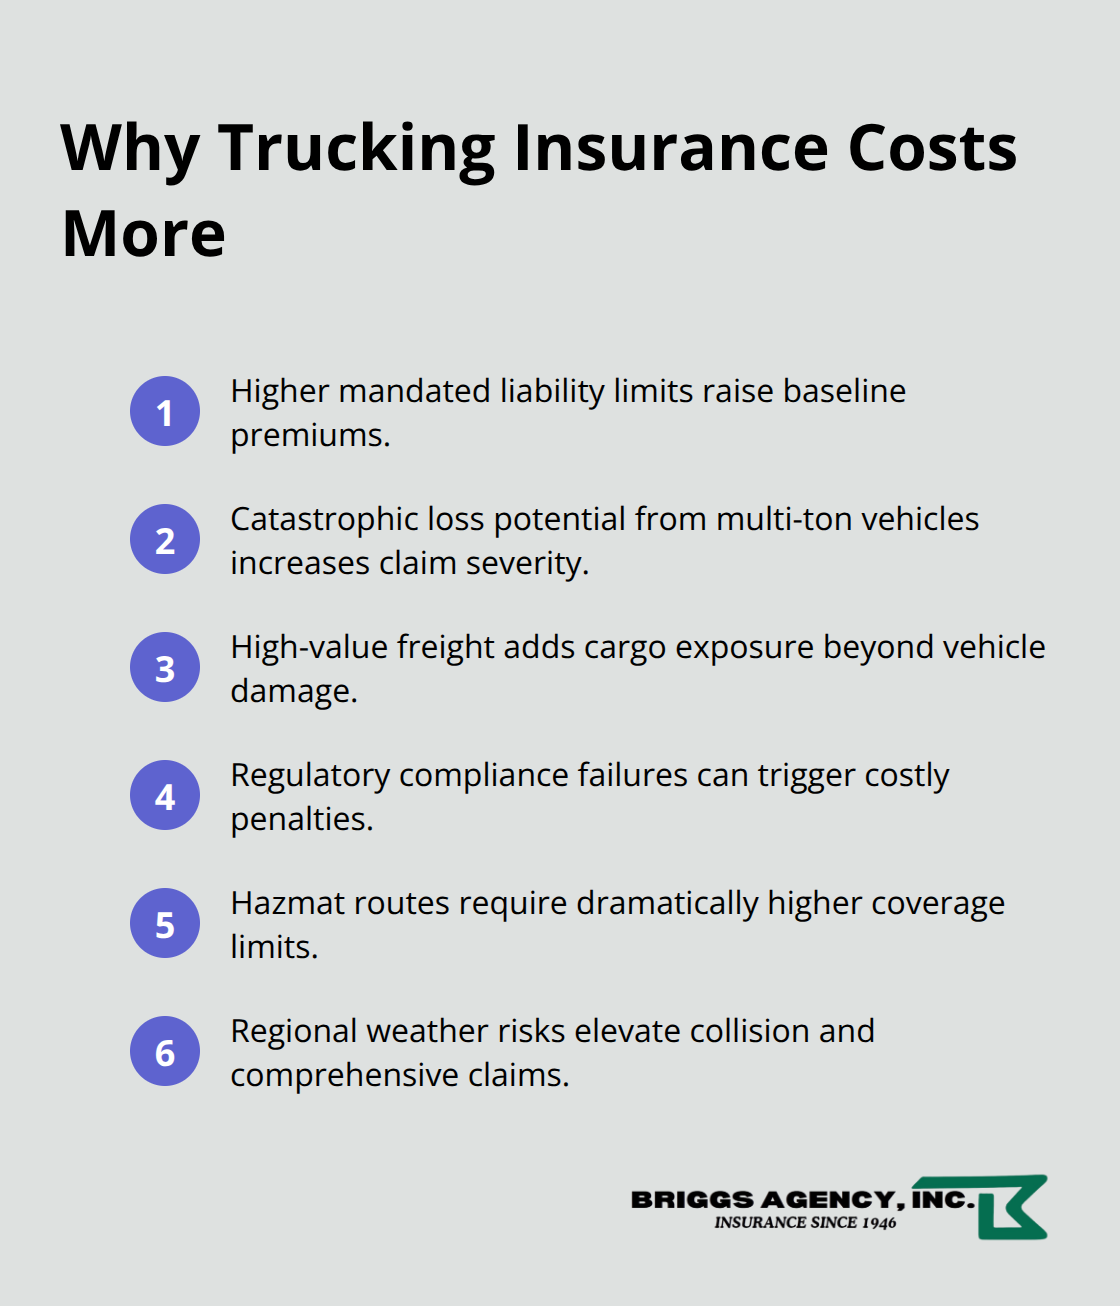
Primary auto liability covers you when your drivers cause injury or property damage to third parties, and it accounts for 50 to 65 percent of your total fleet insurance costs, typically running $5,000 to $10,500 per truck annually. The reason it dominates your budget is straightforward: jury verdicts in trucking cases have exploded. Between mid-2020 and early 2023, average nuclear verdicts reached $27.5 million, which means carriers price in catastrophic risk. If you operate in states like New Jersey, Louisiana, Delaware, New York, or Connecticut, your liability premiums will be substantially higher due to dense urban corridors and active plaintiff litigation. A single truck in New Jersey costs around $20,763 annually in premiums compared to Mississippi at roughly $3,552, according to 2026 rate data. This geographic spread forces many operators to rethink their service territories entirely.

Physical Damage and Cargo Protection

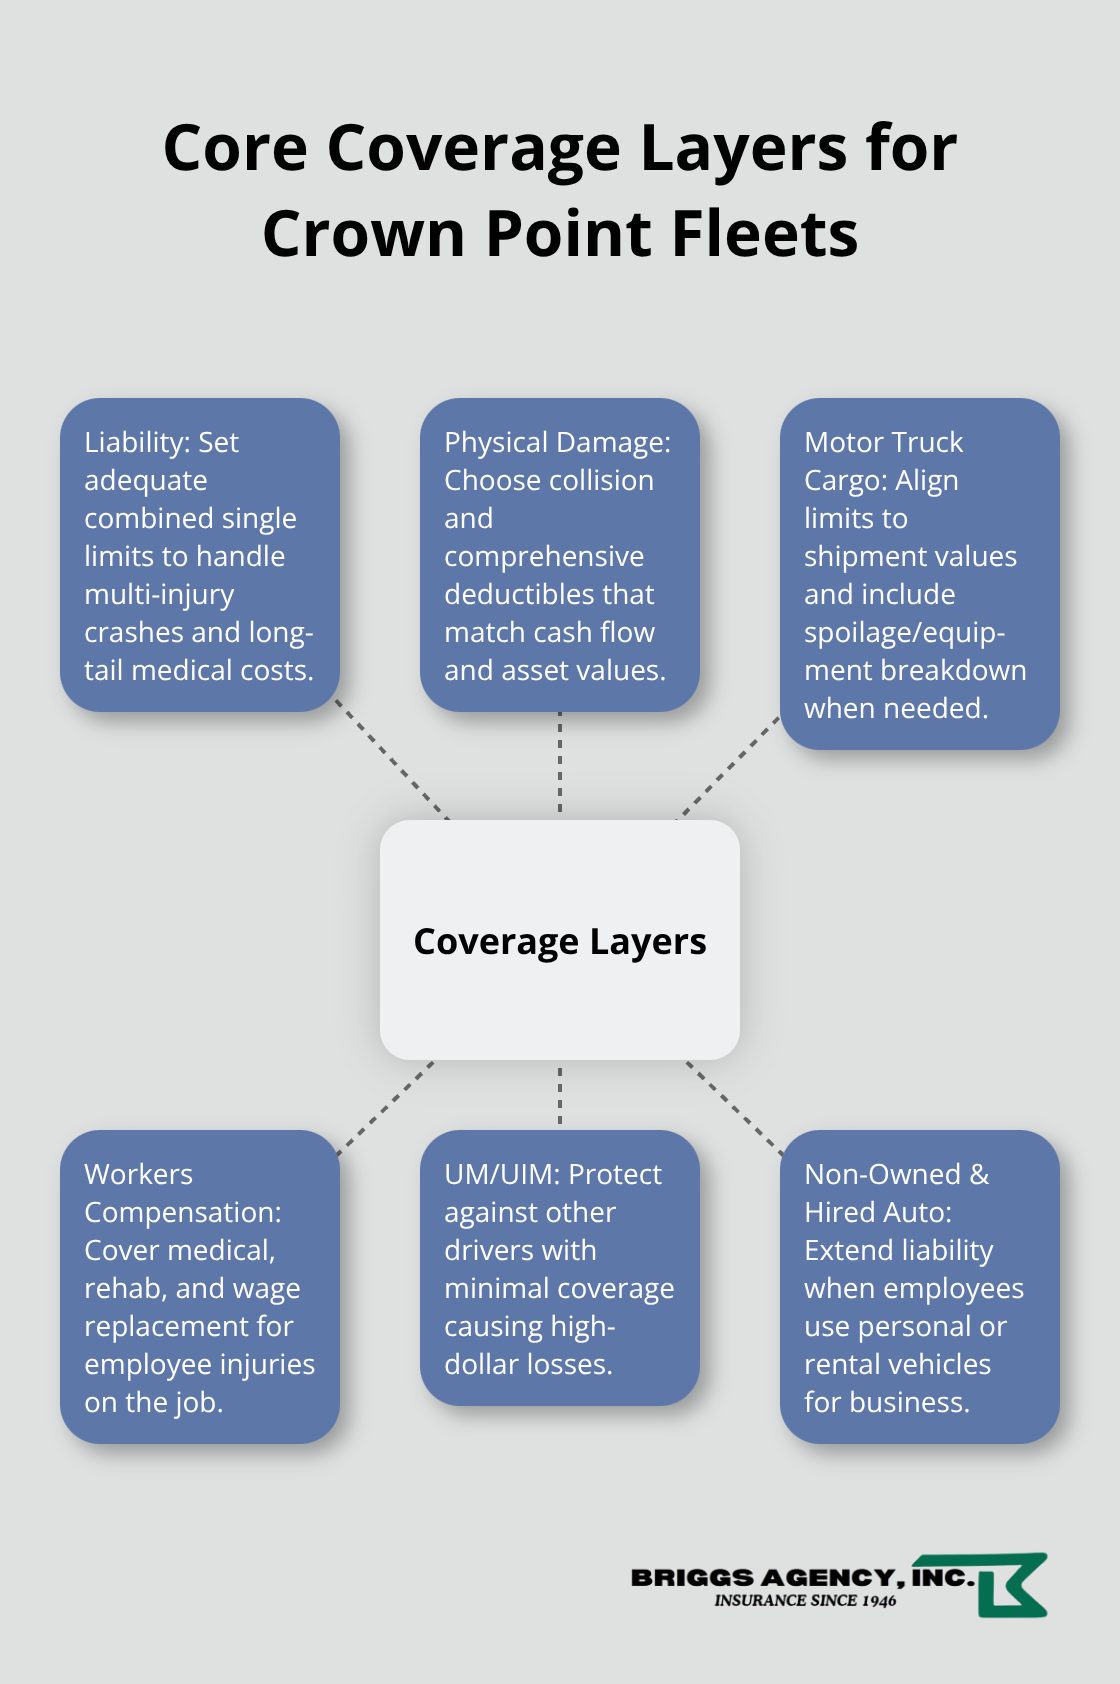
Physical damage coverage protects your trucks from collisions, theft, and weather, while cargo coverage protects the freight you haul. Most freight brokers require a minimum of $100,000 in cargo coverage, so this becomes non-negotiable if you want to secure loads. Cargo theft reached record levels in 2024 and stayed elevated into 2025, concentrated in food, metals, and electronics, which means underwriters tighten terms and demand stronger verification protocols. Your coverage structure must match your actual operational model-whether you own all equipment, lease some, or hire drivers with their own rigs.

Additional Coverage Layers for Your Operation

For owner-operators leasing to carriers, occupational accident coverage runs about $1,600 to $2,200 per year and protects you if injury prevents you from working. Workers’ compensation is priced on your payroll rather than truck count and is state-mandated for employee drivers. If you hire or lease vehicles from other operators, non-owned and hired vehicle coverage extends your protection to those trucks, preventing gaps when you temporarily expand capacity. These layers work together to address the specific risks your fleet faces based on how you actually operate.

Infographic showing the main fleet insurance coverage layers and what each one protects. - Fleet trucking insurance

The coverage you select today shapes how easily you can scale tomorrow. As your fleet grows, your insurance structure either supports that expansion or creates friction. Understanding what each layer protects-and why you need it-positions you to make decisions that align with your growth plans rather than fighting against them.

Matching Your Fleet Profile to the Right Coverage Structure

Fleet Size Shapes Your Pricing and Structure

Fleet size determines everything about how your insurance gets priced and structured, so start there before comparing carriers. A fleet of five trucks operates under completely different economics than a fleet of 50, and insurers price accordingly. Small fleets with two to nine trucks pay per-vehicle rates with minimal discounts, while mid-size carriers running 10 to 24 trucks qualify for fleet-rated pricing that spreads risk across multiple units. Large carriers with 25 to 49 trucks and enterprise programs with 50 or more units receive customized underwriting and negotiated rates, but face much closer scrutiny of safety programs and loss history. Enterprise fleets pay roughly 38% less per unit than non-fleet operators.

Compact list showing how insurance pricing and structure shift by fleet size tier. - Fleet trucking insurance

Your vehicle types matter equally because a fleet of light-duty pickups presents different risk than heavy-haul rigs or refrigerated trailers. Insurers evaluate not just the number of vehicles but their value, age, and how you use them. A 20-truck fleet at midpoint rates costs approximately $252,000 annually, while a 40-truck fleet at the same midpoint runs about $432,000. These numbers shift dramatically based on your operating territory and route patterns.

Geographic Location Overwhelms Other Pricing Factors

Geographic location overwhelms most other pricing factors, so evaluate where you actually operate before selecting a carrier. The most expensive states like New Jersey, Louisiana, Delaware, New York, and Connecticut share dense urban corridors and aggressive litigation environments, while the Midwest offers the most affordable rates with six of the top 15 lowest-cost states located there. Operating in multiple states requires carriers with broad appetite across those regions, not just local players. A single truck in New Jersey costs around $20,763 annually compared to Mississippi at roughly $3,552, a spread that forces many operators to rethink their service territories entirely.

Coverage Limits, Deductibles, and Carrier Comparison

When comparing coverage limits and deductibles, avoid the trap of matching your competitor’s structure or accepting whatever the first quote shows. Instead, break out your costs by coverage layer: auto liability typically runs $5,000 to $10,500 per truck annually, cargo coverage depends on your freight requirements, and workers’ compensation scales with payroll. Higher deductibles directly reduce premiums, and many fleets benefit from structured excess arrangements rather than single-layer coverage. Match your deductible to your cash flow situation, not the lowest number available, and consider how your financial reserves align with your risk tolerance.

Start your carrier comparison 120 to 180 days before renewal, not 30 days out when your options narrow. Provide clean loss runs, current safety data, and evidence of driver training or telematics adoption. Carriers reward proactive safety with credits for video dashcams paired with driver coaching, automatic emergency braking systems, and strict cargo verification protocols. Request quotes from at least three carriers because rate variation for identical coverage often exceeds 20 percent based on how each underwriter evaluates your specific risk profile.

Your fleet’s operational structure-whether you own all equipment, lease some, or hire drivers with their own rigs-directly influences which coverage layers you need and how carriers will price them. Understanding this connection between your actual operations and your insurance structure positions you to make decisions that align with your growth plans rather than fighting against them.

What Actually Reduces Your Fleet Insurance Costs

Driver Safety Records and Training Programs

Driver safety records form the foundation of your premium because insurers treat each driver as a risk multiplier across your entire fleet. A single driver with multiple violations or at-fault accidents can push your rates up 15 to 25 percent or more, which means one bad hire costs you thousands annually across your whole operation. Formal driver training programs directly reduce this risk, and carriers reward them with measurable credits. Video telematics paired with driver coaching creates a documented safety culture that underwriters want to insure, often lowering premiums by 10 to 30 percent compared to fleets without these systems.

Dashcams specifically help exonerate drivers after claims, reducing liability exposure and protecting your loss history from inflated settlements. The data matters more than the equipment alone, so implement a system where drivers understand they are monitored for coaching, not punishment. Fleets that adopt this approach see improved retention and lower incident frequency because drivers know their performance directly affects the company’s bottom line.

Vehicle Maintenance and Equipment Standards

Vehicle maintenance and equipment standards separate fleets that control costs from those that chase claims. Newer trucks with automatic emergency braking systems reduce crash frequency, though repair costs for ADAS-equipped vehicles run higher when damage occurs, creating a tradeoff that carriers are still pricing into underwriting. Underwriters examine maintenance records closely because a fleet with documented preventive maintenance demonstrates operational discipline and reduces mechanical failure claims.

Equipment age matters significantly, with older trucks facing steeper premiums due to higher failure risk and increased repair costs. Your claims history then determines whether carriers view you as a reliable risk or a problem account. Fleets with frequent small claims often pay more than those with one major claim because frequency signals systemic operational issues, while severity can sometimes be dismissed as bad luck.

Timing Your Renewal and Managing Claims History

Start your renewal process 120 to 180 days early and give yourself time to clean up your loss runs, gather safety documentation, and demonstrate improvements before presenting to carriers. Carriers tighten terms when they see cargo theft, identity fraud, or repeated similar claims, so implement cargo verification protocols and anti-fraud measures now to prevent premium increases later. This proactive approach (combined with strong documentation) positions your fleet as a lower-risk account that carriers compete to insure rather than one they reluctantly accept.

Checklist of actionable steps fleets can take to reduce insurance premiums and improve underwriting results.

Final Thoughts

Fleet trucking insurance works best when it scales alongside your operations rather than forcing you to rebuild coverage every time you add trucks or expand into new territories. The structure you build today-your coverage layers, deductible strategy, and carrier relationships-either supports that expansion or creates obstacles. Starting with the right foundation means understanding your fleet size, geographic footprint, and operational model so you can select limits and deductibles that match your actual risk.

Your driver safety programs, maintenance discipline, and claims management directly influence what carriers will offer you at renewal. Fleets that invest in telematics, driver training, and documented loss control don’t just reduce accidents; they build underwriting credibility that translates into competitive rates and flexible terms as you scale. The difference between a fleet that manages risk proactively and one that reacts to claims often exceeds 20 to 30 percent in annual premiums.

Starting your renewal process 120 to 180 days early gives you leverage to shop multiple carriers, present your safety improvements, and negotiate terms before capacity tightens. Contact Briggs Agency, Inc. to discuss your fleet’s specific needs and get customized quotes that reflect your actual operations and safety performance.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
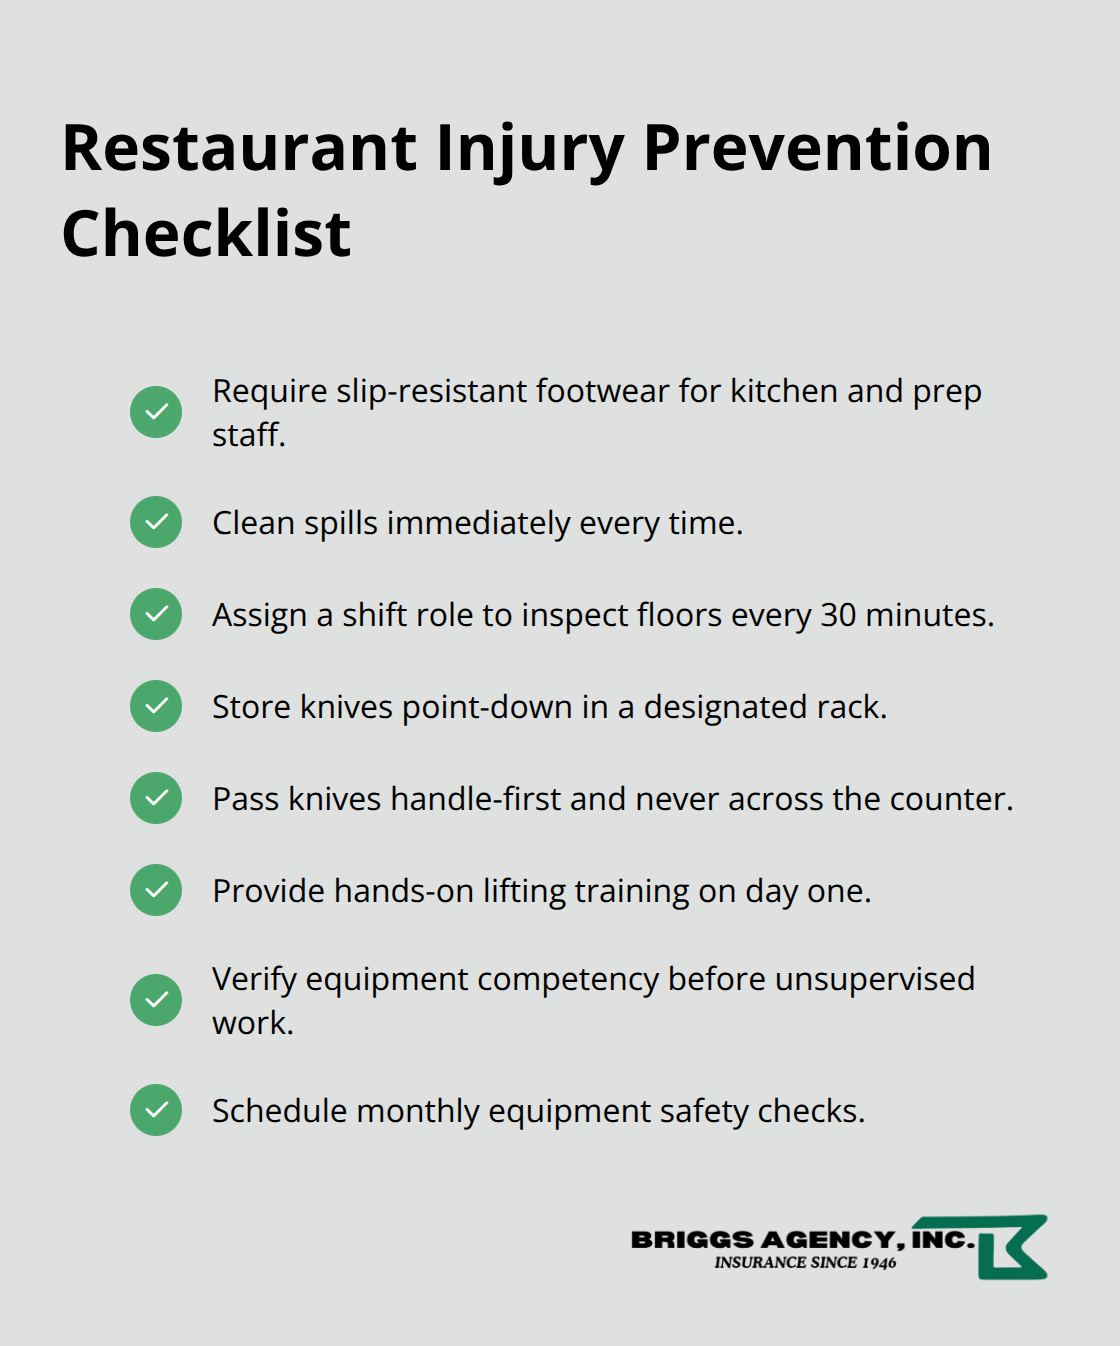
The Bears Are Coming to Indiana!

As of June 5, 2026, the Chicago Bears’ board of directors have agreed on moving forward to build a new stadium in Hammond, Indiana. Assuming the team finalizes the building site and all legal requirements, it is projected to be completed around 2029.


About Hammond

Located in Lake County in Northwest Indiana, Hammond sits on the Illinois border near the Chicago metropolitan area. With a population of approximately 77,000 people, Hammond is the 8th largest city in the state of Indiana.

First settled in 1847 and incorporated as a city in 1907, Hammond was named after George H. Hammond who was in the refrigerated meat transport industry. The city became a quick industrial hub, specializing in meatpacking, railroad transport, and manufacturing.

Today, Hammond strives in a diverse economy, continuing its’ legacy in manufacturing and transportation as well as healthcare, retail, hospitality, and much more! The city is also known for its renowned casino, the Horseshoe Hammond Casino, that serves as a great tourist destination.


Why Are the Bears Coming to Indiana?

For several years, the Bears’ have struggled to secure a deal for a stadium to be built in Chicagoland. They have attempted at pursing a site in Arlington Heights, but many disputes over taxes caused many obstacles. As a result, the Bears’ board of directors has settled on Hammond, Indiana.

Unlike Illinois, Indiana approved roughly $1 billion towards the stadium development, making it a much more attractive option. They believe that locating a stadium in Hammond would create new investments and opportunities. In addition to the financial incentives, Hammond’s location offers easy access between Indiana and Illinois. This allows for the Bears to stay connected to the Chicago area while reaching out for growth throughout Northwest Indiana.


How Does This Effect Insurance?

Moving forward with the new building initiatives, this stadium project opens many opportunities for contractors, electricians, excavators, and much more! Similarly, more business developments are likely to open in proximity to the stadium, which is great for business owners. However, as development increases, property values of surrounding homes can potentially increase. This makes construction costs higher, leading to a need for larger dwelling limits. Likewise, auto rates could increase. This is a result of higher traffic activity which leads to more auto claims.


Overall, What to Expect

With the implementation of the new stadium to Hammond, the following could be expected:

  • Construction job opportunities
  • Business developments (hotels, restaurants, etc.)
  • Increased housing demand
  • Higher property values
  • Increased tourism
  • Increased traffic and auto claims

The Bears stadium has the potential to become one of the largest developments in Northwest Indiana! While not all details are finalized, there is many opportunities for growth and development for the region.


It is crucial to regularly review your insurance coverage to ensure that you remain protected. Speak to one of our insurance professionals at Briggs Agency, and we can help review your coverage to find the best solution for you or your business!

Crown Point Trucking Insurance: Fleet Protection for Local Carriers

Running a trucking operation in Crown Point means managing risks that go far beyond standard business insurance. Your fleet faces unique exposures-from cargo liability to regulatory compliance-that require specialized protection.

At Briggs Agency, Inc., we work with local carriers every day and understand exactly what coverage gaps can cost your business. This guide walks you through the trucking insurance options that actually matter for your operation.

Why Trucking Insurance Costs More Than Standard Auto Coverage

Trucking insurance operates in a completely different risk universe than standard commercial auto policies. Indiana minimum liability for commercial trucking is $750,000 for non-hazardous freight, with requirements jumping to $5,000,000 for hazmat shipments according to FMCSA standards. That’s not a minor difference-it reflects the genuine catastrophic exposure your operation faces. A single accident involving a loaded truck can generate six-figure claims that would bankrupt a business relying on basic auto coverage.

Key reasons trucking insurance exceeds standard commercial auto costs

Standard commercial policies simply don’t account for the scale of damage a multi-ton vehicle can inflict, the value of freight you’re transporting, or the regulatory penalties that follow a compliance failure.

Cargo and Equipment Require Separate Protection

Your freight isn’t covered under vehicle damage policies. Motor truck cargo coverage protects you when goods are damaged, spoiled, or lost during transport-and this matters far more than most owner-operators realize. Temperature-controlled cargo creates an especially tricky exposure: if your refrigeration fails mid-route and spoils a load of perishables worth $50,000, standard physical damage coverage won’t touch it. You need specific provisions that cover spoilage losses tied to equipment failure. Likewise, service trucks carrying expensive tools, diagnostic equipment, or specialized aftermarket gear need riders that cover these assets separately. A deductible of $500 to $1,000 works for vehicle collision, but your equipment and cargo exposures demand different thresholds based on actual shipment values and tool inventory.

Regulatory Compliance Creates Non-Negotiable Coverage Demands

The FMCSA requires proof of insurance via forms BMC-91 or BMC-91X before you legally operate as a for-hire carrier. A lapsed policy doesn’t just cost you money-it revokes your operating authority and triggers Indiana BMV fines and registration issues. Coverage gaps can strand your fleet while you sort paperwork. Hazmat shipments demand environmental cleanup cost coverage and regulatory fine protection that standard policies exclude entirely. Indiana’s winter weather (ice, hail, thunderstorms) increases collision risk and liability claims dramatically, especially for operations running heavy truck traffic through Lake County corridors. Your policy must account for these seasonal and geographic realities, not just generic national averages.

Protect Against Underinsured Drivers and Employee Vehicle Use

Uninsured or underinsured motorist coverage becomes critical when another driver causes a six-figure accident and carries minimal coverage. Without this layer, you absorb the gap out of pocket. Non-owned and hired vehicle liability protects your operation when employees use personal or rental vehicles for business purposes-a coverage most standard policies handle poorly or exclude entirely. These gaps expose your business to significant financial risk that extends well beyond your own fleet.

Understanding these distinct coverage layers sets the foundation for selecting the right protection. The next section walks you through the specific coverage options that address these exposures and help you build a policy tailored to your Crown Point operation.

The Coverage Layers That Keep Crown Point Fleets Protected

Liability Coverage Forms Your Foundation

Liability coverage forms the foundation of any trucking operation, and the numbers matter more than most carriers realize. Indiana minimum liability sits at $750,000 for non-hazardous freight, but that floor leaves you dangerously exposed. A single accident involving your truck striking a passenger vehicle can easily generate $2 million in bodily injury claims when multiple people are injured, medical care extends over years, and lost wages accumulate. Many Crown Point carriers operate with $1 million in combined single-limit liability, which provides meaningful protection without excessive premium burden.

The real gap appears when you factor in uninsured or underinsured motorist coverage. If another driver causes a crash and carries only Indiana’s minimum $25,000 in liability, your uninsured motorist layer absorbs the difference, protecting your operation from absorbing six figures out of pocket. Without this coverage, you self-insure against other people’s inadequate policies.

Physical Damage Coverage Protects Your Assets

Physical damage coverage protects your actual assets-trucks, trailers, and cargo-and requires honest assessment of what you transport and what your vehicles are worth. Collision coverage typically carries deductibles between $500 and $2,500; choosing the right deductible involves calculating your cash flow tolerance against premium savings. A $1,000 deductible represents a practical middle ground for most fleet operations.

Comprehensive coverage handles theft, weather damage (critical during Indiana’s harsh winters), vandalism, and animal strikes. Many carriers underestimate exposure here-a severe hailstorm can damage an entire fleet in minutes, and comprehensive coverage absorbs those costs while collision does not.

Visual guide to essential trucking insurance layers - Crown Point trucking insurance

Motor Truck Cargo Coverage Matches Your Shipments

Motor truck cargo coverage specifically protects the freight you transport, and this is where operational details become essential. Temperature-controlled loads demand explicit spoilage protection if refrigeration fails; standard cargo policies won’t cover product loss from equipment breakdown. High-value shipments require cargo limits matching actual values with roughly a 20 percent cushion for growth and contingencies.

Service vehicles carrying diagnostic tools, specialized equipment, or aftermarket gear need equipment riders covering these assets separately from vehicle damage. Align deductibles to your inventory value rather than your vehicle collision deductible.

Workers Compensation Covers Your Team

Workers compensation protects employees injured on the job and covers medical expenses, rehabilitation, and wage replacement. Indiana requires this coverage for any business with employees. Strong workers comp coverage reduces your exposure when a driver sustains a back injury loading freight or suffers an accident-related injury.

Premium calculations tie directly to your payroll and job classification. Owner-operators with no employees can exclude themselves, but this decision should align with actual operational structure and growth plans. The specific coverage you select-liability limits, deductibles, cargo protection, and workers comp-directly shapes your ability to operate safely and profitably in Crown Point’s competitive transportation market. Selecting the right combination requires understanding not just what regulations demand, but what your actual operation exposes you to each day.

Finding the Right Trucking Insurance Partner

Selecting a trucking insurance provider in Crown Point requires moving beyond premium quotes and actually examining what coverage you receive and how an agency will support your operation when claims happen. Most carriers focus on price, but the cheapest quote often reflects the weakest protection. Commercial auto insurance for light-duty vehicles typically costs $250 to $400 per month, though this varies dramatically based on your safety record, driver experience, cargo type, and whether you operate hazmat routes. A quote $2,000 below market should trigger questions about what coverage limits or protections were cut to hit that number. The real cost of underinsurance emerges when a claim exceeds your limits and you’re writing checks out of pocket.

Shop Multiple Carriers for True Price Comparison

Obtain quotes from at least three specialized trucking carriers to account for the 30 to 40 percent premium variation across providers and to identify which carriers actually understand Crown Point operations versus those applying generic national pricing. Generic policies miss local exposures entirely-Lake County’s heavy truck traffic, winter weather patterns, and warehouse district concentrations create distinct risks that local brokers recognize while national carriers often ignore. An independent agent representing 15 or more A-rated carriers can shop your risk across Travelers, Liberty Mutual, Progressive, Cincinnati, Auto-Owners, Western Reserve Group, AmTrust, and Hartford simultaneously, comparing not just premiums but actual coverage structures side-by-side.

Conduct Thorough Discovery Before Accepting Quotes

The agent you select should conduct detailed discovery before quoting, asking specific questions about your vehicles, drivers, routes, and loss history over the past five years. This process takes time-don’t trust anyone who quotes within minutes of a phone call. Strong underwriting relies on tools like CAB reports to understand your safety history and identify necessary follow-up actions.

Percent figures from the guide that influence pricing and limits - Crown Point trucking insurance

Verify Claims Support and Operational Competence

Claims handling separates good agencies from mediocre ones; request references and ask how quickly the agency secures proof of insurance for new contracts-same-day certificate issuance within hours after binding demonstrates operational competence. Verify that your agent monitors BMC-91 filings actively to prevent accidental authority loss and can coordinate additional insured language when customers demand it.

Partner with Local Expertise

An independent agency in Crown Point understands the specific exposures your operation faces daily rather than applying national averages that miss what matters in your market. Local agents translate trucking regulations into practical coverage that protects your fleet against the risks you actually encounter on Lake County roads and beyond.

Final Thoughts

Protecting your Crown Point trucking operation requires more than finding the cheapest policy-the coverage decisions you make today determine whether a single accident drains your business or whether your fleet continues operating safely and profitably. Liability limits, cargo protection, physical damage deductibles, and workers compensation all work together to create a safety net that reflects your actual operational exposures rather than regulatory minimums alone. Lake County’s heavy truck traffic, winter weather patterns, and warehouse district concentrations create specific risks that national carriers miss entirely.

An independent agent representing multiple A-rated carriers can compare coverage structures side-by-side, identify gaps that standard policies leave open, and tailor protection that matches what your operation genuinely needs. This process takes time and detailed discovery, but it prevents the costly mistakes that emerge when claims exceed your limits or coverage gaps leave you exposed. Crown Point trucking insurance isn’t generic-local expertise matters because your risks differ from operations in other markets.

Contact Briggs Agency, Inc. to discuss your specific operation and receive quotes that reflect your actual exposures. We’ll conduct thorough discovery, shop your risk across carriers, and help you build a policy that keeps your fleet protected and compliant. Your business deserves protection tailored to Crown Point’s unique transportation landscape, not national averages that miss what matters in your market.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.
Logistics Fleet Insurance: Keeping Your Deliveries on Track

Your delivery fleet faces real risks every day. Vehicle accidents, cargo damage, and unexpected downtime can drain your budget fast. At Briggs Agency, Inc., we help logistics companies protect their operations with the right fleet insurance coverage.

This guide walks you through what you need to know to keep your business running smoothly.

What Fleet Insurance Covers and Why It Matters

Core Coverage Types for Logistics Operations

Fleet insurance protects your delivery operation from the financial devastation that accidents, cargo loss, and vehicle downtime create. Unlike standard commercial auto policies, fleet coverage bundles liability, physical damage, cargo protection, and workers’ compensation into one package designed for the realities of logistics work. Commercial auto liability covers third-party injuries and property damage when your driver is at fault-this is mandatory for interstate operations under Federal Motor Carrier Safety Administration rules, with minimum requirements varying depending on entity type and operating authority. Physical damage coverage pays for repairs or replacement of your vehicles after collision or comprehensive losses like theft or weather damage. Cargo insurance protects the goods you’re transporting from loss or damage in transit, which becomes critical when you’re hauling electronics, perishables, or time-sensitive medical shipments.

Four core protections in fleet insurance for logistics operations - Logistics fleet insurance

Additional Protections Your Fleet Needs

Workers’ compensation covers your employees’ medical expenses and lost wages if they suffer injury on the job, and it’s legally required in nearly every state. Many logistics operations also need hired and non-owned auto coverage when contractors use personal vehicles for deliveries, and general liability protects against slip-and-fall claims at delivery locations. These protections work together to shield your business from multiple angles of exposure that standard policies simply don’t address.

The Real Cost of Inadequate Coverage

A single accident involving your delivery vehicle can result in a lawsuit exceeding $25 million in median damages, according to nuclear verdict data showing awards have risen roughly 33% over the past decade. Fleet insurance premiums have climbed approximately 40% over the last decade, with current trucking insurance averaging over $10 per mile in 2024. Downtime from vehicle repairs drains revenue immediately-a truck sitting idle costs far more than the repair bill itself when you factor in missed deliveries and lost customer trust.

Regulatory Consequences of Operating Uninsured

Regulatory violations compound the problem; operating without proper coverage can suspend your FMCSA authority within 24 to 48 hours, shutting down your entire operation. This isn’t a minor inconvenience-it’s a complete halt to your business. The stakes demand that you understand your insurance to match your coverage to your actual operations, not guess at what you might need.

Finding the Right Coverage for Your Operation

An independent agent who understands logistics operations can compare quotes from multiple carriers and help you right-size coverage to match your specific routes, vehicle types, and cargo risks, ensuring you’re protected without overpaying for unnecessary limits. The next section explores how to evaluate providers and make this critical decision with confidence.

Essential Coverage for Your Delivery Operation

Commercial Auto Liability and Physical Damage

Commercial auto liability is non-negotiable for any logistics business operating across state lines. The Federal Motor Carrier Safety Administration requires minimum liability coverage that varies depending on your entity type and operating classification. Physical damage coverage protects your vehicles from collision and comprehensive losses, but here’s what matters operationally: a single repair bill for a delivery truck can easily reach $5,000 to $15,000, and that’s before you account for the revenue lost while the vehicle sits in the shop.

Telematics systems that monitor hard braking, rapid acceleration, and following distance can reduce your insurance premiums by 10% to 30% according to industry data, so insurers now actively reward fleets that implement these safety tools. These systems give you real-time visibility into driver behavior and vehicle health, which translates directly into lower claims and better rates.

Percent reductions in insurance premiums from telematics systems

Workers’ Compensation and Contractor Coverage

Workers’ compensation is mandatory in nearly every state and covers employee medical expenses and lost wages from job-related injuries. The coverage becomes especially important when your team handles heavy packages or works in challenging weather conditions that increase accident risk. Hired and non-owned auto coverage protects you when contractors or employees use their personal vehicles for deliveries, which is common in last-mile operations where independent drivers handle final-leg delivery to customer doors.

This coverage fills a critical gap because your standard commercial policy typically excludes vehicles you don’t own, leaving you exposed if a contractor’s vehicle is involved in an accident while making a delivery on your behalf. Without this protection, a single incident can create significant liability exposure.

Cargo and General Liability Protection

Cargo insurance protects the actual goods in transit from loss, damage, or theft, and becomes essential when you move high-value electronics, temperature-sensitive perishables, or time-critical medical shipments. General liability rounds out your protection by covering slip-and-fall claims at delivery locations, property damage to customer facilities, and third-party bodily injury claims that fall outside vehicle-related incidents.

The cost of these coverages varies based on your fleet size, vehicle types, delivery routes, driver safety records, and cargo value. An independent agent who understands logistics operations allows you to right-size coverage to your actual risk profile rather than paying for unnecessary limits or discovering gaps when a claim occurs.

Navigating State-Specific Requirements

State-specific requirements add complexity to your coverage strategy. California imposes stricter workers’ compensation mandates, Texas requires specific intrastate cargo coverage, and New York mandates supplementary uninsured motorist protection. If your deliveries cross state lines, multi-state coverage strategies matter significantly to your compliance and protection.

An agent experienced in logistics can ensure your policy meets all applicable FMCSA filings and state regulations while positioning your coverage to support growth without constant policy adjustments. The next section explores how to evaluate insurance providers and select a partner who understands your operation’s specific needs.

Selecting a Fleet Insurance Partner Who Understands Logistics

Why Logistics Expertise Matters in Your Insurance Choice

Picking the right insurance provider matters more than most logistics owners realize. A general commercial agent who handles restaurants and contractors won’t understand the specific exposures in last-mile delivery, the impact of telematics on your rates, or how state-by-state regulations affect your coverage strategy. You need an agent who grasps that a 10-minute pre-trip inspection can keep trucks off the DOT roadside inspection list, where nearly one in five trucks face pulls, and who knows how cargo securement violations under 49 CFR 393 create both regulatory and insurance risk. The difference between a generalist and a specialist appears immediately: a specialist asks about your specific routes, vehicle types, driver experience, and loss history before recommending coverage limits, while a generalist plugs numbers into a form and sends you a quote.

Hub-and-spoke showing key capabilities of a logistics-focused insurance agent - Logistics fleet insurance

Comparing Quotes Across Multiple Carriers

An independent agent representing multiple top-rated carriers can compare quotes across different underwriters, but not all agents possess equal expertise in logistics. This matters because a fleet transporting temperature-sensitive pharmaceuticals faces entirely different cargo risks than one delivering packages, and your coverage should reflect that distinction. When you request quotes, ask each agent whether they understand FMCSA filing requirements and can confirm that your BMC-91 certificate posts within 24 to 48 hours of binding coverage, since gaps in authority suspension can halt your entire operation.

Evaluating Claims Support and Responsiveness

The claims experience separates adequate providers from true partners in your business. When a driver causes an accident involving a $25 million nuclear verdict scenario, you need responsive guidance and advocacy, not a claims line that takes three days to return calls. Request references from current logistics clients and ask specifically how quickly the agent responded when a claim occurred and whether the carrier’s adjuster worked collaboratively to resolve the situation. Fleet insurance premiums have surged over the past decade, so cost matters, but the cheapest quote often comes from carriers with weak claims support or limited willingness to work with specialized logistics operations.

Risk Management Resources and Long-Term Value

Ask whether any provider you consider offers risk management resources like fleet assessments, driver training recommendations, or telematics guidance, since these services demonstrate a commitment to reducing your losses rather than just collecting premiums. A provider who actively helps you implement safety programs and driver monitoring can reduce accidents by 20 to 40 percent according to industry data, which translates directly into better renewal rates and lower long-term costs. An independent agent with logistics experience can tailor policies to your actual operation rather than applying a one-size-fits-all approach, ensuring you’re protected without overpaying for unnecessary limits.

Final Thoughts

Proper logistics fleet insurance protects your operation from the financial devastation that accidents, cargo loss, and vehicle downtime create. Nuclear verdicts averaging $25 million and premiums that have climbed 40% over the past decade show why getting coverage right matters to your bottom line. Working with a local agent who understands logistics operations ensures you avoid coverage gaps that turn into catastrophic losses while preventing overpayment for limits you don’t need.

An independent broker representing multiple carriers compares quotes across underwriters, confirms your FMCSA filings post correctly, and helps you implement telematics and safety programs that reduce premiums by 10% to 30%. This expertise translates into competitive pricing, proper protection, and responsive claims support when incidents occur. A generalist agent won’t ask the right questions about your routes, cargo types, or driver experience, leaving you exposed to gaps or unnecessary costs.

At Briggs Agency, Inc., we’ve served Crown Point and surrounding communities since 1946 as a family-owned independent agency representing multiple top-rated carriers. Our experienced local agents compare options and tailor logistics fleet insurance policies to your specific needs rather than applying a one-size-fits-all approach. Contact us today to discuss your fleet’s specific risks and get a customized quote that protects your business.

The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.