
Body Shop Insurance
Auto body shops repair vehicles damaged by collisions, weather, vandalism, and everyday wear. This work may involve welding, frame straightening, painting, sanding, glass replacement, and the use of specialized tools and chemicals. These operations can expose a business to fires, injuries, property damage, equipment losses, and damage to customer vehicles.
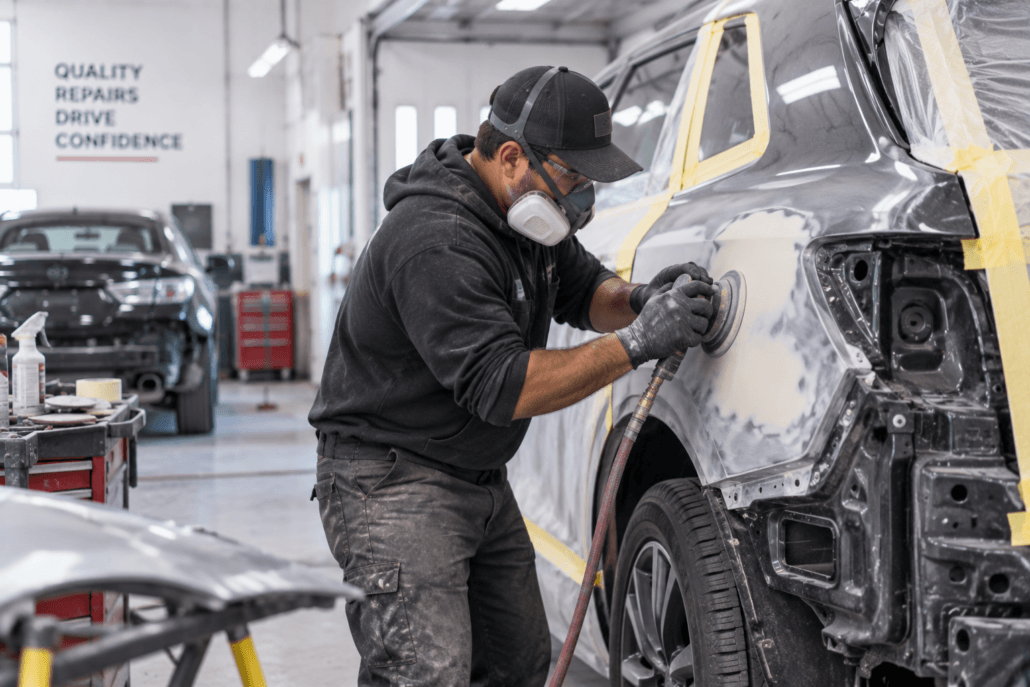 Body shop insurance can help protect your business against certain risks involving liability, employees, buildings, equipment, and vehicles left in your care. Coverage can be tailored to your operations, whether you run a small independent collision repair shop or a larger facility with multiple technicians and service bays.
Who May Need Body Shop Insurance?
Insurance coverage may be appropriate for businesses such as:
- Auto body and collision repair shops
- Automotive paint shops
- Paintless dent repair businesses
- Frame and alignment shops
- Auto glass repair and replacement shops
- Vehicle restoration businesses
- Mobile dent and cosmetic repair services
- Custom paint and vehicle modification shops
The appropriate coverage may depend on the services provided, annual revenue, number of employees, building ownership, paint booth operations, equipment values, test-driving practices, and the number and value of customer vehicles kept on the property.
Common Body Shop Insurance Coverages
Garage Liability Insurance
Garage liability insurance may help protect a body shop against certain third-party bodily injury or property damage claims resulting from its operations. For example, a customer could be injured inside the shop, or completed repair work could allegedly contribute to an accident or additional vehicle damage.
Garagekeepers Insurance
Customer vehicles may be damaged by fire, theft, vandalism, severe weather, faulty lifts, or collisions while being moved or test-driven. Garagekeepers insurance may help cover certain physical damage to customers’ vehicles while they are in the business’s care, custody, or control.
Garagekeepers coverage is different from garage liability insurance. Many body shops may need both forms of protection.
Commercial Property Insurance
Commercial property insurance may help protect a shop’s building and business property against certain covered losses. Covered property may include frame machines, paint booths, welding equipment, compressors, tools, computers, office furnishings, replacement parts, and supplies.
Business income coverage may also be available to help with certain lost income and continuing expenses if a covered event temporarily interrupts operations.
Workers’ Compensation Insurance
Body shop employees may be exposed to burns, cuts, respiratory hazards, repetitive injuries, falling objects, and accidents involving tools or vehicles. Workers’ compensation insurance may provide medical and wage-replacement benefits to qualifying employees who experience work-related injuries or illnesses. Requirements vary by state.
Commercial Auto Insurance
A body shop may own tow trucks, courtesy cars, parts-delivery vehicles, or other business-use automobiles. Commercial auto insurance may provide liability and physical damage coverage for qualifying business-owned vehicles.
Pollution Liability Insurance
Paints, solvents, fuels, oils, and other chemicals may create environmental risks. Pollution liability insurance may help cover certain cleanup expenses and third-party claims arising from qualifying pollution incidents. Standard liability or property policies may limit or exclude some pollution-related losses.
Body Shop Insurance FAQs
How much does body shop insurance cost?
Costs vary based on services, payroll, revenue, claims history, property values, equipment, paint operations, coverage limits, and the number and value of customer vehicles handled.
Does body shop insurance cover customer vehicles?
Garagekeepers insurance may cover certain damage to customer vehicles while they are in the shop’s care, custody, or control. Coverage depends on the policy and cause of loss.
Are tools and equipment automatically covered?
Not necessarily. Tools and machinery may require commercial property, inland marine, or equipment breakdown coverage. Limits and deductibles vary by policy.
Does an insurance policy cover every accident or loss?
No. Policies contain conditions, exclusions, deductibles, and coverage limits. Shop owners should carefully review their policies and accurately disclose their services, property, equipment, and business practices.
