
Concrete Contractors Insurance
Concrete work is essential to homes, businesses, roads, and other structures, but it also comes with significant risks. From property damage and employee injuries to equipment theft and vehicle accidents, one unexpected event can create costly disruptions. Concrete contractors insurance helps protect your business from many of the risks associated with pouring, finishing, repairing, and transporting concrete.
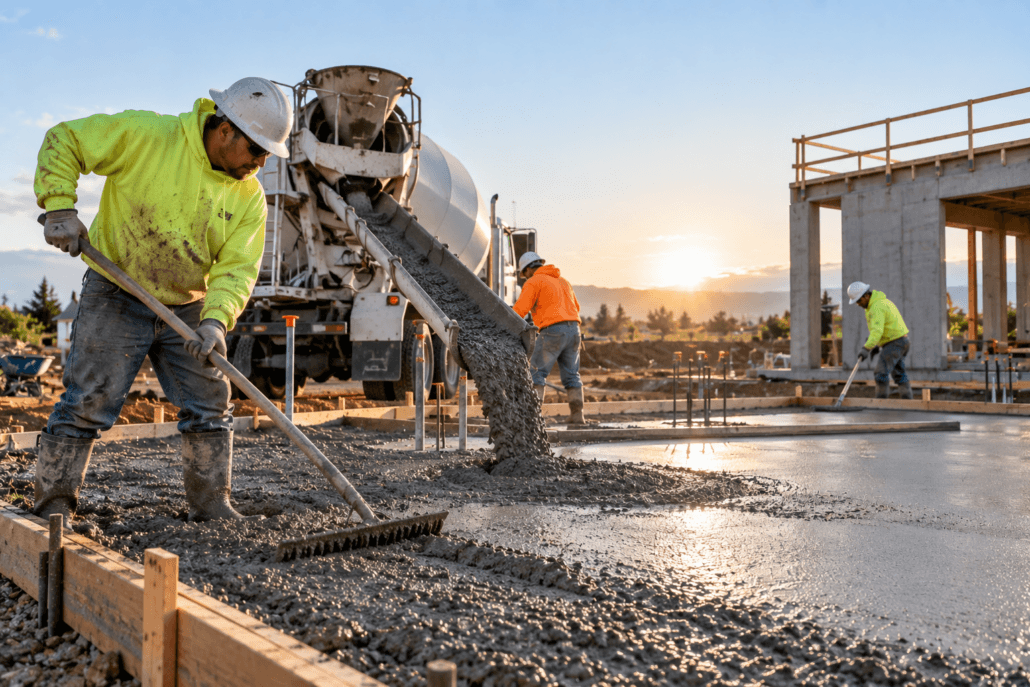
Whether you work on residential foundations, commercial buildings, driveways, sidewalks, patios, or other concrete projects, insurance coverage can be tailored to the size and scope of your operations.
Why Do Concrete Contractors Need Insurance?
Concrete contractors regularly work with heavy equipment, large vehicles, specialized tools, and potentially hazardous materials. Crews may also perform work on active construction sites alongside other contractors. Even with strong safety procedures in place, accidents can happen.
A customer could trip over equipment, freshly poured concrete could damage nearby property, or an employee could be injured while operating machinery. Without appropriate insurance, your business may be responsible for medical expenses, repairs, legal costs, or other damages.
Insurance can also help concrete contractors meet licensing requirements and satisfy the coverage requirements found in many construction contracts.
Insurance Coverage for Concrete Contractors
The coverage needed by a concrete contractor depends on factors such as the services provided, number of employees, equipment used, and types of projects completed. A contractor’s insurance program may include several different types of coverage.
General Liability Insurance
General liability insurance may help protect your business when its operations result in third-party bodily injury or property damage. It may also cover certain legal expenses if your business is sued over a covered incident.
Commercial Auto Insurance
Personal auto insurance generally does not cover vehicles used primarily for business. Commercial auto insurance may help protect company-owned cars, trucks, and vans used to transport workers, tools, materials, or equipment.
Workers’ Compensation Insurance
Concrete work is physically demanding and may expose employees to falls, strains, machinery accidents, and other hazards. Workers’ compensation insurance may help pay eligible medical expenses and lost wages when an employee suffers a work-related injury or illness. Requirements vary by state.
Contractors’ Tools and Equipment Coverage
Concrete mixers, saws, compactors, finishing tools, and other equipment can be expensive to repair or replace. Contractors’ tools and equipment coverage may help protect movable business property if it is stolen, damaged, or lost due to a covered event.
Commercial Property Insurance
If your business owns or leases an office, shop, storage facility, or other physical location, commercial property insurance may help cover the building and its contents against certain covered losses.
Umbrella or Excess Liability Insurance
Umbrella or excess liability insurance may provide additional protection when the limits of an underlying liability policy are exhausted by a covered claim.
Concrete Contractors Insurance FAQs
How much does concrete contractor insurance cost?
Insurance costs vary based on payroll, revenue, services performed, claims history, coverage limits, number of vehicles, and other risk factors. Comparing coverage options can help you find a policy suited to your business.
What is a policy limit?
A policy limit is the maximum amount an insurer may pay for a covered claim or during the policy period. Different coverages within the same policy may have separate limits.
What is an insurance deductible?
A deductible is the amount the policyholder is responsible for paying toward a covered loss before insurance contributes. Deductibles can vary by policy and type of coverage.
Does an insurance policy cover every accident?
No. Insurance policies contain conditions, exclusions, limits, and coverage requirements. Review your policy carefully and speak with an insurance professional to understand what is and is not covered.
How often should a contractor review their insurance?
It is a good idea to review coverage at least once a year and whenever the business adds employees, vehicles, equipment, services, or larger projects.
